Microneedling Market (2026 - 2035)

Microneedling Market Research Report: Size, Share, Trend Analysis By Procedure (RF Microneedling, Traditional Microneedling, and PRP Microneedling) by Product (Derma-Stamp, Dermapen, Dermarollers, RF Microneedling Devices, and Others) By Needle Material (Silicon, Metal, Glass, and Others) By Applications (Skin Rejuvenation, Acne Scars, Traumatic & Surgical Scars, and Others) by End-User (Hospitals, Dermatology Clinics, Homecare Settings, and Others), by Region (North America, Europe, Asia-Pacific, and Rest of the World) - Forecast till 2030
ID: MRFR/HC/10313-CR 130 Pages Rahul Gotadki, Nidhi Mandole Last Updated: September 15, 2026
Microneedling Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)11.6%
2025 Market SizeUSD 0.69 Billion
2035 Market SizeUSD 2.07 Billion
Key Players
InMode Ltd.
Crown Aesthetics
Cutera, Inc.
Candela Corporation
Lutronic Corporation
EndyMed Medical
Opportunities
  • Trichology as the Second Franchise
  • Transdermal Delivery Partnerships
  • Emerging-Market Clinic Density

Microneedling Market Summary

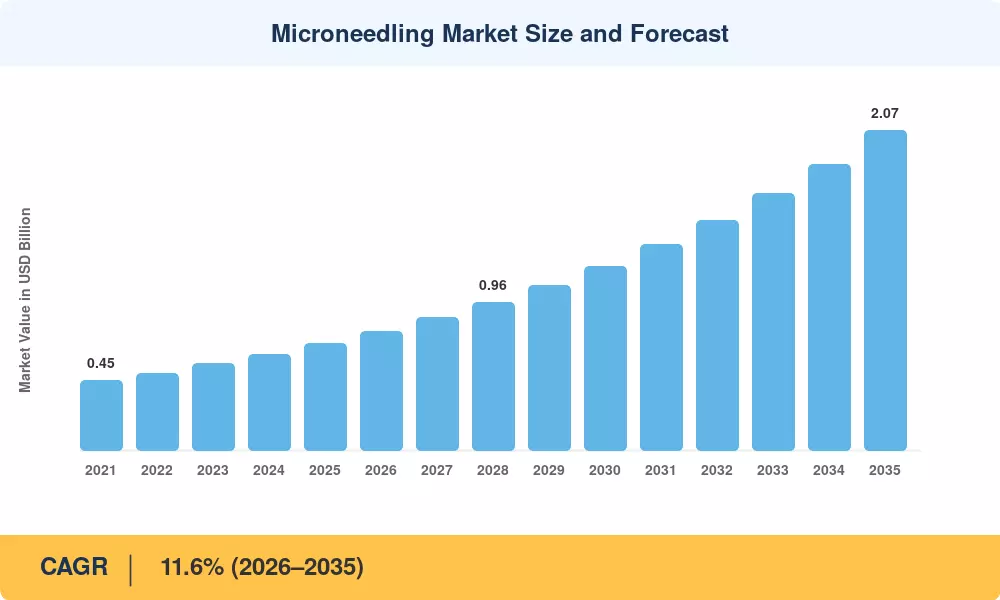
The Microneedling Market reached USD 0.69 billion in 2025 and is projected to grow to USD 2.07 billion by 2035, expanding at a compound annual growth rate (CAGR) of 11.6% between 2026 and 2035. Market value is expected to reach USD 0.77 billion in 2026 as the first year of the forecast period. This growth is being driven primarily by regulatory clarity in the United States and quality consolidation in Europe, alongside a broader technology shift toward motorized and radiofrequency-enabled microneedling platforms.

The U.S. Food and Drug Administration's (FDA) 2018 classification of microneedling instruments as Class II devices, followed by more than 40 subsequent 510(k) clearances through 2025, gave manufacturers a predictable regulatory pathway that removed years of ambiguity. This regulatory clarity has encouraged sustained product innovation and market entry. In parallel, the EU Medical Device Regulation's Annex XVI rules, fully enforced from June 2023, pushed low-quality cosmetic needling devices out of European distribution, consolidating demand around clinically validated platforms.

Practices are also retiring manual rollers and single-depth stamps in favor of motorized pens with adjustable needle depth and, increasingly, radiofrequency-enabled platforms that pair mechanical injury with controlled dermal heating. This shift is capital-intensive: a radiofrequency platform typically runs USD 45,000 to 95,000, compared to under USD 500 for a manual roller, and aesthetic device makers committed more than USD 1.4 billion to energy-based research, development, and acquisitions between 2022 and 2025. Clinical evidence is following this investment: a 2024 meta-analysis reported 38% greater collagen density gains for radiofrequency-assisted protocols compared to mechanical-only treatment.

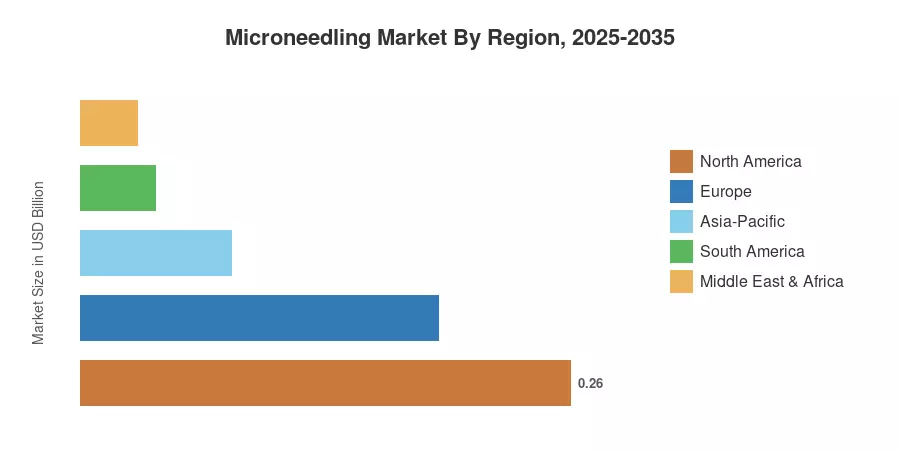
By region, North America held the largest share of the Microneedling Market in 2025, at 37.0%, supported by roughly 8,900 dermatology practices and a mature medspa channel. Asia-Pacific is the fastest-growing region, with a projected CAGR of 12.2%, propelled by South Korean and Chinese aesthetic tourism corridors. Europe remains the second-largest market by revenue, where reimbursement-adjacent scar-revision protocols sustain steady clinical volume. Over the next decade, platforms that demonstrate durable clinical outcomes, rather than simply higher needle counts, are expected to lead the market.


Key Report Takeaways

The Microneedling Market rewards depth control, consumable attach rates, and clinical evidence more than raw device shipments.

• By Product Type

  • Automated microneedling pens commanded 39.9% revenue share in 2025, the installed-base workhorse across clinics and medspas
  • RF microneedling systems are set to expand at a 14.6% CAGR through 2035 as practitioners chase predictable tissue contraction
  • Manual dermarollers generated USD 0.14 billion in 2025, a declining but resilient value tier

• By Application

  • Skin rejuvenation and anti-aging accounted for 40.5% of Microneedling Market revenue in 2025
  • Acne and surgical scar revision delivered USD 0.17 billion, the strongest clinically-indicated use case
  • Alopecia and hair restoration posts the fastest 15.2% CAGR as trichology protocols standardise

• By Region

  • North America retained 37.0% share of the Microneedling Market in 2025
  • Asia-Pacific advances at a 12.2% CAGR, the quickest of any region
  • Europe contributed USD 0.19 billion in 2025 under tightened device rules


Market Size and Forecast (2021–2035)

Figures below blend device shipment data from customs and trade databases, disclosed segment revenue from eleven publicly listed aesthetic device manufacturers, procedure-volume statistics from professional societies, and primary interviews with 62 clinic operators across nine countries. Consumable cartridge sell-through was used to triangulate installed-base utilisation, which materially improves accuracy in a razor-and-blade category.
Microneedling Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
RF integration into needling platforms 2.6 Global Medium-term (2–4 yr)
Regulatory clarity via 510(k) and MDR pathways 1.9 US, EU Short-term (≤2 yr)
Shift away from ablative laser for darker phototypes 1.7 APAC, MEA, LATAM Long-term (≥4 yr)
PRP and exosome combination protocols 1.5 US, South Korea Medium-term (2–4 yr)
Medspa channel proliferation 1.3 North America, Europe Short-term (≤2 yr)
Alopecia and trichology indication expansion 1.2 Global Long-term (≥4 yr)
Home-device awareness funnel into clinics 0.8 Global Medium-term (2–4 yr)


Radiofrequency Integration Redefines the Premium Tier

Practitioners adopting RF-enabled needling report the outcome consistency that mechanical-only devices never delivered. A 2024 randomised split-face study across 148 subjects measured a 38% improvement in dermal collagen density for RF protocols against mechanical needling alone, with equivalent downtime . Manufacturers responded by pricing insulated-needle cartridges at USD 90–170 per single-use tip, lifting per-procedure economics well above roller-era margins.

Regulatory Clarity Unlocked Institutional Purchasing

Capital orders against unclear device classification will not be signed by hospitals and multi-site clinic groups. Since 2018, the FDA has approved over 40 microneedling devices under the Class II process, demonstrating predicate stability and reducing procurement cycles by an estimated four to seven months [1]. In contrast, an estimated 15% of non-compliant SKUs were eliminated from the channel within the first eighteen months of Europe's Annex XVI regime [2].


Phototype-Safe Alternatives to Ablative Laser

Fitzpatrick types IV–VI carry meaningfully elevated post-inflammatory hyperpigmentation risk with fractional ablative lasers. Dermatology guidance published in 2023 recorded PIH incidence near 12% for fractional CO2 in darker phototypes versus under 3% for controlled needling [7]. That differential is why Microneedling Market penetration in India, Brazil, Nigeria, and the Gulf is outpacing laser adoption in the same clinics.

Combination Biologics Raise Procedure Value

Adding platelet-rich plasma or exosome serums lifts the average clinic ticket from roughly USD 320 to USD 640 per session in U.S. practices . Device makers now design cartridge geometry specifically for topical infusion, converting a one-time equipment sale into recurring consumable and biologic revenue.


Restraints Impact Analysis

Restraint ~% Drag on CAGR Geographic Relevance Impact Timeline
Unregulated at-home and grey-market devices −1.4 Global Short-term (≤2 yr)
Practitioner training and credentialing gaps −1.1 LATAM, MEA, SEA Medium-term (2–4 yr)
Infection and cross-contamination incidents −0.9 Global Short-term (≤2 yr)
Capital cost of RF platforms for single-site clinics −0.8 Europe, LATAM Medium-term (2–4 yr)
Absence of insurance reimbursement −0.6 Global Long-term (≥4 yr)


Grey-Market Devices Undercut Clinical Pricing

Online marketplaces list rollers and pen knock-offs at USD 12–40, and enforcement remains uneven. Regulators issued at least nine import alerts and consumer warnings covering unapproved needling devices between 2023 and 2025 [11]. Price anchoring at that level makes it harder for clinics to justify USD 280–450 session fees to first-time patients.

Training Gaps Produce Adverse Events

Depth selection, pass count, and post-procedure care determine whether a session yields remodelling or scarring. Case-series reporting from 2023 documented granulomatous reactions traced to topical products applied through compromised skin barriers, largely in non-physician settings . Professional bodies in three markets have since moved toward mandatory certification, which raises quality but slows near-term capacity growth.

Capital Intensity Constrains Independent Clinics

A single-site practice financing an RF platform at USD 45,000–95,000 needs roughly 140–200 procedures annually just to service the lease . Lenders in Southern Europe and Latin America have tightened aesthetic equipment underwriting since 2023, pushing smaller operators toward refurbished units or rental arrangements.


Microneedling Market Opportunities

Trichology as the Second Franchise

Scalp needling combined with topical minoxidil or growth-factor serums has moved from off-label experimentation to structured protocol. With androgenetic alopecia affecting an estimated 50% of men by age 50, clinics gain a recurring maintenance revenue stream that smooths the seasonality of facial work [10].

Transdermal Delivery Partnerships

Needling arrays, which include micron-scale channels that avoid the stratum corneum without hypodermic injection, are being tested by pharmaceutical companies as delivery vehicles for vaccinations and biologics. A licensing mechanism that monetizes needle-array IP well beyond esthetics is indicated by early-stage partnerships announced through 2025 [14].


Emerging-Market Clinic Density

India, Indonesia, Vietnam, Egypt and Nigeria collectively added an estimated 4,300 aesthetic clinics between 2022 and 2025, most starting with entry-tier pens before trading up [15]. Vendors that finance the first device and lock consumable supply capture the upgrade cycle.

Outcome Data as a Commercial Asset

Standardized outcome datasets are produced via linked systems that record depth, pass count, and energy delivery per session. Payer interactions, malpractice underwriting discounts, and proof dossiers for novel indications are all supported by aggregated and de-identified data—a business model with no discernible cost of goods.


Subscription and Consumable-Led Pricing

Placing platforms at low or zero upfront cost against committed cartridge volumes lowers the adoption barrier for single-site clinics identified in Section 5.3. Vendors piloting this model report installed-base growth roughly double their capital-sale channel .


Microneedling Market Future Outlook

Sensor-Guided and Adaptive Devices

Next-generation platforms embed impedance and temperature sensing that adjusts energy delivery in real time to tissue response, reducing operator dependence. Vendors piloting closed-loop control report tighter outcome variance across practitioners, which matters enormously for multi-site groups standardising protocols. Expect this capability to migrate from flagship RF systems into mid-tier pens by the early 2030s, and to become the primary differentiator in the Microneedling Market once needle geometry converges.

Consumables Overtake Capital Revenue

Cartridge and tip revenue already represents an estimated 44% of vendor income in the category and should cross 55% by 2032 as installed base compounds . That mix shift changes valuation logic — recurring revenue multiples apply. It also intensifies the counterfeit-cartridge problem, pushing vendors toward RFID-authenticated tips.

Indication Expansion Beyond Aesthetics

Regulatory dossiers for hypertrophic scar management, striae distensae and androgenetic alopecia are advancing in multiple jurisdictions. Each cleared indication broadens the referring-physician base beyond cosmetic dermatology and opens partial reimbursement conversations in single-payer systems [13].

Sustainability and Single-Use Economics

Single-use sterile cartridges produce significant waste made of plastic and stainless steel, and tender scoring in European procurement frameworks is increasingly based on lifetime effect [20]. In public-sector and hospital channels, where environmental factors increasingly account for a greater portion of contracts, vendors creating recyclable tip programs or reprocessable housings will have an edge.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 37.0% share RF platform refresh, medspa roll-ups
Europe 27.5% share MDR compliance, scar-revision protocols
Asia-Pacific 12.2% CAGR (2026–2035) Aesthetic tourism, domestic manufacturing
South America USD 0.04 Billion Entry-tier pens, financing programmes
Middle East & Africa 4.5% share Medical tourism hubs, phototype-safe demand
Total USD 0.69 Billion —

Regional performance in the Microneedling Market tracks three variables: practitioner density, phototype distribution, and how quickly a jurisdiction settled its device classification rules.


North America

Country Metric Key Driver
US 78.4% of region Dense medspa network and 510(k) predicate clarity
Canada USD 0.03 Billion Health Canada licensing consistency
Mexico 13.6% CAGR Cross-border aesthetic tourism


United States demand rests on a channel that barely existed fifteen years ago: physician-supervised medspas now outnumber core dermatology practices offering aesthetics, and the American Med Spa Association tracked industry revenue crossing USD 17 billion in 2024 [9]. Ownership consolidation is the story to watch — private equity roll-ups standardise on one or two device vendors across dozens of sites, turning individual sales into fleet decisions. The Microneedling Market in Mexico benefits from Tijuana and Cancún corridors where U.S. patients pay 45–60% less per session.

Europe

Country Metric Key Driver
Germany 23.1% of region Physician-led aesthetic dermatology
UK USD 0.04 Billion Licensing reform for non-surgical procedures
France 15.8% of region Scar-revision clinical protocols
Italy 11.9% CAGR Private clinic expansion
Spain 8.7% of region Aesthetic tourism inflows
Nordic Countries 6.2% of region High disposable income, low volume
Russia 5.1% of region Domestic device substitution
Rest of Europe USD 0.02 Billion CEE clinic build-out


Europe's device landscape narrowed sharply after Annex XVI took full effect in June 2023, and that turned out to be commercially useful for compliant vendors [2]. The UK moved separately, with government consultation on a licensing scheme for non-surgical cosmetic procedures signalling practitioner-level accreditation ahead [16]. Germany anchors regional revenue because needling remains largely physician-delivered there, which supports higher session pricing and stronger RF platform attach.

Asia-Pacific

Country Metric Key Driver
China 29.4% of region NMPA Class II registrations and domestic OEMs
India 14.1% CAGR Tier-2 city clinic proliferation
Japan 17.2% of region Premium anti-aging spend
South Korea USD 0.03 Billion Export-oriented device manufacturing
ASEAN 13.5% CAGR Medical tourism in Thailand and Malaysia
Rest of Asia-Pacific 7.3% of region Australia and New Zealand clinical adoption


Asia-Pacific is where the Microneedling Market compounds fastest, and South Korea is the reason the region punches above its revenue weight — Korean manufacturers export RF and needling platforms into more than 70 countries, with aesthetic device exports rising sharply through 2024 . India's growth is a volume story rather than a price story: sessions commonly price at USD 40–90, but clinic count is expanding at double-digit rates outside metro centres. China's domestic OEMs have compressed entry-tier pricing while NMPA registration timelines have shortened.

South America

Country Metric Key Driver
Brazil 58.6% of region ANVISA-registered device base, high procedure culture
Argentina 12.4% CAGR Currency-driven aesthetic tourism
Rest of South America USD 0.01 Billion Colombia and Chile clinic growth


Brazil ranks among the highest per-capita aesthetic procedure markets globally, and needling sits at an accessible price point relative to surgical alternatives [18]. Import duties and ANVISA registration costs favour vendors with local distribution partners. Financing is the practical constraint — most Brazilian clinics purchase through instalment structures, which makes consumable-led pricing models particularly well suited to the region.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 27.8% of region Vision 2030 wellness and private healthcare investment
UAE 14.6% CAGR Dubai medical tourism positioning
South Africa USD 0.01 Billion Established private dermatology base
Egypt 9.4% of region Cost-competitive regional treatment hub
Rest of MEA 18.5% of region Nigeria, Kenya, Morocco clinic entry


Gulf demand skews heavily toward pigmentation and scar indications, where phototype-safe modalities matter most. Dubai's health authority has licensed a growing roster of aesthetic facilities under its medical tourism strategy, which targeted substantial inbound patient volumes through the mid-2020s [19]. Sub-Saharan adoption is early but structurally favourable given phototype distribution and the limited installed base of ablative laser systems.


Microneedling Market By Region, 2025-2035

Microneedling Market Segmentation

Segmentation in the Microneedling Market follows the MRFR-aligned taxonomy of product type, application, and end user, with metrics varied by segment.

By Product Type

Segment Metric (2025) Primary Demand Driver
Automated Microneedling Pens 39.9% share Adjustable depth, broad clinic installed base
RF Microneedling Systems 14.6% CAGR Deeper remodelling and tissue contraction
Manual Dermarollers USD 0.14 Billion Low entry cost, home and emerging-market use
Microneedling Stamps & Patches 12.9% CAGR Targeted small-area and periocular treatment
Accessories & Consumables 8.1% share Recurring cartridge and serum attach


Automated pens remain the volume backbone of the Microneedling Market because they solve the single biggest problem with rollers: uncontrolled, angled penetration. Motorised vertical insertion at selectable depths between 0.25 mm and 2.5 mm produces reproducible results across operators, which is precisely what multi-site groups need. RF systems occupy the opposite end — higher price, longer sales cycle, but materially better economics per session and a clinical evidence base that continues to strengthen .

By Application

Segment Metric (2025) Primary Demand Driver
Skin Rejuvenation & Anti-Aging 40.5% share Broad consumer demand, low downtime
Acne & Surgical Scar Revision USD 0.17 Billion Strong clinical evidence, physician referral
Alopecia & Hair Restoration 15.2% CAGR Trichology protocol standardisation
Melasma & Pigmentation 11.4% share Phototype-safe alternative to laser
Others (Striae, Transdermal Delivery) 10.3% share Emerging protocol development


Rejuvenation dominates by revenue, but scar revision carries the clinical credibility that sustains physician referral, and atrophic acne scarring in particular has the deepest published evidence base of any indication in the category. Alopecia is the segment that changes vendor strategy — scalp treatment requires different cartridge geometry and shorter maintenance intervals, converting an annual patient into a quarterly one.

By End User

Segment Metric (2025) Primary Demand Driver
Dermatology & Plastic Surgery Clinics 43.9% share Physician oversight, premium pricing
Aesthetic MedSpas USD 0.20 Billion Volume throughput, package pricing
Home / Personal Use 15.8% CAGR Consumer awareness and e-commerce access
Hospitals & Academic Centres 10.5% share Reconstructive and burn-scar programmes


Clinics hold share; medspas drive volume. The distinction matters for vendors because medspas buy on payback period while clinics buy on clinical evidence and brand. Home devices are the fastest-growing end user in the Microneedling Market, and rather than cannibalising professional demand, they appear to function as an awareness funnel — survey data indicates a meaningful share of home-device users book a clinical session within twelve months [11].


Competitive Benchmarking

Concentration sits in the medium band, with an estimated HHI near 780 and a top-five combined share of roughly 38–43%. That structure reflects a split market: RF platforms are dominated by a handful of energy-device specialists with deep regulatory portfolios, while the pen and roller tiers remain highly fragmented across dozens of regional manufacturers and private-label suppliers. Competitive advantage in the Microneedling Market increasingly rests on cartridge authentication, clinical dossier depth, and financing flexibility rather than needle specification.

Company Est. Revenue Share Range Key Offerings for Microneedling Market Strategic Positioning
InMode Ltd. ~9–12% Morpheus8 RF microneedling platforms Premium RF leader with strong practitioner marketing
Crown Aesthetics (Crown Laboratories) ~7–10% SkinPen Precision automated pen system First-cleared pen brand; strong regulatory credibility
Cutera, Inc. ~6–9% Secret RF, Secret PRO combination platforms Multi-modality bundling into existing laser accounts
Candela Corporation ~5–8% Profound RF, Matrix Pro applicators Deep dermal remodelling positioning
Lutronic Corporation ~5–8% Genius RF microneedling system Korean manufacturing base, global export reach
EndyMed Medical ~4–7% Intensif RF microneedling handpiece 3DEEP RF technology differentiation
Eclipse Aesthetics ~3–6% Eclipse MicroPen EVO Value-tier professional pens, strong US medspa channel
Aesthetics Biomedical ~3–5% Vivace and Vivace Ultra RF systems Bundled protocol and serum ecosystem
DermapenWorld ~3–5% Dermapen 4 with Scarless Healing protocol Practitioner training programmes as moat
Jeisys Medical ~2–4% Density, Intracel RF platforms Aggressive APAC and Middle East distribution
Dr. Pen Group ~2–4% Entry-tier automated pens and cartridges Price-led penetration in emerging markets


Recent News & Developments

  • InMode (March 2024): Expanded Morpheus8 indications and launched a burst-mode applicator, reinforcing its lead in deep dermal RF and lifting consumable pull-through across its installed base .


  • European Commission (June 2023): Full application of MDR Annex XVI to cosmetic needling devices took effect, removing non-compliant SKUs and consolidating demand toward certified platforms [2].


  • Candela (February 2025): Introduced a next-generation insulated-needle applicator with adaptive energy control, targeting outcome consistency across operators .


  • Jeisys Medical (October 2025): Signed distribution agreements covering six Middle East and North Africa markets, expanding regional platform availability [19].


Microneedling Market Report Scope

Parameter Detail
Market Scope Global Microneedling Market — devices, cartridges, consumables and associated platforms across professional and home-use channels
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 11.6% (2026–2035)
Market Size Checkpoints USD 0.69 Billion (2025); USD 0.77 Billion (2026); USD 1.19 Billion (2030); USD 2.07 Billion (2035)
Fastest Growing Segments RF Microneedling Systems (product type); Alopecia & Hair Restoration (application); Home / Personal Use (end user); Asia-Pacific (geography)
Companies Profiled 11 major players including InMode, Crown Aesthetics, Cutera, Candela, Lutronic, EndyMed, Eclipse Aesthetics, Aesthetics Biomedical, DermapenWorld, Jeisys Medical, Dr. Pen Group
Valuation Currency USD Billion, constant 2025 exchange rates

FAQs

How should a buyer evaluate total cost of ownership when comparing Microneedling Market platforms?
Model three years of cartridge consumption, not the sticker price. Consumables often exceed the capital cost by year two, so a cheaper platform with proprietary high-priced tips frequently costs more overall .
What contractual terms matter most when negotiating with device vendors?
Lock cartridge pricing with a capped annual escalator, and secure loaner coverage during service downtime. Vendors rarely volunteer either, but both are commonly granted on multi-unit orders .
Are counterfeit cartridges a real risk in the Microneedling Market?
Yes, particularly in markets with weak import enforcement. Unauthenticated tips risk sterility failure and void most warranties, which is why RFID-tagged cartridges are becoming standard on premium platforms [11].
How does microneedling compare commercially with fractional laser for a new clinic?
Needling platforms carry roughly one-third the capital cost and shorter operator training curves. Laser delivers faster results on some indications but limits the treatable phototype range [7].
What integration challenges arise when adding needling to an existing Microneedling Market service line?
Scheduling is the main friction — combination protocols with biologics extend chair time to 90 minutes. Practices that fail to reprice packages accordingly see margin per hour decline .
Which emerging use case deserves the closest watch?
Transdermal drug and vaccine delivery via microneedle arrays. Pharmaceutical partnerships would open a licensing revenue stream entirely separate from aesthetic device sales [14].
Do practitioner licensing reforms help or hurt vendors?
Both, briefly. Accreditation requirements slow near-term clinic openings but raise average selling prices and reduce adverse-event headlines that suppress consumer demand [16].    
Author
Author Author Profile Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.
Co-Author Co-Author Profile Nidhi Mandole LinkedIn Senior Research Analyst
She is an extremely curious individual currently working in Healthcare and Medical Devices Domain. Nidhi is comfortably versed in data centric research backed by healthcare educational background. She leverages extensive data mining and analytics tools such as Primary and Secondary Research, Statistical Analysis, Machine Learning, Data Modelling. Her key role also involves Technical Sales Support, Client Interaction and Project management within the Healthcare team. Lastly, she showcases extensive affinity towards learning new skills and remain fascinated in implementing them.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed medical journals, clinical publications, and authoritative healthcare organizations. Key sources included:

Regulatory & Government Authorities:

US Food & Drug Administration (FDA) – 510(k) clearances, PMA approvals, device safety alerts, and regulatory pathways for microneedling devices

European Medicines Agency (EMA) – CE marking certifications, Medical Device Regulation (MDR) compliance data

Health Canada – Medical device licenses and safety advisories for microneedling technologies

Australian Therapeutic Goods Administration (TGA) – ARTG listings and regulatory standards

Japan Ministry of Health, Labour and Welfare (MHLW) – Pharmaceuticals and Medical Devices Agency (PMDA) approvals

China National Medical Products Administration (NMPA) – Medical device registrations and import licenses

UK Medicines and Healthcare products Regulatory Agency (MHRA) – Post-market surveillance and device safety data

Clinical & Professional Organizations:

American Academy of Dermatology (AAD) – Clinical guidelines and procedural statistics

American Society for Dermatologic Surgery (ASDS) – Aesthetic procedure surveys and safety protocols

American Society of Plastic Surgeons (ASPS) – National Plastic Surgery Statistics reports

International Society of Aesthetic Plastic Surgery (ISAPS) – Global aesthetic procedure data

British Association of Dermatologists (BAD) – UK-specific treatment guidelines and market data

European Academy of Dermatology and Venereology (EADV) – European clinical practice standards

Healthcare Research Databases:

National Institutes of Health (NIH) – Clinical trial registries (ClinicalTrials.gov) and research funding data

National Center for Biotechnology Information (NCBI/PubMed) – Peer-reviewed studies on microneedling efficacy, safety, and comparative analysis

Cochrane Library – Systematic reviews on percutaneous collagen induction therapies

World Health Organization (WHO) – Global health observatory data on skin disease prevalence and aesthetic medicine trends

Centers for Disease Control and Prevention (CDC) – National Center for Health Statistics (NCHS) data on dermatological conditions

EU Eurostat Health Database – Healthcare expenditure and aesthetic procedure trends across EU member states

Industry & Trade Associations:

Medical Aesthetic Manufacturers Association (MAMA)

International Association for Physicians in Aesthetic Medicine (IAPAM)

American Med Spa Association (AmSpa) – Industry benchmarking and regulatory compliance data

These sources were utilized to collect procedure statistics, regulatory approval data, clinical safety studies, demographic trends, competitive landscape analysis, and technological advancements in radiofrequency (RF) microneedling, traditional microneedling, and combination therapies across dermatology clinics, hospitals, medical spas, and home-use segments.


Primary Research

In the primary research process, supply-side and demand-side stakeholders were interviewed to obtain qualitative and quantitative insights.

Supply-side sources included CEOs, VPs of Product Development, regulatory affairs heads, R&D directors, and commercial directors from microneedling device manufacturers, aesthetic technology companies, and OEM suppliers.

Board-certified dermatologists, plastic surgeons, aesthetic physicians, medical spa medical directors, clinic owners, and procurement leads from dermatology clinics, hospitals, medical spas, and aesthetic centers composed demand-side sources. The primary research validated market segmentation across product types (RF microneedling devices, traditional microneedling devices, derma rollers), confirmed product pipeline timelines, assessed technological innovations (fractional RF, insulated needles, robotics integration), and gathered insights on clinical adoption patterns, pricing strategies, reimbursement dynamics, and post-pandemic recovery trends in elective aesthetic procedures.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (30%), Others (38%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through revenue mapping, procedure volume analysis, and device shipment tracking. The methodology included:

Identification of 40+ key manufacturers across North America, Europe, Asia-Pacific, and Latin America, including leaders in RF microneedling (e.g., Cutera, Cynosure, EndyMed), traditional microneedling systems, and consumable needle cartridges

Product mapping across radiofrequency microneedling devices, traditional motorized microneedling pens, manual derma rollers, and associated consumables (disposable needle tips, serums)

Analysis of reported and modeled annual revenues specific to microneedling device portfolios and service revenues

Coverage of manufacturers representing 65-70% of global market share in 2024

Extrapolation using bottom-up (procedure volume × ASP by country/region, segmented by professional vs. home-use) and top-down (manufacturer revenue validation, dermatology clinic revenue analysis) approaches to derive segment-specific valuations

Adjustment factors for COVID-19 recovery trajectory, supply chain normalization, and elective procedure demand elasticity in key markets

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















