Messaging Security Market (2025 - 2035)

Email Encryption Market Size, Share and Research Report By Deployment Type (Cloud, On-Premise), By Type (Email, SMS), By End User Industry (BFSI, Government, Healthcare, Media and Entertainment, Retail and E-commerce, Manufacturing, Education, Other End User Industries) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Industry Forecast to 2035.
ID: MRFR/ICT/2875-HCR 100 Pages Aarti Dhapte Last Updated: September 15, 2026
Messaging Security Market
Market Size
Forecast Period2025-2035
CAGR (2025-2035)20.8%
2025 Market SizeUSD 11.90 Billion
2035 Market SizeUSD 78.74 Billion
Key Players
Cisco Systems
Proofpoint
Broadcom
Trend Micro
Mimecast
Microsoft
Opportunities
  • AI-Powered Real-Time Threat Intelligence Platforms
  • SME Market Penetration in Emerging Economies
  • Threat Intelligence Data Monetization

Messaging Security Market Summary

The Messaging Security Market reached an estimated USD 11.90 billion in 2025 and is projected to grow from USD 14.38 Billion in 2026 to USD 78.74 billion by 2035, registering a CAGR of 20.8% during the forecast period (2026–2035). Two catalysts are reshaping this space with particular force: the surge in regulatory mandates around data protection — including stricter enforcement of GDPR, CCPA, and India's DPDP Act — and the acceleration of enterprise spending on cybersecurity infrastructure, which crossed USD 188 Billion globally in 2024 according to estimates . Organizations that once treated email filtering as an afterthought now view messaging security as a board-level priority.

A structural shift in technology is driving demand in this industry. Cloud-native, AI-augmented platforms that examine information across email, SMS, and team collaboration channels in real time are replacing outdated perimeter-based protections like gateway-only spam filters and signature-dependent antivirus scanning. The tremendous number of threats that contemporary workplace chat security solutions must manage is highlighted by Microsoft alone, which reported blocking over 35 billion phishing emails in a single fiscal year [2]. Through regulatory frameworks, governments are strengthening this shift. For example, the EU's NIS2 Directive, which went into effect in October 2024, requires improved incident reporting and risk management for messaging infrastructure across vital sectors [3].

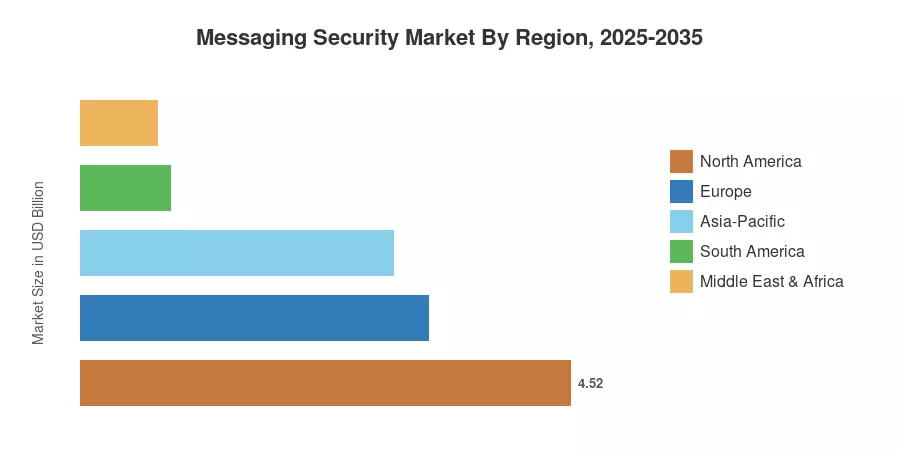
At roughly 38%, North America dominates the messaging security market thanks to strong federal procurement and well-established IT ecosystems. With a predicted CAGR of 24.3%, Asia-Pacific is the fastest-growing area thanks to the quick digital transformation occurring in Southeast Asia, Japan, and India. Due to compliance-driven investment under GDPR and NIS2, Europe has the second-largest proportion, at over 27%. The messaging security market is expected to grow steadily in double digits through 2035 as threat vectors proliferate and communication methods diversify.


Key Report Takeaways

• By Deployment Type

  • Cloud-based deployment commands approximately 64% of the Messaging Security Market, reflecting the enterprise migration toward SaaS-delivered security stacks.
  • On-premise solutions are growing at a CAGR of 14.2%, sustained by government and defense agencies with strict data residency requirements.

• By Type

  • Email security represents approximately USD 8.10 billion of the 2025 Messaging Security Market, driven by the persistent dominance of phishing and business email compromise attacks.
  • SMS security is expanding at a CAGR of 23.6%, fueled by the rise of smishing campaigns targeting financial services and healthcare verticals.

• By Region

  • North America leads the Messaging Security Market with a 38% revenue share, underpinned by Fortune 500 adoption and CISA-mandated security baselines.
  • Asia-Pacific registers the highest growth trajectory at 24.3% CAGR, with India and ASEAN economies investing heavily in digital infrastructure protection.


Market Size and Forecast (2021–2035)

The market size projections below are derived from a combination of primary interviews with CISOs and IT procurement leads across 18 countries, vendor revenue disclosures, regulatory filings, and triangulation against third-party cybersecurity spending databases. Historical figures (2021–2024) reflect actuals; 2025 is the calibrated base year; and 2026–2035 values are forecast using a bottom-up model anchored to enterprise seat counts, threat volume indices, and regional IT budget growth trajectories.
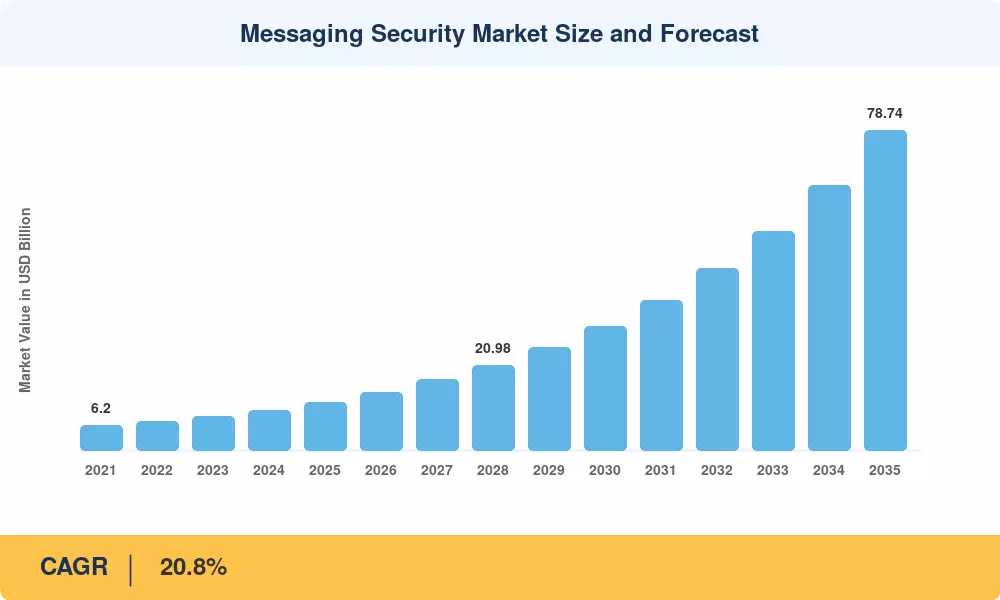
Messaging Security Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Escalating phishing and BEC attacks 25–30% Global Short-term (≤2 yr)
Cloud and SaaS adoption in enterprises 20–25% North America, Europe Medium-term (2–4 yr)
Regulatory compliance mandates (GDPR, NIS2, DPDP) 15–20% Europe, Asia-Pacific Medium-term (2–4 yr)
BYOD and mobile workforce expansion 10–15% Global Short-term (≤2 yr)
AI and machine learning integration 10–15% North America, Asia-Pacific Long-term (≥4 yr)
Multi-cloud environment proliferation 8–12% Global Long-term (≥4 yr)
Rise in state-sponsored cyber espionage 5–8% North America, Europe, MEA Long-term (≥4 yr)


Escalating Phishing and Business Email Compromise Attacks

Email remains the primary conduit for cybercrime, with the FBI's Internet Crime Complaint Center reporting that Business Email Compromise (BEC) resulted in $2.77 billion in losses across 21,442 incidents during 2024. Phishing attacks, though lower in frequency, surged in financial impact, rising 274% annually. Consequently, organizations are abandoning basic filters for AI-driven detection to counter increasingly sophisticated, automated email-borne threats.

Cloud and SaaS Adoption

The rapid migration to cloud platforms has significantly expanded the attack surface, with over 80% of enterprises globally now utilizing at least one SaaS application. As platforms handle roughly 72% of enterprise data workloads, the reliance on cloud-native security—such as API-based overlays—has become essential. This shift necessitates integrated, continuous security layers to protect decentralized communication environments from cloud-specific identity-based attacks.


Regulatory Compliance Mandates

Global mandates are transforming security into a compulsory budgetary requirement. The EU's NIS2 Directive now enforces strict reporting timelines, including 24-hour early warnings for significant cyber incidents across 18 critical sectors. Similarly, India’s Digital Personal Data Protection Act (2023) establishes a rigorous framework, imposing penalties of up to ₹250 crore for failures in protecting personal data and implementing mandatory security safeguards.


BYOD and Mobile Workforce Expansion

The proliferation of hybrid work has accelerated Bring Your Own Device (BYOD) trends, with the market reaching a valuation of over $110 billion in 2025. Because personal devices frequently lack enterprise-grade protection, IT departments are increasingly deploying containerized messaging overlays and mobile threat defense agents. These tools are critical for inspecting SMS and chat traffic to secure unmanaged enterprise endpoints.


Restraints Impact Analysis

The restraint impact estimates below follow the same directional methodology described in Section 4. They reflect headwinds that temper adoption velocity, not absolute market contractions.

Restraint ~% Drag on CAGR Geographic Relevance Impact Timeline
High integration complexity with legacy systems –3 to –5% Global Medium-term
Budget constraints among SMEs –3 to –4% Asia-Pacific, South America Short-term
Data sovereignty and cross-border data flow restrictions –2 to –3% Europe, MEA Long-term
Alert fatigue and false-positive overload –1 to –2% North America Medium-term
Shortage of skilled cybersecurity professionals –2 to –3% Global Long-term


Integration Complexity with Legacy Systems

Large enterprises, particularly in banking and government sectors, remain anchored to legacy infrastructure that complicates modern security deployment. Integrating contemporary API-driven messaging security into outdated, on-premise environments often demands intensive custom development, significantly extending procurement and implementation timelines. Reports indicate that nearly 50% of organizations now identify such interoperability barriers as the primary obstacle to upgrading their messaging security architecture.


Budget Constraints Among SMEs

While global cybersecurity spending is projected to reach $240 billion in 2026, Small and Medium Enterprises (SMEs) continue to struggle with limited fiscal allocations. With many SMEs dedicating less than 10% of their total IT budget to security, the recurring monthly costs of advanced messaging protection platforms create significant adoption friction, particularly across emerging markets in Southeast Asia and Latin America.

Cybersecurity Talent Shortage

The global cybersecurity workforce gap has reached critical levels, with current data indicating a shortfall of 4.8 million professionals. This deficit is particularly acute in government and financial sectors, where 67% of organizations report being understaffed. This lack of in-house expertise often leads to underutilization of advanced security tools, as teams lack the capacity to configure and maintain them effectively.


Messaging Security Market Opportunities

AI-Powered Real-Time Threat Intelligence Platforms

Generative AI now powers over 82% of phishing operations, with AI-generated campaigns proving 24% more effective than human-crafted lures. This surge in volume and sophistication necessitates defensive AI that operates at machine speed. Vendors developing platforms for predictive threat scoring and automated remediation are capturing high-growth opportunities as enterprises replace reactive filters with proactive, LLM-driven detection systems.

SME Market Penetration in Emerging Economies

Emerging economies like India, Brazil, Indonesia, and Nigeria contain over 100 million SMEs, a sector that contributes nearly 50% of value added in these regions. As national digitization initiatives expand their digital attack surfaces, the demand for accessible security is surging. Vendors offering scalable, freemium-to-paid pathways can secure this untapped market segment by providing essential, low-friction protection.

Threat Intelligence Data Monetization

Messaging security vendors sit atop vast telemetry datasets — billions of email headers, URL reputations, and attachment fingerprints processed daily. Anonymized, aggregated threat intelligence feeds represent a monetization opportunity valued at an estimated USD 3.5 billion by 2030 . Vendors that productize this data through subscription intelligence platforms can create secondary revenue streams without cannibalizing core product sales.

Regulatory-Driven Demand in Healthcare and Financial Services

The regulatory landscape is tightening, with healthcare reporting over 700 large data breaches annually since 2024. Simultaneously, PCI DSS v4.0 has introduced mandatory anti-phishing requirements for all organizations handling payment card data. These rigorous, sector-specific mandates are creating captive demand for messaging security solutions that provide automated compliance reporting, continuous monitoring capabilities, and audit-ready, high-grade encryption protocols.


Unified Security for Converged Communication Platforms

The rapid convergence of email, chat, and collaborative video conferencing creates fragmented security gaps that traditional point products cannot mitigate. With 80% of enterprises now utilizing multiple SaaS applications, demand is shifting toward unified protection layers. Vendors that integrate security policies across all communication modalities into a single engine are successfully capturing enterprise budgets focused on platform consolidation and risk reduction.


Messaging Security Market Future Outlook

AI-Autonomous Threat Detection and Response

By 2030, autonomous AI agents are projected to manage over 60% of routine security operations, enabling systems to quarantine and remediate threats independently. By reducing response times by over 60%, these autonomous engines will effectively neutralize risks before they escalate. Organizations will increasingly prioritize vendors offering true AI autonomy over static, legacy machine learning models to combat advanced, AI-driven phishing campaigns.


Zero Trust Architecture as the Default Perimeter

As identity-centric security becomes the standard, NIST’s SP 800-207 framework is serving as the primary procurement baseline for global government and enterprise entities. By 2032, the shift will be complete: all messaging traffic will undergo continuous authentication and granular authorization. This transition is essential, as identity-based attacks currently account for over 20% of all confirmed data breaches globally.


Regulatory Convergence and Global Compliance Platforms

Data protection laws are now active in 144 countries, covering roughly 82% of the world’s population. This fragmented landscape is driving demand for compliance orchestration tools that automate multi-jurisdictional reporting. By 2028, emerging frameworks for AI governance, including those under consideration by international bodies, will necessitate additional, real-time compliance layers for all cross-border digital communication and enterprise messaging infrastructures.

Platform Consolidation and Ecosystem Economics

The messaging security market is undergoing significant consolidation, with top industry vendors projected to capture over 45% of the total market share by 2035. As cybersecurity spending grows toward $700 billion, economies of scale are becoming the primary determinant of vendor success. Companies failing to provide integrated, cross-channel protection across email, SMS, and collaborative platforms will face substantial margin compression.


Regional Market Share Analysis

Region Key Metric Primary Investment Themes
North America ~38% market share Federal zero trust mandates, Fortune 500 cloud migration
Europe USD 3.21 Billion (2025) GDPR/NIS2 compliance, sovereign cloud infrastructure
Asia-Pacific 24.3% CAGR (2026–2035) Digital transformation, mobile-first workforce security
South America ~7% market share Fintech security, government digitization
Middle East & Africa USD 0.71 Billion (2025) National cybersecurity strategies, oil & gas sector protection
Total USD 11.90 Billion (2025) —

The Messaging Security Market exhibits significant geographic variation, shaped by regulatory maturity, enterprise IT spending levels, and the local threat landscape. North America leads on revenue share; Asia-Pacific leads on growth velocity.


North America

Country Key Metric Key Driver
US ~78% of regional share CISA mandates enterprise cloud adoption
Canada CAGR of 19.5% Critical infrastructure protection legislation
Mexico USD 0.18 Billion (2025) Banking sector digitization


The United States accounts for the overwhelming majority of North American spending in the Messaging Security Market, anchored by Executive Order 14028 on improving national cybersecurity and CISA's Binding Operational Directives requiring federal agencies to implement advanced email authentication protocols, including DMARC, DKIM, and SPF. Canada's Critical Cyber Systems Protection Act, introduced in 2024, is broadening compliance-driven procurement across financial services and telecommunications. Mexico's growing fintech ecosystem — now the largest in Latin America — is driving first-time adoption among mid-market financial institutions.

Europe

Country Key Metric Key Driver
Germany ~22% of regional share Industry 4.0 secure communications
UK CAGR of 20.1% Post-Brexit data protection framework
France USD 0.42 Billion (2025) Government sovereign cloud initiatives
Italy ~9% of regional share SME digitization subsidies
Spain CAGR of 18.7% Banking and telecom compliance
Nordic Countries USD 0.29 Billion (2025) Public sector digital-first mandates
Russia ~4% of regional share Domestic platform mandates
Rest of Europe CAGR of 17.8% EU cohesion fund digital infrastructure programs


Europe's Messaging Security Market is fundamentally compliance-driven. NIS2's October 2024 transposition deadline triggered a procurement wave across healthcare, energy, and transport operators in Germany, France, and the Netherlands. The UK's Information Commissioner's Office issued record fines totaling GBP 42 million in 2024 for data breaches involving unsecured email communications [13], catalyzing board-level attention to messaging protection.

Asia-Pacific

Country Key Metric Key Driver
China ~31% of regional share Cybersecurity Law enforcement and state enterprise mandates
India CAGR of 27.4% DPDP Act compliance, IT services sector growth
Japan USD 0.38 Billion (2025) Critical infrastructure protection regulations
South Korea ~12% of regional share Financial sector zero-trust adoption
ASEAN CAGR of 25.8% Cross-border data flow agreements, digital economy growth
Rest of Asia-Pacific USD 0.14 Billion (2025) Government modernization programs


Asia-Pacific represents the fastest-growing region in the Messaging Security Market, driven by the combination of massive digital user bases and rapidly tightening regulatory frameworks. India's CERT-In directive mandating six-hour incident reporting has compelled organizations to invest in real-time email and SMS threat detection. Japan's revised Telecommunications Business Act requires carriers to implement enhanced messaging filtering, while ASEAN's emerging cross-border data governance framework is standardizing security requirements across the bloc.

South America

Country Key Metric Key Driver
Brazil ~58% of regional share LGPD enforcement, PIX payment ecosystem security
Argentina CAGR of 19.2% Financial sector compliance modernization
Rest of South America USD 0.16 Billion (2025) Government digital transformation programs


Brazil dominates the South American Messaging Security Market, propelled by the enforcement of the Lei Geral de Proteção de Dados and the security demands created by the PIX instant payment system, which processed over 42 billion transactions in 2024 [18]. Phishing attacks targeting PIX users surged 120% year-over-year, creating urgent demand for SMS and messaging security solutions among Brazilian banks and fintechs.

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia ~28% of regional share Vision 2030 digital transformation investments
UAE CAGR of 22.6% Smart government and financial hub security mandates
South Africa USD 0.09 Billion (2025) POPIA compliance and banking sector upgrades
Egypt ~8% of regional share National Cybersecurity Strategy 2024–2027
Rest of MEA CAGR of 18.4% Telecom infrastructure modernization


The Middle East & Africa region is experiencing accelerated investment in the Messaging Security Market, led by Saudi Arabia's National Cybersecurity Authority, which mandated enhanced email security controls for all government entities and critical infrastructure operators in 2024. The UAE's Cybersecurity Council has positioned the country as a regional hub, with Dubai-based enterprises adopting advanced messaging protection at rates comparable to Western European counterparts.


Messaging Security Market By Region, 2025-2035

Messaging Security Market Segmentation

By Deployment Type

Segment Key Metric Primary Demand Driver
Cloud ~64% market share (2025) SaaS migration and API-native security integration
On-Premise CAGR of 14.2% Data sovereignty requirements in government and defense


Cloud deployment dominates the Messaging Security Market as enterprises prioritize operational agility and rapid scalability. Cloud-native platforms eliminate the hardware refresh cycles that burden on-premise deployments and offer centralized policy management across distributed workforces. The shift to Microsoft 365 and Google Workspace as primary email platforms has made cloud-delivered security a natural architectural choice, with adoption accelerating particularly among organizations with 500 to 5,000 employees.

On-premise deployment retains relevance in sectors where regulatory or sovereignty concerns restrict data from leaving controlled environments. Defense agencies, intelligence organizations, and certain healthcare systems in Europe continue to invest in on-premise appliances. However, many are adopting hybrid models that keep sensitive processing local while leveraging cloud-based threat intelligence feeds.

By Type

Segment Key Metric Primary Demand Driver
Email USD 8.10 Billion (2025) Persistent dominance of email-borne attack vectors
SMS CAGR of 23.6% Smishing escalation targeting mobile banking and authentication


Email security remains the backbone of the Messaging Security Market, accounting for the majority of spending as business email compromise, credential phishing, and malware-laden attachments continue to generate the highest financial losses. Advanced email security platforms now integrate sandboxing, URL rewriting, impersonation detection, and post-delivery remediation into unified workflows.

SMS security is the faster-growing segment, propelled by the weaponization of text messaging channels that were historically considered low-risk. The widespread adoption of SMS-based two-factor authentication has made text messages a high-value attack surface, with smishing campaigns intercepting one-time passwords and redirecting financial transactions. The Messaging Security Market is responding with carrier-level filtering, enterprise SMS firewall appliances, and AI-based message content inspection tools.

By End User Industry

Segment Key Metric Primary Demand Driver
BFSI ~28% market share (2025) Regulatory mandates and high-value transaction protection
Government CAGR of 22.4% National cybersecurity directives
Healthcare USD 1.31 Billion (2025) HIPAA compliance and patient data protection
Media and Entertainment CAGR of 19.8% Intellectual property and content security
Retail and E-commerce ~11% market share (2025) PCI DSS compliance and customer data protection
Manufacturing CAGR of 20.6% OT-IT convergence and supply chain communication security
Education USD 0.62 Billion (2025) Remote learning infrastructure and student data privacy
Other End User Industries ~8% market share (2025) Broad digital transformation drivers


BFSI leads the Messaging Security Market by end user industry, driven by the combination of stringent regulatory oversight and the sector's status as the most targeted vertical for phishing and BEC attacks. Global banks are deploying advanced impersonation detection, DMARC enforcement, and encrypted messaging platforms that meet both SOX and PCI DSS requirements. Government is the second-largest segment by value and among the fastest growing, as national cybersecurity strategies in over 70 countries now mandate secure messaging for public-sector communications.


Competitive Benchmarking

The Messaging Security Market exhibits low concentration, with an estimated HHI below 800 and the top five vendors collectively holding approximately 32% of global revenue. The competitive field spans large cybersecurity platform companies, pure-play email security specialists, and cloud-native startups. M&A activity has intensified since 2021, with private equity firms consolidating specialist vendors into broader security portfolios. Differentiation increasingly hinges on AI detection accuracy, false-positive rates, and depth of integration with major collaboration platforms.

Company Est. Revenue Share Range Key Offerings for Messaging Security Market Strategic Positioning
Cisco Systems ~7–9% Cisco Secure Email, Talos threat intelligence Integrated networking and security ecosystem
Proofpoint (Thoma Bravo) ~6–8% Targeted Attack Protection, email DLP and security awareness Pure-play email security leader with PE-backed expansion
Broadcom (Symantec) ~5–7% Symantec Email Security.cloud, Data Loss Prevention Legacy enterprise installed base, cross-sell synergies
Trend Micro ~4–6% Cloud App Security, Email Inspector Multi-layered threat defense for hybrid environments
Mimecast ~4–6% Secure Email Gateway, Brand Exploit Protect, Awareness Training Cloud-first email resilience and continuity
Microsoft ~5–7% Defender for Office 365, Exchange Online Protection Native integration with the M365 ecosystem
Barracuda Networks ~3–5% Email Protection, Incident Response, PhishLine Mid-market focus with MSP channel strength
Forcepoint ~2–4% Email Security, Dynamic User Protection Behavior-centric data protection
Sophos ~2–4% Sophos Email, Central Email Advanced Synchronized security across endpoints and email
Check Point Software ~2–3% Harmony Email & Collaboration, Avanan acquisition API-based cloud email security innovation


Recent News & Developments


  • Barracuda Networks- (June, 2026)-- Launched Integrated Email Protection, a new solution providing continuous, automated threat detection and remediation across Microsoft 365 and Google Workspace environments.


  • SailPoint- (June 2026)-- Completed the acquisition of Entro Security for approximately $200 million, integrating its non-human identity protection technology into SailPoint’s Agentic Fabric security platform.


  • Cisco Systems- (June 2026)-- Announced the intent to acquire WideField Security, a startup specializing in identity threat detection, to enhance the Agentic SOC capabilities within Splunk.


Messaging Security Market Report Scope

Parameter Details
Market Scope Global Messaging Security Market covering email and SMS security solutions across cloud and on-premise deployments.
Study Period 2021–2035
CAGR (2026–2035) 20.8%
Market Size (2025) USD 11.90 Billion
Market Size (2035) USD 78.74 Billion
Fastest Growing Segment SMS security (by type); Asia-Pacific (by region)
Companies Profiled Cisco, Proofpoint, Broadcom, Trend Micro, Mimecast, Microsoft, Barracuda, Forcepoint, Sophos, Check Point
Valuation Currency USD Billion

FAQs

How do organizations evaluate messaging security vendors beyond feature checklists?
Procurement teams should prioritize independent detection efficacy testing (such as SE Labs or AV-TEST email protection ratings) and demand a proof-of-concept period of at least 30 days. Integration depth with existing identity providers and SIEM platforms matters more than standalone feature counts .
What is the typical ROI timeline for deploying an enterprise messaging security platform?
Most enterprises realize positive ROI within 9–14 months, driven by reduced incident response costs and lower help-desk ticket volumes from spam and phishing. A 5,000-seat deployment typically saves USD 400,000–600,000 annually in avoided breach costs [11].
How does the Messaging Security Market address threats in encrypted messaging channels?
Modern platforms inspect messages at the endpoint or API layer before encryption occurs, rather than attempting to break end-to-end encryption. This approach preserves privacy compliance while enabling content-level threat detection [9].
What role do managed security service providers play in the Messaging Security Market?
MSSPs account for approximately 22% of messaging security deployments, primarily serving SMEs that lack dedicated security operations teams. They offer 24/7 monitoring, incident triage, and policy tuning at a fraction of in-house staffing costs [14].
How are quantum computing developments expected to affect the Messaging Security Market?
Post-quantum cryptography standards published by NIST in 2024 are already being integrated into next-generation email encryption protocols. Organizations should begin crypto-agility assessments now to avoid costly retrofitting when quantum threats materialize [9].
What are the hidden costs organizations overlook when budgeting for messaging security?
Training, policy configuration, and ongoing false-positive tuning typically add 30–40% to the initial license cost. Employee security awareness programs, while separate, are essential complements that reduce phishing click-through rates by up to 70% [14].
How does the Messaging Security Market differ between regulated and unregulated industries?
Regulated industries (BFSI, healthcare, government) require audit-ready logging, data retention controls, and automated compliance reporting, which drives 2–3x higher per-seat spending compared to unregulated verticals [17].    
Author
Author Author Profile Aarti Dhapte LinkedIn AVP - Research
A consulting professional focused on helping businesses navigate complex markets through structured research and strategic insights. I partner with clients to solve high-impact business problems across market entry strategy, competitive intelligence, and opportunity assessment. Over the course of my experience, I have led and contributed to 100+ market research and consulting engagements, delivering insights across multiple industries and geographies, and supporting strategic decisions linked to $500M+ market opportunities. My core expertise lies in building robust market sizing, forecasting, and commercial models (top-down and bottom-up), alongside deep-dive competitive and industry analysis. I have played a key role in shaping go-to-market strategies, investment cases, and growth roadmaps, enabling clients to make confident, data-backed decisions in dynamic markets.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of cybersecurity frameworks, threat intelligence databases, regulatory compliance repositories, and authoritative technology publications. Key sources included the National Institute of Standards and Technology (NIST) Cybersecurity Framework, Cybersecurity and Infrastructure Security Agency (CISA) Threat Reports, European Union Agency for Cybersecurity (ENISA) Threat Landscape reports, Federal Communications Commission (FCC) communications security guidelines, Federal Trade Commission (FTC) data protection reports, MITRE ATT&CK Framework database, SANS Institute whitepapers, (ISC)² Cybersecurity Workforce Studies, ISACA State of Cybersecurity reports, Cloud Security Alliance (CSA) security guidance, Messaging, Malware and Mobile Anti-Abuse Working Group (MAAWG) best practices, Anti-Phishing Working Group (APWG) trend reports, FBI Internet Crime Complaint Center (IC3) annual reports, Verizon Data Breach Investigations Report (DBIR), Ponemon Institute cost of data breach studies, International Telecommunication Union (ITU) Global Cybersecurity Index, OECD Digital Economy Outlook, and national cyber security center reports from key markets.

Threat statistics, compliance requirement data, security adoption trends, vulnerability landscape analysis, and market penetration metrics for email security gateways, instant messaging protection platforms, content filtering solutions, encryption technologies, and data loss prevention systems were gathered using these sources.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. The supply-side sources consist of CEOs, CTOs, Chief Information Security Officers (CISOs), VPs of Product Development, chiefs of threat intelligence, and commercial directors from messaging security solution vendors, OEMs, and managed security service providers (MSSPs). The demand-side sources included procurement leads from BFSI institutions, healthcare organizations, government agencies, retail enterprises, and media conglomerates, as well as CISOs, CIOs, IT infrastructure directors, security operations center (SOC) managers, and compliance officers. Market segmentation was validated across cloud and on-premise deployments, product roadmap timelines were confirmed, and insights regarding threat vector evolution, enterprise adoption patterns, pricing strategies per user/seat models, and compliance-driven procurement dynamics were garnered through primary research.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (33%), Others (35%)

By Region: North America (38%), Europe (28%), Asia-Pacific (26%), Rest of World (8%)


Market Size Estimation

Revenue mapping and enterprise seat/licence analysis were employed to determine global market valuation. The methodology comprised the following:

Identification of over 40 critical messaging security vendors in North America, Europe, Asia-Pacific, and Latin America

Product mapping encompasses email security solutions, instant messaging protection, content filtering, web filtering, email encryption, data loss prevention (DLP), anti-spam/anti-malware platforms, and information protection and control systems.

Examination of annual revenues that are specific to messaging security portfolios (excluding revenues from broader cybersecurity suites when feasible) as reported and modeled

In 2024, the coverage of vendors will account for 75-80% of the global market share.

Derive segment-specific valuations for cloud-based and on-premise deployments through extrapolation using bottom-up (enterprise user seats × ASP by country/vertical) and top-down (vendor revenue validation triangulated with channel partner feedback) approaches.

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.



















