Medical Footwear Market (2026 - 2035)

Medical Footwear Market Research Report: Size, Share, Trend Analysis By Product Type (Orthopedic Shoes, Diabetic Shoes, Post-Surgery Footwear, Compression Stockings), By End Users (Hospitals, Clinics, Home Care, Rehabilitation Centers), By Material (Leather, Synthetic, Rubber, Textile), By Distribution Channel (Online, Retail, Pharmacies) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth Outlook & Industry Forecast 2025 To 2035
ID: MRFR/MED/41648-HCR 200 Pages Rahul Gotadki, Kinjoll Dey Last Updated: September 11, 2026
Medical Footwear Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.85%
2025 Market SizeUSD 12.03 Billion
2035 Market SizeUSD 23.21 Billion
Key Players
DJO Global
Aetrex Worldwide
Orthofeet
Ottobock SE
Össur hf
Apex Foot Health
Opportunities
  • AI-Powered Prescription and Fitting Platforms
  • Emerging Market Expansion via Public Health Programs
  • Subscription and Data Monetization Models

Medical Footwear Market Summary

The Global Medical Footwear Market size was valued at USD 12.03 Billion in 2025, and the market is projected to grow from USD 12.78 Billion in 2026 to USD 23.21 Billion by 2035, registering a CAGR of 6.85% during the forecast period 2026–2035. Two structural forces anchor this trajectory: the International Diabetes Federation's 2024 projection that global diabetes prevalence will surpass 783 million adults by 2045 [1], and the U.S. Centers for Medicare & Medicaid Services' expanded Therapeutic Shoe Bill coverage that now reimburses up to USD 472 per beneficiary annually for qualifying medical footwear [2]. These policy and epidemiological tailwinds are pulling the medical footwear market well beyond its historical growth corridor.

The technology landscape is shifting decisively. Traditional mass-produced orthotic shoe manufacturing is giving way to additive-manufacturing workflows — 3D-printed midsoles and lattice-structure insoles that conform precisely to individual foot morphologies. Stratasys and HP report that medical-grade 3D printing adoption in the podiatric segment grew 34% year-over-year in 2024 [3]. Simultaneously, embedded sensor insoles from companies like Sensoria Health and Moticon now relay real-time plantar-pressure data to clinicians, turning passive footwear into active monitoring devices.

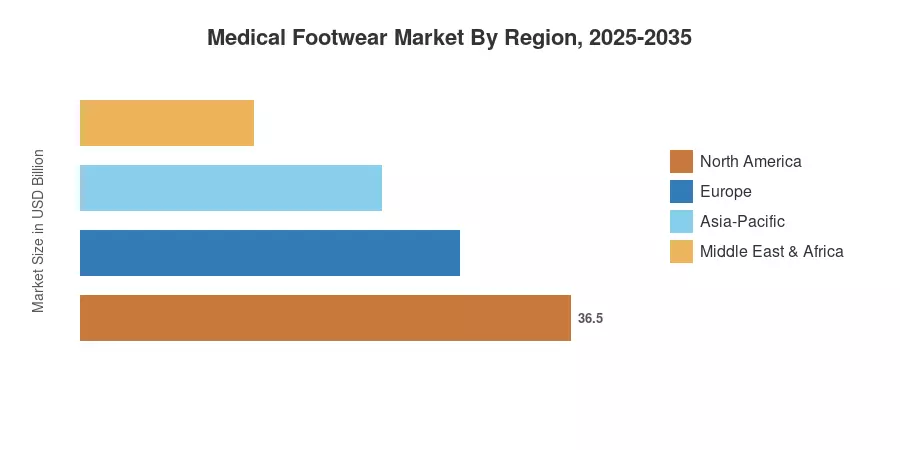
North America commands roughly 30.4% of the medical footwear market, driven by insurance reimbursement and a mature podiatric care infrastructure. Asia-Pacific is the fastest-growing region at a projected 9.35% CAGR, fueled by urbanization, expanding e-commerce channels, and rising diabetes diagnosis rates in India and China. Europe holds the second-largest share at approximately 27.1%, supported by national health service procurement programs across Germany, France, and the UK. The decade ahead will reward manufacturers who combine digital customization with clinical validation.


Key Report Takeaways

• By Product Category

  • Medical shoes and boots captured 46.8% of revenue share in the medical footwear market in 2025, reflecting entrenched prescriber loyalty and broad insurance formulary inclusion.
  • Insoles and inserts are on track to expand at a 10.1% CAGR through 2035, driven by consumer comfort-seeking behavior and clinical rehabilitation footwear adoption.

• By Medical Condition

  • Diabetes accounted for 63.0% of the medical footwear market in 2025, underpinned by Medicare Part B reimbursement and comparable programs in the EU.
  • Plantar fasciitis treatments are projected to advance at a 7.85% CAGR, as workplace wellness programs increasingly subsidize preventive footwear.

• By Distribution Channel

  • Specialty stores and clinics held 55.9% share of the medical footwear market, though their dominance is eroding as telehealth-to-doorstep models gain traction.
  • Online platforms are poised to grow at a 10.9% CAGR, making them the fastest-expanding distribution channel through 2035.

• By Region

  • North America led the medical footwear market at 30.4% share, with the U.S. contributing the vast majority of regional revenue.
  • Asia-Pacific's 9.35% CAGR through 2035 positions it to close the gap with Europe by the early 2030s.


Market Size and Forecast (2021–2035)

Market Research Future employs a triangulated estimation methodology that cross-references bottom-up revenue modeling from company filings with top-down macroeconomic indicators, including healthcare expenditure growth, diabetes prevalence trends, and insurance reimbursement data across 42 countries.
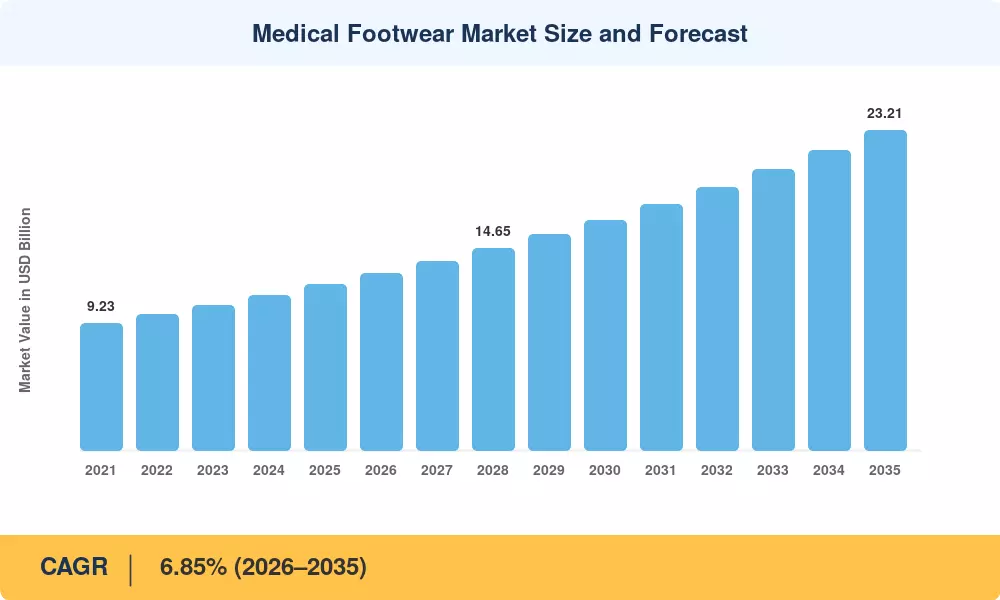
Medical Footwear Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Rising global diabetes prevalence ~22% Global Long-term (≥4 yr)
Insurance & reimbursement expansion ~18% North America, Europe Short-term (≤2 yr)
Additive manufacturing scale-up ~16% North America, Asia-Pacific Medium-term (2–4 yr)
E-commerce & DTC channel growth ~14% Global Short-term (≤2 yr)
Aging population demographics ~12% Europe, Japan Long-term (≥4 yr)
Smart-sensor insole integration ~10% North America, Europe Medium-term (2–4 yr)
Regulatory pathway simplification ~8% Global Medium-term (2–4 yr)


Rising Global Diabetes Prevalence

The IDF Diabetes Atlas (10th edition) estimates that 537 million adults were living with diabetes in 2021 and projects this figure to reach 783 million by 2045 [1]. Each new diagnosis represents a potential lifetime consumer of protective footwear—the American Podiatric Medical Association estimates that 15% of diabetic patients may develop a foot ulcer in their lifetime, and therapeutic shoes reduce ulcer recurrence by up to 60% [18]. This epidemiological fact makes the market for medical footwear inherently immune to cyclical downturns in consumer discretionary spending.


Insurance and Reimbursement Expansion

Coverage for one pair of depth shoes and three pairs of inserts annually for qualified diabetic patients is available under Medicare’s Therapeutic Shoe Bill (Section 1861(s)(12) of the Social Security Act) [2]. In Germany, the GKV statutory health insurance now reimburses prescribed orthopedic shoes up to EUR 400, while in France, the Assurance Maladie extended podiatric coverage in January 2024 [11]. These programs lower out-of-pocket expenses by 60-80% and directly boost the potential market for medical footwear.


Additive Manufacturing Scale-Up

Since 2021, HP’s Multi Jet Fusion and Carbon’s Digital Light Synthesis platforms have reduced the cost per unit of producing insoles by around 40% [3]. Podiatry clinics in the U.S. and Germany can now offer bespoke insoles made from 3D scans of feet in the clinic, the same day, reducing delivery time from 3 weeks to less than 4 hours. This change in manufacturing is particularly revolutionary for the medical footwear sector in Asia-Pacific, where the low labor costs are already conducive to large volumes of production.


E-Commerce and Direct-to-Consumer Channel Growth

Online platforms captured an estimated 10.9% CAGR trajectory through 2035, accelerated by telemedicine consultations that generate digital prescriptions directly linkable to e-commerce fulfillment [6]. Dr. Comfort and Orthofeet both reported 28%+ year-over-year online sales growth in 2024.


Restraints Impact Analysis

Restraint impact percentages represent directional drag estimates on market growth potential. They do not subtract linearly from the headline CAGR but indicate the relative severity of each headwind based on qualitative-quantitative sensitivity analysis.

Restraint ~% Drag on CAGR Geographic Relevance Impact Timeline
High out-of-pocket costs in uninsured markets ~–20% Asia-Pacific, South America Long-term (≥4 yr)
Lack of clinical awareness among GPs ~–18% Global (excl. North America) Medium-term (2–4 yr)
Fragmented regulatory standards ~–16% Asia-Pacific, MEA Medium-term (2–4 yr)
Counterfeit and substandard products ~–14% South America, Africa Long-term (≥4 yr)
Limited reimbursement for preventive footwear ~–12% Europe (select countries) Short-term (≤2 yr)


High Out-of-Pocket Costs in Uninsured Markets

In India, where government health insurance (Ayushman Bharat) covers hospitalization but not outpatient medical equipment, diabetes patients pay 100% of footwear expenditures out of pocket – INR 5,000-12,000 (USD 60-145) on average every pair [9]. This pricing barrier is stifling uptake in rural areas where 65% of India’s diabetic population lives. Similarly, the medical footwear market in Southeast Asia is structurally limited, with insurance penetration for podiatric devices below 8% in the ASEAN member states.


Lack of Clinical Awareness Among General Practitioners

Without clinical referral pathways, demand for the medical footwear market remains latent. Training gaps at the primary-care level represent a systemic bottleneck that advertising and consumer education alone cannot resolve.

Fragmented Regulatory Standards

The categorization of medical footwear is highly variable between countries, with the FDA classifying the majority of goods as Class I exempt devices, the EU’s MDR 2017/745 classifying them as Class I with self-certification, and several APAC markets requiring full pre-market approval [7]. To enter the global medical footwear industry, manufacturers must develop parallel quality management systems to meet regulatory demands, which increases compliance costs by 15–25%.


Medical Footwear Market Opportunities

AI-Powered Prescription and Fitting Platforms

Machine-learning algorithms trained on gait analysis datasets can now recommend insole geometry and shoe modifications with 92% concordance to podiatrist recommendations [14]. Companies embedding AI into the medical footwear market value chain — from diagnosis through fulfillment — will capture margin from both clinical and retail channels.

Emerging Market Expansion via Public Health Programs

China's Healthy China 2030 blueprint prioritizes diabetic complication prevention. These government-driven programs create bulk procurement opportunities for manufacturers positioned in the medical footwear market across Asia-Pacific.

Subscription and Data Monetization Models

Smart insoles generate continuous plantar-pressure and gait data that hold value for insurers, pharmaceutical companies running neuropathy drug trials, and physical therapy networks. Licensing anonymized datasets could represent a USD 200–400 million ancillary revenue stream for the medical footwear market by 2032 [8].

Bio-Based and Sustainable Materials

Consumer demand for eco-friendly medical products is rising — a 2024 survey found that 41% of healthcare purchasers consider sustainability credentials when selecting medical devices [15]. Bio-based antimicrobial foams and recycled-polymer outsoles offer manufacturers a differentiation lever in the increasingly competitive medical footwear market.

Post-Surgical and Rehabilitation Footwear Niche

The global volume of orthopedic surgeries exceeded 22 million procedures in 2024 [22]. Each post-operative patient requires protective footwear for 4–12 weeks, creating a recurring demand cycle that remains underpenetrated by specialized medical footwear market players.


Medical Footwear Market Future Outlook

Digital Prescription Ecosystems

By 2030, an estimated 40% of medical footwear prescriptions in North America and Europe will originate from digital platforms combining telehealth consultations, AI-driven foot scans via smartphone cameras, and direct e-commerce fulfillment [14]. This shift will compress the medical footwear market supply chain from five intermediaries to two, redistributing margin toward manufacturers and platforms that own the patient relationship.

Additive Manufacturing at Population Scale

The cost of 3D-printed medical insoles has dropped from USD 300 per pair in 2020 to approximately USD 85 in 2025, and is projected to reach USD 40 by 2030 [3]. At that price point, custom-fit insoles become economically competitive with off-the-shelf alternatives, potentially doubling the addressable medical footwear market for personalized products. HP and Carbon are already licensing production technology to regional fabrication labs across 18 countries.

Sustainability and Circular Economy Integration

The medical devices sector faces increasing ESG scrutiny. Forward-looking players in the medical footwear market are investing in bio-based polyurethane foams and take-back recycling programs — Aetrex launched a closed-loop insole recycling pilot in 2024 that recovered 72% of material weight.

Emerging Market Infrastructure Build-Out

The World Bank estimates that healthcare spending in low- and middle-income countries will grow at 7.2% annually through 2035, roughly double the rate in high-income nations [24]. For the medical footwear market, this spending growth translates into new hospital procurement budgets, expanded insurance formularies, and a rising middle class willing to pay out of pocket for preventive health products. India, Brazil, and Nigeria represent the three largest untapped opportunity pools.


Regional Market Share Analysis

Region Key Metric Primary Investment Themes
North America 30.4% share (2025) Reimbursement-led demand, DTC e-commerce, smart insoles
Europe 27.1% share (2025) MDR compliance, aging demographics, and public procurement
Asia-Pacific 9.35% CAGR (2026–2035) Diabetes screening programs, urbanization, and manufacturing hubs
South America USD 0.96 Billion (2025) Public health expansion, counterfeit regulation
Middle East & Africa USD 0.72 Billion (2025) Gulf healthcare investment, import-dependent supply chains
Total USD 12.03 Billion (2025)

The medical footwear market displays pronounced regional asymmetry shaped by insurance infrastructure, diabetes prevalence, and distribution maturity.


North America

Country Key Metric Key Driver
United States 82.3% of regional share Medicare Therapeutic Shoe Bill [2]
Canada 10.8% of regional share Provincial health coverage programs
Mexico 6.9% of regional share IMSS diabetic foot care initiatives


The United States drives the overwhelming majority of North American revenue for the medical footwear market, with approximately 37 million diagnosed diabetic patients eligible for reimbursed therapeutic footwear under Medicare Part B [2]. Canada's publicly funded provincial programs in Ontario and British Columbia provide partial reimbursement, while Mexico's IMSS system is piloting footwear subsidies in 12 states.

Europe

Country Key Metric Key Driver
Germany 7.12% CAGR GKV reimbursement and orthopedic tradition
United Kingdom 5.85% CAGR NHS diabetic foot screening pathway
France USD 0.58 Billion (2025) Assurance Maladie expansion [11]
Italy USD 0.42 Billion (2025) SSN procurement frameworks
Spain 5.6% CAGR Aging population dynamics
Nordic Countries USD 0.39 Billion (2025) Universal healthcare access
Russia 4.8% CAGR Import substitution policy
Rest of Europe USD 0.51 Billion (2025) Varied regulatory maturity


Germany remains Europe's anchor market for the medical footwear market, supported by a deeply embedded orthopedic shoe-making tradition and GKV reimbursement of up to EUR 400 per pair. The UK's NHS Long Term Plan mandates annual foot checks for all diabetic patients, generating consistent referral volume into medical footwear channels [11].

Asia-Pacific

Country Key Metric Key Driver
China 31.5% of regional share Healthy China 2030 diabetic care mandate
India 11.2% CAGR Ayushman Bharat expansion and 77M diabetic population [10]
Japan USD 0.48 Billion (2025) Super-aging demographics
South Korea 8.9% CAGR NHIS coverage expansion
ASEAN USD 0.34 Billion (2025) E-commerce-led access
Rest of Asia-Pacific 7.8% CAGR Urbanization and rising disposable income


Asia-Pacific presents the strongest growth trajectory for the medical footwear market through 2035. China's centralized procurement system and India's expanding diabetes screening infrastructure together serve a combined diabetic population exceeding 210 million — a patient base larger than North America's and Europe's combined [9] [10].

South America

Country Key Metric Key Driver
Brazil 62.4% of regional share SUS public health system footwear programs
Argentina 18.7% of regional share Private insurance sector growth
Rest of South America 18.9% of regional share NGO-driven diabetic care outreach


Brazil's Unified Health System (SUS) introduced diabetic foot care as a priority line item in 2023, creating a formal procurement channel for the medical footwear market. Argentina's growing private health insurance market — covering approximately 18 million citizens — is beginning to include podiatric device benefits [13].

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 28.3% of regional share Vision 2030 healthcare investment
UAE 7.5% CAGR Medical tourism and premium retail
South Africa 21.6% of the regional share Private hospital network expansion
Egypt 6.8% CAGR Universal Health Insurance Law rollout
Rest of MEA 31.2% of regional share Import dependency, fragmented distribution


The Gulf states are investing heavily in healthcare infrastructure — Saudi Arabia's Vision 2030 allocated USD 65 billion to health sector development [23]. For the medical footwear market, this translates into new hospital-based dispensaries and retail pharmacy channels that did not exist five years ago. Sub-Saharan Africa remains constrained by supply chain fragmentation and limited reimbursement.


Medical Footwear Market By Region, 2025-2035

Medical Footwear Market Segmentation

By Product Category

Segment Key Metric Primary Demand Driver
Medical Shoes & Boots 46.8% share (2025) Insurance-reimbursed prescriptions
Insoles & Inserts 10.1% CAGR (2026–2035) 3D-printing cost reduction
Orthopedic Braces & Supports USD 1.68 Billion (2025) Post-surgical rehabilitation demand


Medical shoes and boots dominate the medical footwear market because they represent the primary insured product category — Medicare, GKV, and NHS programs all center reimbursement around complete footwear rather than components. Prescriber behavior reinforces this position: podiatrists default to full-shoe prescriptions for diabetic patients because clinical evidence most strongly supports complete offloading solutions [18].

Insoles and inserts, meanwhile, are the fastest-growing product segment in the medical footwear market. The convergence of smartphone-based foot scanning, additive manufacturing, and direct-to-consumer shipping has created a low-friction purchase pathway that bypasses traditional clinical gatekeepers. Orthofeet and Aetrex both reported insole revenue growth exceeding 30% in 2024 [19].

By Medical Condition

Segment Key Metric Primary Demand Driver
Diabetes 63.0% share (2025) Reimbursement programs and ulcer prevention protocols
Arthritis & Osteoporosis USD 1.93 Billion (2025) Aging demographics in Europe and Japan
Plantar Fasciitis 7.85% CAGR (2026–2035) Workplace wellness and athletic crossover demand
Other Conditions USD 1.14 Billion (2025) Neuropathy, post-surgical recovery, pediatric deformities


Diabetes remains the structural backbone of the medical footwear market because the condition creates a recurring, clinically mandated need for protective footwear. Plantar fasciitis is the segment to watch — employer-sponsored wellness programs in the U.S. and Germany now cover preventive insoles, expanding the addressable population beyond clinical patients into the active-lifestyle consumer base.

By Age Group

Segment Key Metric Primary Demand Driver
Pediatric (under 18) USD 0.84 Billion (2025) Congenital and developmental conditions
Adult (18–60) 59.4% share (2025) Occupational and diabetes-related demand
Geriatric (over 60) 8.15% CAGR (2026–2035) Fall prevention and mobility support


Adults aged 18–60 account for the largest segment in the medical footwear market, driven by working-age diabetes prevalence and occupational health mandates. The geriatric segment's growth trajectory is steeper because global populations over 60 are expanding at 3.2% annually, and fall-prevention footwear is increasingly prescribed as a first-line intervention [17].

By Distribution Channel

Segment Key Metric Primary Demand Driver
Specialty Stores & Clinics 55.9% share (2025) Prescriber referral networks
Online Platforms 10.9% CAGR (2026–2035) Telemedicine integration and DTC models
Pharmacies & Retail USD 2.05 Billion (2025) Walk-in accessibility and brand awareness


Specialty stores and clinics still control the majority of distribution in the medical footwear market, but online platforms are eroding that dominance faster than most incumbents anticipated. The pandemic permanently shifted patient comfort with remote consultations, and medical footwear is well-suited to digital fulfillment because sizing can be captured via smartphone scanning technologies [6].


Competitive Benchmarking

The medical footwear market exhibits medium concentration, with the top five players holding an estimated 32–38% combined revenue share. The Herfindahl-Hirschman Index sits in the 800–1,200 range, indicating a moderately fragmented landscape where regional specialists coexist with global medical device conglomerates. Competition intensifies around reimbursement-eligible product lines and digital distribution capabilities.

Company Est. Revenue Share Range Key Offerings Strategic Positioning
DJO Global (Dr. Comfort) ~7–10% Diabetic shoes, therapeutic insoles, custom orthotics Vertically integrated; strong Medicare channel presence
Aetrex Worldwide ~5–8% Smart insoles with gait analytics, diabetic footwear Technology-forward; Albert 2-foot scanning platform
Orthofeet ~4–7% Orthopedic shoes, plantar fasciitis insoles DTC e-commerce leader; wide consumer appeal
Ottobock SE ~4–6% Post-operative shoes, rehabilitation footwear Global rehab brand; strong EU distribution
Össur hf ~3–6% Prosthetic-compatible footwear, bracing solutions Prosthetics expertise; Nordic heritage brand
Apex Foot Health ~3–5% Ambulator diabetic shoes, A-Wave insoles Legacy clinical brand; strong podiatrist relationships
Drew Shoe Corporation ~2–4% Depth shoes, extra-wide therapeutic footwear Niche sizing specialist; loyal prescriber base
Darco International ~2–4% Post-surgical shoes, wound care boots Acute-care focus; hospital procurement contracts
Podartis S.r.l. ~2–3% Custom diabetic footwear, modular insole systems Italian craftsmanship; strong Southern European presence
New Balance (Medical Line) ~2–3% Motion-control shoes, wellness walking footwear Consumer brand crossover; lifestyle positioning


Recent News & Developments


  • Aetrex Worldwide (January 2025): Expanded the retail integration of its Albert 2 Pro 3D foot-scanning systems, combining high-resolution pressure mapping with machine-learning algorithms to deliver instant, customized orthotic selections across international clinics.
  • Ottobock SE (November 2024): Revolutionized personalized lower-limb care by commercializing its iconiq 3D-printed silicone liner technology, utilizing precise 3D residual limb scans to improve patient comfort and limb stability during active rehabilitation cycles.
  • U.S. CMS (September 2024): Strengthened compliance audits for the Therapeutic Shoes for Persons with Diabetes benefit, enforcing strict documentation requirements for doctors prescribing depth shoes and multi-density custom inserts under Code Section 1861(s)(12).


  • EU Commission (April 2024): Monitored manufacturer compliance transitions under MDR 2017/745, confirming that standard non-sterile custom orthopedic footwear retains its Class I self-certification status while requiring strict technical documentation and material traceability.


Medical Footwear Market Report Scope

Parameter Detail
Market Scope Global medical footwear market, including shoes, boots, insoles, inserts, orthopedic braces, and post-surgical protective devices
Study Period 2021–2035
CAGR 6.85% (2026–2035)
Market Size (2025) USD 12.03 Billion
Market Size (2035) USD 23.21 Billion
Fastest Growing Segment Insoles & Inserts (10.1% CAGR); Online Platforms (10.9% CAGR)
Companies Profiled 10 (DJO Global, Aetrex, Orthofeet, Ottobock, Össur, Apex Foot Health, Drew Shoe, Darco, Podartis, New Balance)
Valuation Currency USD Billion
Forecast Methodology Triangulated estimation combining bottom-up company revenue analysis, top-down macroeconomic modeling, and proprietary diabetes prevalence forecasting

FAQs

How do reimbursement caps influence product design in the medical footwear market?
This creates a design corridor where innovation focuses on material efficiency rather than premium pricing [2].
What role do podiatrist referral networks play in brand loyalty within the medical footwear market?
Podiatrists prescribe from familiar formularies, and brands that invest in clinical education programs and sampling retain 70–80% of prescriber loyalty year over year. Breaking into established referral networks requires multi-year relationship building [18].
How does the medical footwear market address sizing variability across global populations?
Manufacturers increasingly deploy 3D foot-scanning kiosks that capture morphology data across populations, enabling parametric last design. This reduces returns by 35% compared to traditional sizing charts [8].
What cybersecurity risks accompany smart-insole adoption in the medical footwear market?
Connected insoles transmit health data via Bluetooth, creating HIPAA and GDPR compliance obligations. Manufacturers must encrypt data in transit and at rest, adding approximately 12–15% to per-unit electronics costs [8].
How do counterfeit products threaten the medical footwear market in emerging economies?
Unregulated imports — particularly in Southeast Asia and West Africa — carry no clinical validation and can cause pressure injuries. The WHO estimates that counterfeit medical devices represent 8% of market volume in low-income countries [21].
What is the typical procurement cycle for hospital-based medical footwear market purchases?
Hospital procurement follows 12–18 month tender cycles tied to annual budgets, requiring manufacturers to maintain pre-qualified vendor status and comply with group purchasing organization contract terms [22].
How will carbon border adjustment mechanisms affect the medical footwear market supply chain?
The EU's CBAM, operational from 2026, will increase landed costs for footwear manufactured in high-emission jurisdictions by an estimated 3–5%, pushing manufacturers toward nearshoring or verified low-carbon supply chains [15].    
Author
Author Author Profile Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.
Co-Author Co-Author Profile Kinjoll Dey LinkedIn Senior Research Analyst
He is an extremely curious individual currently working in Healthcare and Medical Devices Domain. Kinjoll is comfortably versed in data centric research backed by healthcare educational background. He leverages extensive data mining and analytics tools such as Primary and Secondary Research, Statistical Analysis, Machine Learning, Data Modelling. His key role also involves Technical Sales Support, Client Interaction and Project management within the Healthcare team. Lastly, he showcases extensive affinity towards learning new skills and remain fascinated in implementing them.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed medical journals, clinical publications, and authoritative health organizations. Key sources included the US Food & Drug Administration (FDA) Center for Devices and Radiological Health, European Medicines Agency (EMA) Medical Device Regulations, International Diabetes Federation (IDF.org), American Podiatric Medical Association (APMA.org), American Orthopaedic Foot & Ankle Society (AOFAS), Centers for Disease Control and Prevention (CDC) National Center for Health Statistics, National Institutes of Health (NIH) National Institute of Diabetes and Digestive and Kidney Diseases (NIDDK), National Center for Biotechnology Information (NCBI/PubMed), World Health Organization (WHO) Global Health Observatory, EU Eurostat Health Database, Occupational Safety and Health Administration (OSHA) workplace safety standards, American Diabetes Association (ADA) clinical guidelines, and national health ministry reports from key markets. These sources were used to collect prevalence statistics for diabetes and foot disorders, regulatory approval data for medical-grade footwear, clinical safety studies on orthopedic interventions, demographic trends in aging populations, reimbursement policies for therapeutic footwear, and competitive landscape analysis for orthopedic shoes, diabetic footwear, post-surgical footwear, and compression therapy products.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, VPs of Product Development, heads of regulatory affairs, supply chain directors, and commercial directors from contract manufacturers, orthotic device firms, and medical footwear manufacturers were examples of supply-side sources. Board-certified podiatrists, orthopedic surgeons, wound care experts, diabetes educators, hospital and health system medical supply procurement managers, retail pharmacy purchasers, rehabilitation center directors, and home healthcare coordinators were examples of demand-side suppliers. Primary research verified material innovation timelines (leather, synthetic, rubber, textile), validated market segmentation across product types (orthopedic shoes, diabetic shoes, post-surgery footwear, compression stockings), and gathered information on clinical adoption patterns, pricing strategies, distribution channel dynamics, and insurance reimbursement frameworks.

Primary Respondent Breakdown:

By Designation: C-level Executives (28%), Director Level (32%), Others (40%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through revenue mapping and unit volume analysis across the medical footwear value chain. The methodology included:

Identification of 50+ key manufacturers across North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa

Product mapping across orthopedic shoes, diabetic footwear, post-operative footwear, and compression stockings segments

Material segmentation analysis covering leather, synthetic polymers, rubber compounds, and advanced textile composites

Distribution channel assessment spanning e-commerce platforms, specialty retail, hospital supply chains, and pharmacy networks

Analysis of reported and modeled annual revenues specific to medical footwear portfolios

Coverage of manufacturers representing 72-78% of global market share in 2024

Extrapolation using bottom-up (procedure volume × ASP by country/region) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















