Marine Battery Market (2026 - 2035)

Marine Battery Market Size, Share, Industry Trend & Analysis Research Report: By Battery Type (Lithium Iron Phosphate, Nickel Manganese Cobalt, Advanced Lead-Acid, Nickel-Based and Other), By Vessel Type (Passenger Ferries and Ro-Pax, Offshore Support Vessels, Tugs and Harbour Craft, Naval and Defence, Recreational and Yachts, Cargo and Others), By Propulsion Architecture (Fully Electric, Plug-In Hybrid, Conventional Hybrid, Auxiliary and Hotel Load), By Nominal Capacity (Above 1,000 kWh, 100–1,000 kWh, Below 100 kWh), By Region (Europe, Asia-Pacific, North America, South America, Middle East & Africa) - Forecast to 2035.
ID: MRFR/AD/8052-HCR 128 Pages Abbas Raut, Sejal Akre Last Updated: August 27, 2026
Marine Battery Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)12.4%
2025 Market SizeUSD 1.42 Billion
2035 Market SizeUSD 4.57 Billion
Key Players
Corvus Energy
Leclanché SA
EST-Floattech
Echandia
Wärtsilä
Saft
Opportunities
  • Retrofit of the Existing Global Fleet
  • Inland Waterways in Emerging Economies
  • Energy-as-a-Service and Battery Leasing

Marine Battery Market Summary

The Marine Battery Market reached USD 1.42 billion in 2025 and opens the forecast window at USD 1.59 billion in 2026, climbing to USD 4.57 billion by 2035 at a 12.4% CAGR. Two catalysts explain most of that trajectory. The International Maritime Organization's Net-Zero Framework, approved at MEPC 83 in April 2025, put a price signal on well-to-wake emissions for ships above 5,000 gross tonnes [1]. Alongside it, FuelEU Maritime began enforcing a 2% greenhouse gas intensity cut on energy used by vessels calling at EU ports from January 2025, tightening to 6% in 2030 [2].

Diesel gensets and mechanical shaft lines are giving way to DC bus architectures with large stationary packs. Norway's NOx Fund has disbursed more than NOK 1.5 billion toward low-emission vessel projects since inception, and the European Commission's Alternative Fuels Infrastructure Regulation obliges TEN-T core ports to supply shore power to container and passenger ships by 2030 [3][4].

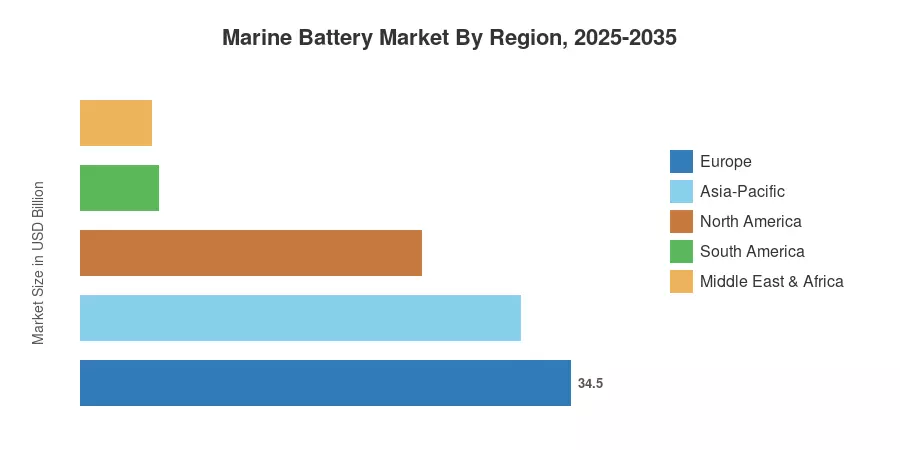
Europe holds roughly 34.5% of the Marine Battery Market on the strength of Norwegian and Dutch ferry fleets. Asia-Pacific grows fastest at a 14.2% CAGR, propelled by Chinese inland waterway electrification and Korean shipyard orderbooks. North America ranks second-largest, anchored by Washington State Ferries and Jones Act coastal newbuilds. The decade ahead belongs to whoever industrialises marine-grade cell supply first.


Key Report Takeaways

• By Technology

  • Lithium iron phosphate holds a 46.8% share of installed capacity within the Marine Battery Market, favoured for thermal stability under class rules
  • Nickel-manganese-cobalt packs command roughly USD 0.41 billion of 2025 revenue, where volumetric energy density governs vessel design
  • Advanced lead-acid and nickel chemistries retain a 19.4% share, largely in auxiliary and starting duty

• By Sector

  • Commercial passenger and ro-pax vessels contribute close to USD 0.55 billion in 2025, the single largest demand pool
  • Naval and defence platforms expand at an 11.1% CAGR through 2035 as submarine and unmanned surface programmes convert
  • Offshore support and workboats represent 17.6% of installed value in the Marine Battery Market

• By Region

  • Europe leads with a 34.5% share, concentrated in Norway, the Netherlands and Denmark
  • Asia-Pacific posts the fastest regional CAGR at 14.2%
  • North America accounts for approximately USD 0.34 billion of 2025 revenue


Market Size and Forecast (2021–2035)

Figures below blend vessel-level order tracking from classification society registers, shipyard delivery schedules, cell shipment data from tier-one suppliers, and disclosed contract values in public procurement portals. Historical years are reconciled against installed megawatt-hours certified by DNV, Lloyd's Register, and Bureau Veritas, then converted to revenue using audited average system pricing per kilowatt-hour.
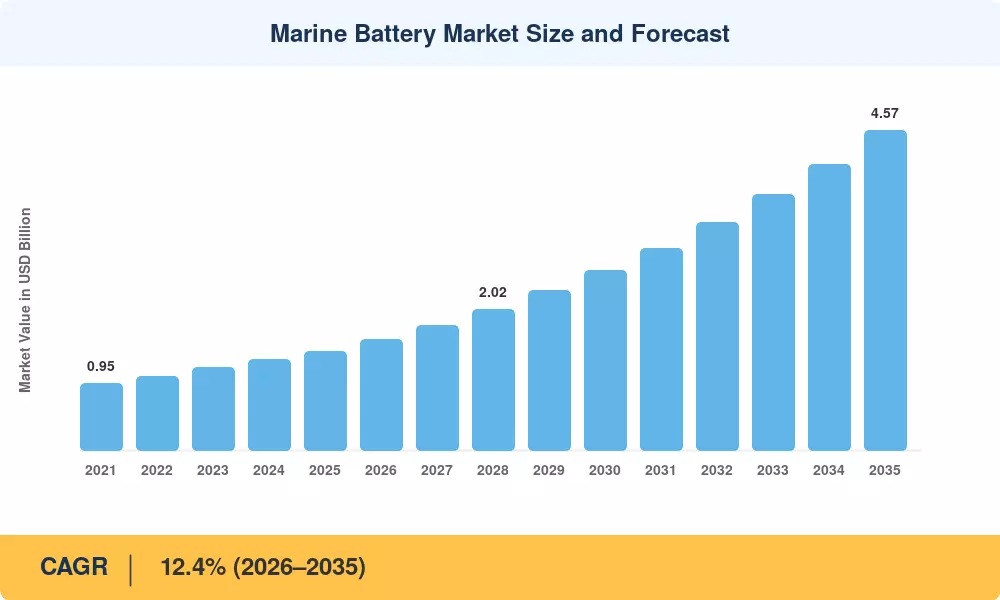
Marine Battery Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
IMO Net-Zero Framework carbon pricing 2.8 Global Medium-term (2–4 yr)
FuelEU Maritime and EU ETS compliance costs 2.4 Europe Short-term (≤2 yr)
Falling cell pack pricing 2.1 Global Long-term (≥4 yr)
Shore-power mandates at major ports 1.7 Europe, North America Medium-term (2–4 yr)
Inland waterway electrification programmes 1.6 Asia-Pacific Long-term (≥4 yr)
Naval hybridisation and quiet-running requirements 1.1 North America, Europe, Asia-Pacific Long-term (≥4 yr)
Port air-quality regulation in coastal cities 0.9 Global Short-term (≤2 yr)


Carbon Pricing Reaches the Waterline

Shipping spent decades outside carbon markets. That ended when the EU Emissions Trading System began covering maritime transport in January 2024, phasing in to a 100% surrender obligation for verified emissions by 2026 [2]. Operators running short-sea routes now model battery capex against a per-tonne allowance cost that has traded above EUR 65 for much of the past two years. For a ro-pax vessel burning 4,000 tonnes of marine gas oil annually, a hybrid conversion trimming 22% of fuel burn pays back within seven years on carbon savings alone.

Compliance Economics on European Short-Sea Routes

Regulatory intensity targets bite hardest where voyages are short, and port calls frequent. FuelEU Maritime's 2% reduction requirement for 2025 rises to 14.5% by 2035, and penalties are set at EUR 2,400 per tonne of VLSFO-equivalent energy in deficit [2]. Ferry operators in Denmark, Norway and Greece have responded by ordering plug-in hybrid tonnage rather than paying pooled penalties.

Cell Economics and the Cost Curve

Pack-level pricing for marine-certified systems fell roughly 38% between 2021 and 2025, tracking but lagging the automotive curve because of class certification, marinisation and lower volumes [6]. Certification overhead still adds a meaningful premium per kilowatt-hour over land-based storage, yet the gap narrows each year as suppliers standardise modules across vessel classes.

Public Funding for Fleet Renewal

Norway's NOx Fund and the EU Innovation Fund together committed over EUR 900 million to maritime decarbonisation projects between 2021 and 2025, with battery-hybrid ferries among the largest recipient categories [3]. India's Harit Nauka guidelines, issued in 2024, target electric propulsion on all inland passenger vessels within a decade [7].


Restraints Impact Analysis

Restraint weightings represent estimated drag on growth momentum in the Marine Battery Market and are directional rather than additive. Each reflects observed project delays, cancelled tenders, and documented cost overruns across the 2021–2025 historical window.

Restraint ~% Drag on CAGR Geographic Relevance Impact Timeline
High upfront capital cost versus diesel −2.3 Global Short-term (≤2 yr)
Shore charging infrastructure gaps −1.9 Asia-Pacific, South America Medium-term (2–4 yr)
Fire safety and class certification complexity −1.4 Global Medium-term (2–4 yr)
Critical mineral supply concentration −1.1 Global Long-term (≥4 yr)
Limited energy density for deep-sea voyages −0.8 Global Long-term (≥4 yr)


The Capital Cost Barrier

Retrofitting a mid-size ferry with a 2 MWh system, DC switchboard, and charging interface typically costs USD 2.5–4.0 million before yard time [8]. Small operators without balance-sheet depth or grant access simply defer. Charter structures compound the problem: the owner funds the equipment while the charterer banks the fuel savings, a split-incentive problem that has stalled numerous otherwise viable projects.

Charging Infrastructure Lags Vessel Orders

It is possible to build ships more quickly than electrify berths. The Alternative Fuels Infrastructure Regulation deadline of 2030 provides little room for grid delays in crowded port towns, and connecting a 3 MW fast-charging dock frequently necessitates substation renovations that utilities execute on multi-year cycles [4]. Southeast Asian and Latin American ports are subject to more severe restrictions due to the lack of medium-voltage quayside capacity.


Safety Certification and Insurance Friction

Thermal runaway propagation testing, gas detection, and ventilation design remain the longest-lead items in class approval. DNV's battery rules and the IMO interim guidelines require enclosure-level containment evidence that adds months to project schedules and drives underwriters to price marine electrification risk conservatively [14].


Marine Battery Market Opportunities

Retrofit of the Existing Global Fleet

Roughly 60,000 commercial vessels above 1,000 gross tonnes are in service today, and fewer than 1% carry meaningful energy storage [12]. Retrofit represents a far larger addressable base than newbuild, particularly for tugs, offshore support vessels and short-route ferries where duty cycles suit peak-shaving.

Inland Waterways in Emerging Economies

China's Yangtze corridor and India's National Waterways programme move enormous freight volumes over predictable routes with fixed charging points. Both governments have issued electrification targets for inland fleets, creating a demand pool that Western suppliers have barely addressed [7].

Energy-as-a-Service and Battery Leasing

Leasing the pack instead of buying it eliminates ownership friction. In order to turn capital expenditures into operating expenses and enable smaller operators, a number of providers now provide per-kilowatt-hour availability contracts that combine state-of-health monitoring, replacement, and end-of-life management [10].


Operational Data Monetisation

Every voyage generates cycle depth, temperature, and load-profile telemetry. Suppliers aggregating this data across fleets can price warranties more accurately, sell predictive maintenance subscriptions and feed anonymised benchmarks back to charterers as fuel-efficiency verification.

Second-Life and Recycling Streams

Marine packs retire at 70–80% remaining capacity, well suited to port-side stationary storage buffering fast-charge peaks. Closing that loop reduces grid upgrade costs and creates a secondary revenue line for suppliers [10].


Marine Battery Market Future Outlook

Autonomy and Energy Management Converge

Vessels that are autonomous and under remote supervision require steady, regulated power. By scheduling genset starts against anticipated load, optimization algorithms have previously reduced fuel consumption on hybrid tugs by 8–12%, and this reasoning readily extends to crewless platforms operating fixed routes [19]. Instead of being a precautionary afterthought, battery management systems become the operational brain.


The Electrification Supercycle Reaches Deep Water

Short-sea electrification is largely settled; the harder question is hybrid architecture for ocean-going tonnage. The IEA projects global battery manufacturing capacity exceeding 6 TWh by 2030, and marine applications will absorb a small but strategically important slice of that output for peak-shaving and harbour manoeuvring on large vessels [20].

Chemistry Diversification

Sodium-ion and semi-solid-state candidates target the marine duty cycle directly, trading energy density for cycle life and thermal tolerance. Class societies have begun drafting approval pathways, and first commercial installations are plausible before 2030 [11].

Verified Emissions Reporting Becomes Commercial Infrastructure

More and more charterers are requesting auditable emissions data rather than estimations. According to IRENA, participation in green shipping corridors is increasingly dependent on verifiable reporting systems, which makes onboard measurement a contractual benefit rather than a compliance expense [21].


Marine Battery Market Segmentation

By Battery Type

The Marine Battery Market divides most sharply along chemistry, where safety certification cost drives selection as much as performance.

Segment Share of 2025 Revenue (%) Primary Demand Driver
Lithium Iron Phosphate 46.8 Thermal stability under class rules
Nickel Manganese Cobalt 28.9 Volumetric density on space-constrained hulls
Advanced Lead-Acid 14.2 Auxiliary, starting and emergency duty
Nickel-Based and Other 10.1 Legacy naval and specialised applications
Total 100.0


Iron phosphate won the safety argument. Its flatter thermal runaway profile simplifies enclosure design and shortens approval timelines, which matters more to a shipyard than a 15% density penalty. Cobalt-bearing chemistries hold their position on high-speed craft and submarines where every cubic metre of hull volume carries a performance cost, and where operators accept tighter monitoring regimes in exchange.

By Vessel Type

Segment 2025 Value (USD Million) Primary Demand Driver
Passenger Ferries and Ro-Pax 552 Fixed routes and frequent charging windows
Offshore Support Vessels 250 Dynamic positioning peak-shaving
Tugs and Harbour Craft 213 Port air-quality regulation
Naval and Defence 199 Acoustic signature reduction
Recreational and Yachts 128 Silent anchorage and hotel loads
Cargo and Others 78 Inland waterway mandates


Ferries dominate for structural reasons: known route length, guaranteed berth time, and a public-sector owner able to absorb payback periods a private charterer would reject. Offshore support vessels follow a different economic logic entirely, where storage smooths dynamic positioning load spikes and lets operators shut down a generator that would otherwise idle at low efficiency for hours.

By Propulsion Architecture

Segment CAGR 2026–2035 (%) Primary Demand Driver
Fully Electric 14.6 Short-route zero-emission mandates
Plug-In Hybrid 13.2 Range flexibility with port-side charging
Conventional Hybrid 10.4 Fuel saving without shore infrastructure
Auxiliary and Hotel Load 9.1 Anchorage emissions and comfort


Fully electric vessels dominate near-term growth for regulatory reasons: strict short-route zero-emission mandates, predictable port schedules, and high-frequency operations that justify rapid shoreside charging infrastructure. Hybrid and auxiliary segments follow a different operational logic entirely, where plug-in configurations and battery-buffered hotel loads smooth out peak power demands, letting operators optimize engine loads and cut emissions even where charging infrastructure remains limited.


By Nominal Capacity

Segment Share of 2025 Installations (%) Primary Demand Driver
Above 1,000 kWh 51.3 Large ferry and offshore propulsion
100–1,000 kWh 33.4 Workboats, tugs, small ferries
Below 100 kWh 15.3 Recreational craft and auxiliary systems
Total 100.0


Large installations above 1,000 kWh dominate by capacity for heavy-duty reasons: multi-megawatt propulsion demands from large ferries and offshore vessels that require massive energy reserves for continuous operation. Smaller battery brackets follow a different deployment logic entirely, where modular sub-1,000 kWh systems provide the agility needed for workboats, tugs, and recreational craft, balancing spatial constraints with localized operational needs.


Regional Market Share Analysis

Region Share of 2025 Market (%) Primary Investment Themes
Europe 34.5 Ferry electrification, shore power, EU compliance
Asia-Pacific 31.0 Inland waterways, shipyard newbuilds, cell manufacturing
North America 24.0 State ferry fleets, tug hybridisation, naval programmes
South America 5.5 River transport, offshore support vessels
Middle East & Africa 5.0 Port craft, luxury and expedition yachts
Total 100.0

Regional performance in the Marine Battery Market tracks three variables: coastal regulation stringency, ferry route density, and shipyard capability. Europe leads on all three.


Europe

Country Share of Region (%) Key Driver
Norway 29.4 Zero-emission fjord requirements from 2026
Netherlands 16.1 Inland barge fleet conversion
Germany 13.8 Port air-quality rules and yard capacity
Denmark 11.2 Municipal ferry procurement
France 9.5 Mediterranean short-sea routes
Rest of Europe 20.0 EU Innovation Fund disbursements


Norway remains the reference market. Parliament's requirement that vessels entering the World Heritage fjords operate emission-free from 2026 forced operators to commit years in advance, and more than 80 battery-electric ferries now run domestic routes [3]. Dutch inland shipping follows a different logic — swappable container packs standardised across barge operators reduce charging dwell time on the Rhine corridor.

Asia-Pacific

Country CAGR 2026–2035 (%) Key Driver
China 15.8 Yangtze inland fleet mandates
South Korea 13.6 Shipyard integration and export builds
Japan 12.4 Coastal cargo and port craft renewal
India 14.9 Harit Nauka inland vessel programme
Rest of Asia-Pacific 11.7 Island ferry networks


China combines demand and supply advantage. Domestic cell makers supply marine-certified modules at costs Western integrators struggle to match, while Ministry of Transport rules restrict new diesel vessels on designated inland routes [7]. Korean yards, meanwhile, treat energy storage as a differentiator in export contracts for European owners.

North America

Country 2025 Value (USD Million) Key Driver
United States 268 State ferry replacement and naval hybridisation
Canada 58 BC Ferries and Great Lakes operations
Mexico 15 Port service craft


Washington State Ferries anchors United States demand through its hybrid-electric conversion and newbuild programme, backed by federal Ferry Service for Rural Communities funding [16]. Tug operators in California pursue hybridisation to meet CARB Commercial Harbor Craft amendments, which tighten in-use engine standards on a rolling schedule through 2032 [13].

South America

Country Share of Region (%) Key Driver
Brazil 54.0 Amazon River passenger transport
Chile 21.5 Aquaculture support vessels
Argentina 13.0 Paraná waterway logistics
Rest of South America 11.5 Port and harbour craft


Brazil's Amazon basin carries millions of passenger journeys annually on ageing diesel craft, and development-bank financing has begun underwriting pilot electric vessels on shorter tributary routes [17]. Chilean salmon farming operators adopt hybrid workboats to cut noise and diesel spill exposure in sensitive fjord environments.

Middle East & Africa

Country 2025 Value (USD Million) Key Driver
United Arab Emirates 24 Abu Dhabi and Dubai marine transport electrification
Saudi Arabia 19 NEOM and Red Sea tourism craft
South Africa 12 Port service and patrol vessels
Rest of MEA 16 Coastal tourism fleets


Gulf demand skews toward premium tourism and government craft rather than freight. Dubai's Roads and Transport Authority has committed to converting its abra and water-taxi fleet, while Red Sea Global specifies electric vessels across its resort transfer operations to protect reef environments [18].


Marine Battery Market By Region, 2025-2035

Competitive Benchmarking

Concentration sits in the moderately fragmented band, with an estimated HHI near 900 and the top five suppliers holding roughly 46–52% of global revenue in the Marine Battery Market. Specialist marine integrators dominate the certified systems layer while diversified industrial groups compete on drive-train bundling, and cell manufacturers increasingly bypass integrators for large fleet contracts.

Company Est. Revenue Share Range Key Offerings for Marine Battery Market Strategic Positioning
Corvus Energy ~13–16% Certified LFP and NMC systems, gas-venting enclosures Category leader in ferry and offshore
Leclanché SA ~8–11% Marine Rack System, high-cycle modules Europe-focused, chemistry-agnostic
EST-Floattech ~6–9% Octopus series modular packs Inland waterway specialist
Echandia ~5–7% LTO and LFP high-power systems Safety-first heavy-duty niche
Wärtsilä ~5–7% Hybrid propulsion packages, energy management Full drive-train integrator
Saft (TotalEnergies) ~4–6% Seagreen modules, naval systems Defence and industrial pedigree
Siemens Energy ~4–6% BlueDrive DC systems, shore-power interfaces Electrical architecture depth
Toshiba Corporation ~3–5% SCiB lithium-titanate cells Fast-charge and long-life focus
Furukawa Battery ~3–4% Lead-acid and hybrid marine cells Asia-Pacific auxiliary strength
Exide Technologies ~2–4% Starting, lighting and auxiliary batteries Aftermarket distribution reach


Recent News & Developments


  • European Union (January 2025): FuelEU Maritime entered application, requiring a 2% cut in energy GHG intensity for vessels calling at EU ports and creating immediate penalty exposure for diesel-only short-sea operators [2]
  • Corvus Energy (September 2024): Commissioned expanded automated production capacity in Bergen to shorten lead times for European ferry contracts amid a growing orderbook [22]
  • European Commission (2024): Alternative Fuels Infrastructure Regulation obligations confirmed for TEN-T core ports, mandating shore-power supply for container and passenger vessels by 2030 [4]
  • Government of India (January 2024): Ministry of Ports issued Harit Nauka green transition guidelines targeting electric propulsion across inland passenger vessels within a decade [7]


  • California Air Resources Board (2023–2025): Commercial Harbor Craft amendments phased in tighter in-use standards, accelerating tug and ferry hybridisation across Californian ports [13]
  • Wärtsilä (March 2025): Expanded its hybrid propulsion portfolio with an integrated energy management platform aimed at offshore support vessel retrofits [24]


Marine Battery Market Report Scope

Parameter Detail
Market Scope Global energy storage systems installed aboard commercial, naval, offshore and recreational vessels, including cells, modules, enclosures, control electronics and integration services
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 12.4% (2026–2035)
Market Size Checkpoints USD 1.42 Billion (2025); USD 1.59 Billion (2026); USD 4.57 Billion (2035)
Fastest Growing Segments Fully electric propulsion architecture; Asia-Pacific region; lithium iron phosphate chemistry
Companies Profiled Corvus Energy, Leclanché, EST-Floattech, Echandia, Wärtsilä, Saft, Siemens Energy, Toshiba, Furukawa Battery, Exide Technologies
Valuation Currency USD, constant 2025 prices

FAQs

How long does class approval typically take for a new vessel battery installation?
Approval in principle usually runs three to five months, with full class certification extending to nine months when enclosure-level propagation testing is required. Early engagement with the society shortens this materially [14].
What contractual risk should buyers watch in Marine Battery Market retrofit deals?
Yard availability, not equipment supply, drives most overruns. Insist on liquidated damages tied to dock days rather than delivery dates [8].
Do insurers price battery-electric vessels differently?
Underwriters commonly apply a premium loading for first-of-class installations, easing once the configuration has documented operating hours. Independent thermal runaway testing evidence reduces the loading fastest [14].
What warranty terms are standard in the Marine Battery Market?
Suppliers typically guarantee 70–80% state of health after a defined cycle count, usually five to ten years. Warranties are voided quickly if charging profiles exceed contracted C-rates [23].
Who owns end-of-life responsibility for retired marine packs?
Under EU battery regulation, producers carry extended responsibility for collection and recycling. Non-EU flag operators should negotiate takeback explicitly in the supply contract [10].
Which integration issue delays projects most often?
Grid connection at the berth. Utility interconnection studies for multi-megawatt fast charging routinely take longer than the vessel conversion itself [4].
Is the Marine Battery Market viable without shore charging infrastructure?
Conventional hybrid configurations deliver 8–15% fuel savings using onboard generation alone, requiring no shore connection. Full electrification, however, depends entirely on quayside power [19].    
Author
Author
Author Profile
Abbas Raut LinkedIn Research Analyst
Abbas Raut is a Senior Research Analyst with 5+ years of experience delivering data-driven insights and strategic recommendations across the Automotive and Aerospace & Defense sectors. He specializes in emerging technologies, industry value chains, and global market dynamics shaping the future of mobility and defense. In automotive, Abbas has led studies on EVs, charging stations, BMS, superchargers, and more, guiding stakeholders through electrification and regulatory shifts. In Aerospace & Defense, he has analyzed markets for military electronics, drones, radars, and electronic warfare solutions, supporting procurement and investment strategies. With expertise in market sizing, forecasting, benchmarking, and technology adoption, Abbas is known for transforming complex datasets into actionable insights that drive strategy, innovation, and growth.
Co-Author
Co-Author Profile
Sejal Akre LinkedIn Senior Research Analyst
She has over 5 years of rich experience, in market research and consulting providing valuable market insights to client. Hands on expertise in management consulting, and extensive knowledge in domain including ICT, Automotive & Transportation and Aerospace & Defense. She is skilled in Go-to market strategy, industry analysis, market sizing, in depth company profiling, competitive intelligence & benchmarking and value chain amongst others.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of maritime regulatory databases, classification society standards, peer-reviewed engineering journals, marine electrification publications, and authoritative maritime organizations. Key sources included the International Maritime Organization (IMO) for MARPOL Annex VI regulations and decarbonization frameworks, DNV (Det Norske Veritas) Battery Power classification standards and Maritime Battery Handbook, American Bureau of Shipping (ABS) Guide for Electrical Energy Storage Systems, Lloyd's Register (LR) Code for Battery-Powered Ships, and ClassNK Guidelines for Lithium-ion Battery Systems. Governmental and intergovernmental sources comprised the U.S. Maritime Administration (MARAD) Fleet Statistics, European Maritime Safety Agency (EMSA) Alternative Fuels Reports, International Energy Agency (IEA) Global Energy Transitions in Shipping, UNCTAD Review of Maritime Transport, International Council on Clean Transportation (ICCT) Maritime Program, U.S. Department of Energy (DOE) Vehicle Technologies Office Marine Applications, European Commission Green Deal Maritime Strategy, national maritime administrations (Norwegian Maritime Authority, Maritime and Port Authority of Singapore, UK Maritime and Coastguard Agency), International Electrotechnical Commission (IEC 62619, 62620 marine battery standards), and IEEE Power Electronics Society marine electrification publications. These sources were utilized to collect vessel fleet data, IMO 2030/2050 regulatory compliance timelines, battery system safety certifications, port electrification infrastructure statistics, shipbuilding order books, and technology readiness levels for zero-emission shipping.


Primary Research

During the primary research process, both supply-side and demand-side stakeholders were interviewed to gather both qualitative and quantitative information. Supply-side sources were CEOs, VPs of Marine Engineering, heads of Battery Integration divisions, regulatory compliance officers, and system architects from marine battery makers, pack integrators, and maritime propulsion system OEMs. Fleet technical managers, chief naval architects from shipbuilding yards, marine procurement directors from ferry operators and offshore vessel companies, port authority infrastructure heads, and naval program managers from defense procurement agencies were all demand-side sources. Primary research confirmed the rates at which battery chemistry is being used, the timelines for retrofitting vessels versus building new ones, and gathered information on how to deploy charging infrastructure, how long it takes for class society to approve a new design, and how the total cost of ownership changes for hybrid versus conventional propulsion.

Primary Respondent Breakdown:

By Designation: C-level Primaries (40%), Director Level (32%), Others (28%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through revenue mapping, battery capacity deployment (MWh), and vessel fleet analysis. The methodology included:

Identification of 50+ key manufacturers and system integrators across North America, Europe, Asia-Pacific, and Scandinavia

Product mapping across lithium-ion chemistries (LFP, NMC, LTO), advanced lead-acid, nickel-cadmium, and solid-state battery categories

Analysis of reported and modeled annual revenues specific to marine battery portfolios and maritime energy storage system integrations

Coverage of manufacturers and integrators representing 75-80% of global marine battery capacity deployed in 2024

Extrapolation using bottom-up (installed battery capacity × ASP by vessel type and region) and top-down (manufacturer revenue triangulation against shipbuilding order books) approaches to derive segment-specific valuations for hybrid ferries, offshore support vessels, electric cargo ships, and naval applications

Validation against global shipyard output statistics and maritime electrification CAPEX forecasts from classification society databases

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















