Laser Headlight Market (2026 - 2035)

Laser Headlight Market Research Report By Vehicle Type (Passenger Vehicles, Light Commercial Vehicles, Medium & Heavy Commercial Vehicles), By Technology Type (Intelligent Laser Headlights, Conventional Laser Headlights), By Sales Channel (OEM, Aftermarket), By Application (High Beam, Low Beam, Cornering Light, Daytime Running Light) - Forecast to 2035
ID: MRFR/AT/8898-CR 128 Pages Triveni Bhoyar, Swapnil Palwe Last Updated: October 07, 2026
Laser Headlight Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)26.85%
2025 Market SizeUSD 19.94 Billion
2035 Market SizeUSD 217.96 Billion
Key Players
Koito Manufacturing
Valeo
FORVIA HELLA
ams OSRAM
ZKW Group
Marelli
Opportunities
  • Emerging-Market Premiumization in India and ASEAN
  • Software-Defined Lighting and Feature Subscriptions
  • Commercial-Vehicle Retrofit Programs

Laser Headlight Market Summary

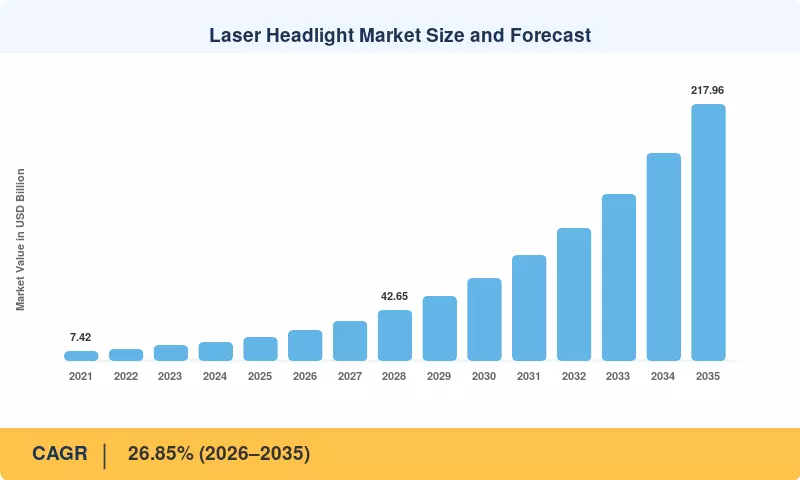
The Laser Headlight Market was valued at USD 19.94 Billion in 2025 and is forecast to reach USD 25.63 Billion in 2026, expanding to USD 217.96 Billion by 2035 at a CAGR of 26.85% over 2026–2035. Two regulatory catalysts anchor that trajectory. UNECE Regulation No. 149 permits higher-luminance adaptive beams across Europe and allied markets [2], while the U.S. National Highway Traffic Safety Administration's 2022 final rule allowed Adaptive Driving Beam (ADB) systems on American roads for the first time [1].

Lighting architecture is changing quickly. Halogen and first-generation xenon units are being retired, and conventional LED headlamp technology is increasingly paired with laser-excited phosphor modules that deliver long-range high beams from a far smaller emitter. Electric vehicles amplify the shift: global EV sales exceeded 17 million units in 2024 [3], and every watt saved on lighting extends driving range. Tier-1 suppliers now combine laser boosters with pixel-level LED control to balance performance, cost, and compliance.

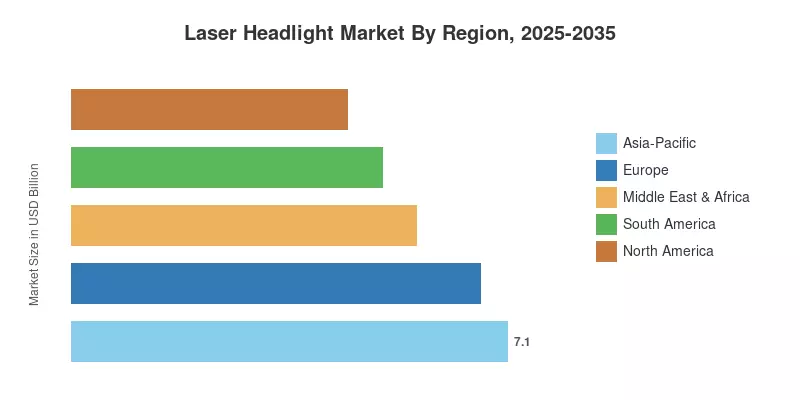
Asia-Pacific leads with a 35.6% share, supported by premium-vehicle output in China, Japan, and South Korea. Middle East & Africa is the fastest-growing region at a 28.2% CAGR, driven by high premium-car penetration in the Gulf states. Europe holds the second-largest position with a 33.4% share, underpinned by German OEMs that pioneered series laser lighting. Over the next decade, software control and sensor fusion will matter as much as raw lumen output.

Key Report Takeaways

• By Vehicle Type

  • Passenger Vehicles accounted for a 78.3% share of the Laser Headlight Market in 2025, reflecting early deployment on German and Japanese premium models.
  • Light Commercial Vehicles generated USD 2.59 billion in 2025 as van fleets tested hybrid laser-LED modules
  • Medium & Heavy Commercial Vehicles are projected to post a 27.0% CAGR, the fastest in this dimension.

• By Technology Type

  • Intelligent Laser Headlights are set to expand at a 27.1% CAGR as pixel-level beam control becomes standard on premium trims.
  • Conventional Laser Headlights held a 63.5% share in 2025 because early programs remain in production.

• By Sales Channel

  • OEM installations captured an 81.0% share of the Laser Headlight Market in 2025
  • Aftermarket demand is forecast to grow at a 27.1% CAGR, led by commercial-fleet retrofits.

• By Application

  • High Beam units led with a 44.4% share in 2025
  • Cornering Light modules are expected to register a 27.0% CAGR on demand for urban side visibility.

• By Region

  • Asia-Pacific held a 35.6% share in 2025
  • Middle East & Africa is forecast to grow at a 28.2% CAGR, the fastest of any region
  • North America generated USD 4.49 billion in 2025

Market Size and Forecast (2021–2035)

Market Research Future built the Laser Headlight Market baseline from bottom-up shipment modeling of laser-equipped vehicle trims, cross-checked against Tier-1 supplier disclosures, OICA production statistics [16], and China Association of Automobile Manufacturers data [17]. Forecast values combine regional vehicle-build schedules with technology-mix assumptions for conventional, hybrid, and intelligent architectures. Growth tapers after 2029 as the installed base matures and microLED competition intensifies.
Laser Headlight Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Impact percentages below are directional estimates of each driver's contribution to Laser Headlight Market growth. They overlap and interact, so they should not be added together to reproduce the headline CAGR.

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Stringent night-visibility and pedestrian-safety rules ~+5.8% Europe, Asia-Pacific Medium-term (2–4 yr)
U.S. ADB rulemaking and IIHS headlight ratings ~+3.9% North America Medium-term (2–4 yr)
EV energy-efficiency requirements ~+4.6% Global Long-term (≥4 yr)
ADAS and camera-sensor integration ~+4.2% Global Medium-term (2–4 yr)
Premium vehicle production growth in Asia ~+3.5% China, South Korea, India Short-term (≤2 yr)
Commercial fleet night-safety economics ~+2.8% North America, Europe Long-term (≥4 yr)


Stringent Night-Visibility and Pedestrian-Safety Rules

UNECE Regulation No. 149 consolidated legacy lamp rules into a single road-illumination standard, permitting higher-luminance adaptive beams as long as glare limits are met [2]. Euro NCAP protocols increasingly reward detection of pedestrians and cyclists at night, and pedestrians account for close to one-fifth of EU road deaths [6]. Automakers chasing five-star ratings therefore specify longer-reach high beams, and laser boosters extending visibility toward 600 meters give camera systems more time to classify hazards.

4.2 U.S. ADB Rulemaking and IIHS Headlight Ratings

NHTSA's 2022 amendment to FMVSS No. 108 ended a long gap with Europe by allowing glare-free adaptive beams [1]. Roughly half of U.S. traffic fatalities occur in darkness, even though only about a quarter of driving happens after sunset [4]. IIHS research found that vehicles with good-rated headlights have a 19% lower nighttime crash rate per mile than poor-rated ones [5], giving OEMs a clear safety case for premium lighting.

EV Energy-Efficiency Requirements

The IEA reports that electric cars exceeded 17 million sales in 2024, more than 20% of global new-car sales [3]. Every component competes for battery energy, and suppliers cite high-beam efficiency gains of up to 30% for laser modules versus comparable LED arrays. BloombergNEF expects continued EV share gains through 2030 [20], so lighting efficiency will stay on OEM specification sheets, especially for range-focused sedans with low-drag front ends.

ADAS and Camera-Sensor Integration

In order to conceal approaching cars while maintaining brilliant lighting throughout the remainder of the road, intelligent laser modules use inputs from front cameras. The test methods required to verify this behavior are defined by SAE J3069 [22] and FORVIA HELL. Tens of thousands of independently controlled pixels can feed driver-assistance functionalities, as demonstrated by A's high-definition lighting systems [8]. At highway speeds, a longer lighting range directly enhances camera object detection.


Premium Vehicle Production Growth in Asia

In 2024, China produced over 31 million cars, more than 12 million of which were new-energy vehicles [17]. Lighting signatures are now used by domestic premium companies as a visual differentiator, and flagship sedans and SUVs costing more than USD 40,000 include laser high beams. Even low laser take rates result in high unit numbers because Asia accounts for much over half of the world's car production, according to OICA figures [16].


Commercial Fleet Night-Safety Economics

Crashes involving large trucks kill more than 5,000 people a year in the United States [4]. Fleet operators running overnight routes face high liability and downtime costs from each incident. Long-range laser-assisted beams reduce driver fatigue and widen hazard-detection windows on unlit rural highways, offering a measurable payback that makes heavy trucks the fastest-growing vehicle category.

Restraints Impact Analysis

The negative impact estimates below are directional and partially overlapping. Each restraint dampens Laser Headlight Market expansion, but their values should not be summed against the driver table.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
High system cost ~−4.1% Global, mass-market segments Short-term (≤2 yr)
U.S. photometric ceilings under FMVSS No. 108 ~−3.2% North America Medium-term (2–4 yr)
Blue laser diode supply concentration ~−2.6% Global Short-term (≤2 yr)
Eye-safety certification and thermal limits ~−1.9% Global Medium-term (2–4 yr)
Substitution by microLED and LED matrix ~−3.6% Global Long-term (≥4 yr)


High System Cost

Historically, laser headlamp sets have cost more than $1,000 per car, which is several times more than the price of an LED unit. Active cooling, safety interlocks, and phosphor converters increase bill-of-materials costs that mass-market OEMs are unable to cover [10]. Laser illumination will continue to be focused on top-tier vehicles and halo trims until hybrid designs reduce component counts.


5.2 U.S. Photometric Ceilings Under FMVSS No. 108

American-spec laser systems have a significantly lesser reach than European models since U.S. regulations limit peak intensity and projection distance [1]. The value proposition is weakened for buyers who pay for laser alternatives since they gain less obvious benefits. In response, a number of manufacturers have removed laser trims from their U.S. inventory or replaced them with more affordable microLED arrays.


Blue Laser Diode Supply Concentration

High-power blue laser diodes come from a small group of specialist semiconductor producers, led by Japanese manufacturers [13]. A single fab disruption can delay vehicle launches by months, as 2024 shortages showed. OEMs now demand dual sourcing, but qualifying a second diode supplier typically requires 18–24 months of validation.

Eye-Safety Certification and Thermal Limits

Laser lamps must meet IEC 60825-1 laser-safety classification and include fail-safe interlocks that cut the diode if the phosphor is damaged [14]. Phosphor efficiency also drops at elevated temperatures, and enclosed housings regularly exceed 100°C. These constraints add engineering cycles and limit use in compact low-beam housings.

Substitution by microLED and LED Matrix

High-definition LED and microLED systems now offer pixel-level beam shaping at lower cost, eroding the laser advantage outside long-range high-beam duty [8]. As microLED yields improve, mid-premium buyers may see little reason to pay extra for laser reach that U.S. regulations partially cap. Suppliers increasingly position laser as a booster inside LED-led modules.

Laser Headlight Market Opportunities

Emerging-Market Premiumization in India and ASEAN

India's Bharat NCAP program, launched in October 2023, has made safety ratings a purchase factor for domestic buyers [15]. Rising premium SUV sales and a 29.4% India CAGR create room for localized laser-LED hybrid modules. Suppliers that assemble lamps in India or Thailand can avoid import duties and price laser options closer to local mid-premium budgets.

Software-Defined Lighting and Feature Subscriptions

Over-the-air beam-pattern updates can be sent to connected lamps, enabling premium feature-on-demand models like improved cornering modes or seasonal glare profiles. Road authorities and map companies can potentially benefit from anonymized data on road reflectivity, glare occurrences, and unlit areas. With this strategy, money from one-time hardware sales is transferred to ongoing software revenue.


Commercial-Vehicle Retrofit Programs

Truck fleets are an obvious early market since European regulations permit aftermarket kits when installers prove photometric compliance [2]. Installation takes only one shift thanks to pre-calibrated modules with specialized heat sinks and CAN bus adapters. Fleets that have already made telematics investments can reduce sales cycles by directly measuring collision reductions.


Road Projection and V2X Communication

Pixel-controlled laser beams can project lane guidance, crosswalk symbols, or turn warnings onto the road surface. Pilots on delivery vans in Germany already project pedestrian alerts during turns across bike lanes. As V2X networks expand, lamps become a communication channel to pedestrians and other drivers.

Hybrid Laser-microLED Modules for Mid-Segment EVs

Combining a compact laser spot for long range with a microLED array for shaping lets OEMs cut diode counts and cost while keeping a premium feature. This architecture also eases supply risk by reducing dependence on high-power diodes [13]. Mid-segment EVs priced around USD 35,000–50,000 represent the largest untapped volume pool.

Laser Headlight Market Future Outlook

Autonomous Driving and Lighting as Communication

Higher automation levels require lighting that serves sensors as well as humans. Laser-assisted beams extend camera detection range, and projection functions let driverless vehicles signal intent to pedestrians. The U.S. DOE and transport agencies continue to fund connected-vehicle research [21], and lamps will likely become a standard output device for V2X messaging by the early 2030s.

Software-Defined Vehicle Platforms

Centralized vehicle computers treat headlamps as edge nodes that receive over-the-air updates. This allows OEMs to refine glare-masking algorithms after sale and monetize optional beam features. Suppliers with in-house control software and ASIC capability will capture more value than those selling optics alone, reshaping competition across the Laser Headlight Market.

Electrification Supercycle

The IEA projects electric cars could exceed 40% of global new-car sales by 2030 under stated policies [3]. Efficiency-focused EV platforms favor compact, low-power lighting that supports aerodynamic front ends. BloombergNEF's outlook points to continued battery cost declines [20], freeing budget for premium features such as laser high beams on mid-segment models.

Sustainability and Materials Circularity

The European Commission's proposed End-of-Life Vehicles Regulation would raise recycled-content and design-for-dismantling requirements [18]. Laser modules use rare-earth phosphors and gallium nitride diodes, so suppliers face pressure to document material sourcing and enable module-level repair. Lifecycle carbon reporting will increasingly influence OEM sourcing decisions.

Regional Market Share Analysis

Region Key Metric Primary Investment Themes
North America USD 4.49 Billion ADB adoption, IIHS ratings, premium SUV and pickup trims
Europe 33.4% share UNECE R149 beams, German OEM programs, truck safety
Asia-Pacific 35.6% share Chinese premium EVs, Japanese diode supply, Korean OEM programs
South America 25.4% CAGR Imported premium vehicles, Brazilian assembly
Middle East & Africa 28.2% CAGR Gulf luxury-car demand, desert night driving
Total USD 19.94 Billion —

Regional demand in the Laser Headlight Market follows premium vehicle production, regulatory permissiveness toward high-luminance beams, and night-driving conditions. Asia-Pacific and Europe together account for more than two-thirds of value, while Gulf markets post the fastest growth from a smaller base.


North America

Country Key Metric Key Driver
US 81.5% share of region Premium SUVs, IIHS rating pressure
Canada 26.1% CAGR Long winter nights, rural highways
Mexico USD 0.37 Billion Premium vehicle assembly for export

The 2022 FMVSS No. 108 amendment opened the U.S. to adaptive beams, but photometric ceilings still limit laser reach compared with European units [1]. The US dominates regional demand through premium SUVs and electric trucks, and IIHS ratings push automakers to improve standard lighting across trims [5]. Canada benefits from long winter nights and rural highways, while Mexico's growing premium assembly base adds export-oriented lamp volumes.


Europe

Country Key Metric Key Driver
Germany 34.5% share of region Premium OEM flagship programs
UK USD 0.91 Billion Premium import demand
France 11.2% share of region Domestic Tier-1 lighting suppliers
Italy 25.8% CAGR Sports and luxury car production
Spain USD 0.45 Billion Vehicle assembly exports
Nordic Countries 27.3% CAGR Long winter darkness, wildlife risk
Russia 2.1% share of region Constrained premium imports
Rest of Europe 15.0% share of region Central European assembly hubs

European adoption benefits from UNECE R149, which permits higher-luminance adaptive beams than U.S. rules [2]. Germany leads because its premium brands introduced series laser lighting and continue to offer it on flagship models. The Nordic Countries grow quickly due to extended darkness and wildlife-collision risk, and Euro NCAP protocols reinforce night-visibility investment across the region [6].


Asia-Pacific

Country Key Metric Key Driver
China 46.2% share of region Domestic premium EV brands
India 29.4% CAGR Bharat NCAP, premium SUV growth
Japan USD 1.35 Billion Lamp and diode manufacturing base
South Korea 11.4% share of region Intelligent lamp programs
ASEAN 28.0% CAGR Thai and Indonesian assembly hubs
Rest of Asia-Pacific 6.1% share of region Australian premium imports

China anchors regional value through domestic premium EV brands that use advanced lighting for visual differentiation [17]. Japan holds a strategic position as home to leading lamp makers and blue diode producers [9][13]. South Korea's OEMs and Hyundai Mobis drive intelligent lamp development [12], while India's high growth reflects Bharat NCAP and rising premium SUV sales [15].


South America

Country Key Metric Key Driver
Brazil 61.5% share of region Local premium assembly
Argentina USD 0.13 Billion Recovering premium imports
Rest of South America 23.9% CAGR Freight-corridor retrofits

Demand centers on imported premium vehicles and limited local assembly of high-end models in Brazil. Import tariffs and currency volatility keep laser options rare outside top trims. Argentina's premium segment is small but recovering, and regional fleets show interest in retrofit kits for long-distance freight corridors.


Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 32.6% share of region Premium SUV demand, new highways
UAE 30.1% CAGR Luxury vehicle concentration
South Africa USD 0.16 Billion Premium vehicle export assembly
Egypt 6.4% share of region Emerging premium segment
Rest of MEA 18.2% share of region Gulf state imports

Saudi Arabia and the UAE combine high premium-car penetration with long-distance desert driving at night, creating strong demand for long-range beams. Saudi Vision 2030 investment in road networks expands highway mileage. South Africa supports premium vehicle assembly for export, and Egypt's market grows from a small base.


Laser Headlight Market By Region, 2025-2035

Laser Headlight Market Segmentation

By Vehicle Type

The Laser Headlight Market by vehicle type remains dominated by passenger models, though commercial categories are gaining momentum.

Segment Key Metric Primary Demand Driver
Passenger Vehicles 78.3% share Premium trim differentiation
Light Commercial Vehicles USD 2.59 Billion Delivery-van night operations
Medium & Heavy Commercial Vehicles 27.0% CAGR Long-haul accident reduction


Passenger Vehicles lead because German and Japanese premium brands introduced laser lighting on flagship sedans and SUVs, though U.S. photometric limits slow incremental gains. Light Commercial Vehicles sit in the middle, with fleet budgets steering many operators toward hybrid laser-LED units. Medium & Heavy Commercial Vehicles grow fastest as logistics firms quantify savings from fewer night-time collisions, and lamp makers are developing modules suited to tall cab designs.

By Technology Type

The Laser Headlight Market by technology type is shifting from fixed-pattern systems toward software-controlled designs.

Segment Key Metric Primary Demand Driver
Intelligent Laser Headlights 27.1% CAGR Pixel-level glare masking
Conventional Laser Headlights 63.5% share Carry-over premium programs


Conventional Laser Headlights retain the majority because first-generation programs from European premium OEMs remain in production. Intelligent Laser Headlights grow faster as MEMS scanners and integrated control ASICs enable dynamic beam remapping based on camera feedback. Over-the-air updates let these units learn driver preferences and coordinate with navigation data, and falling electronics costs are narrowing the price gap with conventional designs.

By Sales Channel

The Laser Headlight Market by sales channel depends heavily on factory installation, but retrofit activity is accelerating.

Segment Key Metric Primary Demand Driver
OEM 81.0% share Line-side calibration and integration
Aftermarket 27.1% CAGR Commercial-fleet retrofits


OEM channels dominate because laser modules require precise alignment, thermal design, and electronic integration best handled on the assembly line. Aftermarket demand grows faster as fleets and enthusiasts seek performance gains without buying new vehicles. European rules ease this path when installers document photometric compliance, while U.S. installers face FMVSS No. 108 hurdles and state inspections that slow uptake.

By Application

The Laser Headlight Market by application reflects laser luminance strengths on long, straight roads.

Segment Key Metric Primary Demand Driver
High Beam 44.4% share Long-range highway visibility
Low Beam USD 5.98 Billion Multi-mode cost amortization
Cornering Light 27.0% CAGR Urban side-street visibility
Daytime Running Light 11.6% share Brand lighting signatures


High Beam applications lead because they exploit the core advantage of laser light: intense, long-range illumination. Cornering Light grows fastest as automated-driving programs prioritize side visibility during low-speed turns, and laser modules hold brightness at sharp angles where LEDs lose efficacy. Low Beam and Daytime Running Light roles spread module costs across several functions, though tighter thermal limits in enclosed housings constrain them.

Competitive Benchmarking

The Laser Headlight Market is moderately concentrated, with an estimated Herfindahl-Hirschman Index of roughly 1,000–1,200. The top five suppliers hold an estimated 50–65% of revenue, led by established Japanese and European lamp makers with long OEM relationships. Competition centers on intelligent control software, thermal engineering, and secure access to blue laser diodes rather than price alone.

Company Est. Revenue Share Range Key Offerings for Laser Headlight Market Strategic Positioning
Koito Manufacturing ~13–16% Laser and LED headlamp modules for Japanese OEMs Scale leader with deep Toyota ties
Valeo ~11–14% Adaptive laser-LED headlamps, aftermarket lighting Software-led lighting and ADAS integration
FORVIA HELLA ~10–13% High-definition and laser-assisted headlamps Pixel-light and electronics specialist
ams OSRAM ~9–12% Laser diodes, phosphor converters, lighting modules Component and semiconductor supplier
ZKW Group ~7–10% Premium laser headlamp systems Supplier to German premium OEMs
Marelli ~6–9% Automotive lighting and laser modules Restructuring-focused European supplier
Stanley Electric ~6–8% Laser and LED lamps, commercial-vehicle modules Commercial-vehicle co-development
Hyundai Mobis ~4–7% Intelligent headlamps, projection lighting Captive Korean OEM supplier
Nichia Corporation ~3–5% High-power blue laser diodes Critical upstream component source
Mitsubishi Electric ~2–4% Lighting control electronics, road projection Electronics and projection specialist


Recent News & Developments

  • Marelli (June 2025): Filed for voluntary Chapter 11 restructuring in the United States to reduce debt while continuing operations, a reminder of margin pressure among lighting suppliers [19]
  • IEA (May 2025): Its Global EV Outlook reported more than 17 million electric car sales in 2024, reinforcing demand for energy-efficient lighting [3]
  • ams OSRAM (2024): Announced a portfolio review and divestment of non-core units to focus on automotive lighting and semiconductor products, including laser components [7]
  • UNECE WP.29 (June 2024): Advanced amendments to road-illumination provisions under Regulation No. 149, refining adaptive-beam requirements used by laser systems [2]
  • IIHS (March 2024): Kept requirements for acceptable or good headlights in its TOP SAFETY PICK criteria, sustaining pressure on OEM lighting performance [5]
  • FORVIA HELLA (2024): Expanded series production of high-definition pixel headlamps, increasing competitive pressure on laser-only designs [8]
  • Bharat NCAP (October 2023): India's new crash-test program took effect, raising safety awareness among premium vehicle buyers [15]

Laser Headlight Market Report Scope

Parameter Details
Market Scope Laser Headlight Market covering laser-based and laser-assisted headlamp systems across vehicle types, technologies, sales channels, applications, and regions.
Study Period 2021–2035 (Historical: 2021–2024; Base Year: 2025; Forecast: 2026–2035)
CAGR 26.85% (2026–2035)
Market Size checkpoints USD 19.94 Billion (2025); USD 25.63 Billion (2026); USD 69.98 Billion (2030); USD 217.96 Billion (2035)
Fastest Growing Segments Medium & Heavy Commercial Vehicles; Intelligent Laser Headlights; Aftermarket; Cornering Light
Companies Profiled Koito Manufacturing, Valeo, FORVIA HELLA, ams OSRAM, ZKW Group, Marelli, Stanley Electric, Hyundai Mobis, Nichia Corporation, Mitsubishi Electric
Valuation Currency USD Billion

FAQs

How do laser headlights compare with LED high beams in range?
Laser high-beam modules typically reach about 600 meters, roughly double a conventional LED high beam. Their small emitter also lets designers shrink headlamp housings and reduce frontal drag [7].
Are laser headlights safe for other road users' eyes?
Production units never emit raw laser light; blue diode output passes through a phosphor that converts it into diffuse white light. Interlocks shut the diode instantly if the converter is damaged, and certification follows IEC 60825-1 [14].
What should fleet buyers check before procuring retrofit kits in the Laser Headlight Market?
Buyers should confirm documented photometric compliance for each operating jurisdiction, CAN bus compatibility, and dedicated heat sinks. Model-specific brackets matter, so universal kits rarely deliver their promised beam pattern [2].
Which supply-chain risk matters most for investors in the Laser Headlight Market?
Blue laser diode output is concentrated among a few producers, so one fab disruption can delay entire vehicle programs. Investors should favor lamp makers with dual-sourced diodes or hybrid laser-LED designs [13].
Do intelligent laser headlights need recalibration after repairs?
Yes, units linked to forward cameras need recalibration after windshield, camera, or bumper work because glare masking depends on precise alignment. Workshops require OEM diagnostic tools, which raises service costs [22].
Could motorcycles become a new demand pocket for the Laser Headlight Market?
Premium motorcycle makers are evaluating compact laser modules because small emitters suit narrow fairings, a niche the Laser Headlight Market has barely tapped. Vibration resistance and cooling remain the main engineering hurdles [13].
What role do phosphor converters play in long-term performance?
Phosphor degradation at high temperatures shifts color toward blue and lowers output. Suppliers are moving to ceramic phosphor plates that hold color stability in hot housings [7].
Author
Author Author Profile Triveni Bhoyar LinkedIn Senior Research Analyst
Triveni Bhoyar has over 5 years of experience in the market research industry, specializing in the Automotive and Aerospace & Defense sectors. She has contributed to 200+ reports, including numerous custom projects for leading global companies, delivering solutions to complex business challenges. Renowned for her ability to generate valuable insights, Triveni excels in addressing unique market dynamics with precision and depth. Her expertise spans market sizing, competitive intelligence, and trend analysis, enabling clients to craft data-driven growth strategies. With strong analytical rigor and a client-centric approach, she plays a pivotal role in driving impactful, strategic decision-making.
Co-Author Co-Author Profile Swapnil Palwe LinkedIn Team Lead - Research
With a technical background as Bachelor's in Mechanical Engineering, with MBA in Operations Management , Swapnil has 6+ years of experience in market research, consulting and analytics with the tasks of data mining, analysis, and project execution. He is the POC for our clients, for their consulting projects running under the Automotive/A&D domain. Swapnil has worked on major projects in verticals such as Aerospace & Defense, Automotive and many other domain projects. He has worked on projects for fortune 500 companies' syndicate and consulting projects along with several government projects.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















