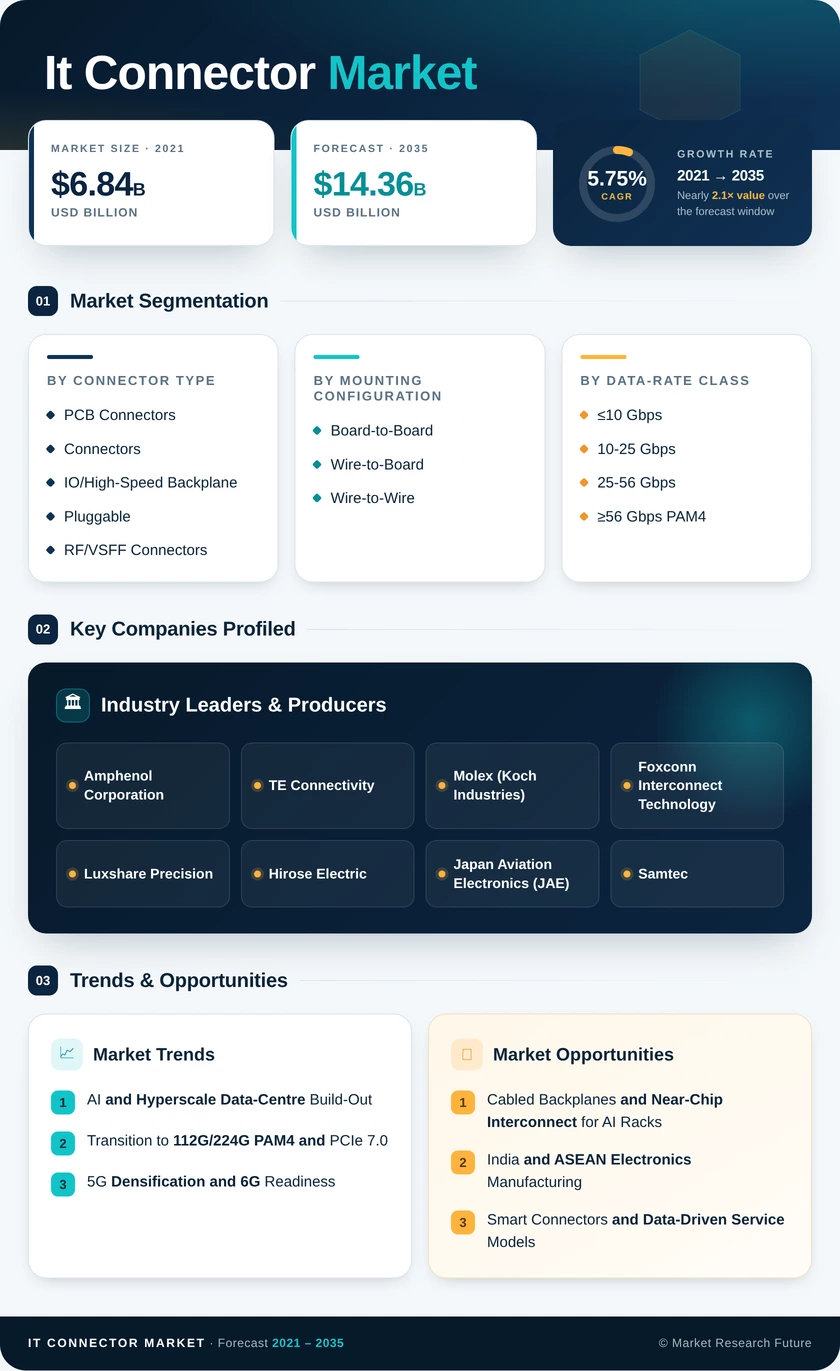
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Connector Type | PCB Connectors; Connectors; IO/High-Speed Backplane and Pluggable; RF/VSFF Connectors; Circular and Rectangular Connectors; Microminiature Connectors | PCB Connectors — 47.4% (share) | IO/High-Speed Backplane and Pluggable — 5.92% (CAGR) |
| By Mounting Configuration | Board-to-Board; Wire-to-Board; Wire-to-Wire | Board-to-Board — 37.8% (share) | Wire-to-Board — 6.45% (CAGR) |
| By Data-Rate Class | ≤10 Gbps; 10-25 Gbps; 25-56 Gbps; ≥56 Gbps PAM4 | ≤10 Gbps — 50.3% (share) | ≥56 Gbps PAM4 — 7.31% (CAGR) |
| By End-user Industry | IT and Telecom (incl. Data Centers); Automotive and E-mobility; Industrial Automation; Medical Devices; Consumer Electronics; Other End-user Industries | IT and Telecom (incl. Data Centers) — 39.9% (share) | Industrial Automation — 6.52% (CAGR) |
| By Application | Servers and Storage; Networking and Switching Equipment; 5G/6G Base-Stations; EV Powertrain / ADAS; Factory Robots; Other Applications | Servers and Storage — 31.4% (share) | 5G/6G Base-Stations — 6.74% (CAGR) |
| By Material | Standard Thermoplastics; Halogen-Free Compounds | Standard Thermoplastics — 72.8% (share) | Halogen-Free Compounds — 6.02% (CAGR) |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | Middle East & Africa — 29.4% (share) | Asia-Pacific — 6.9% (CAGR 2026–2035) |
Market Segmentation Overview
By Connector Type
| Sub-Segment | Key Trend |
|---|---|
| PCB Connectors | Fine-pitch mezzanine demand rising with onshore board assembly |
| Connectors | Stable replacement demand in legacy equipment |
| IO/High-Speed Backplane and Pluggable | Migration to 112G and 224G cages for AI switching |
| RF/VSFF Connectors | Small-cell and fiber-dense rack deployments |
| Circular and Rectangular Connectors | Sealed housings for harsh industrial duty |
| Microminiature Connectors | Adoption in surgical robots and CubeSats |
PCB Connectors lead because every board-level design depends on headers, sockets, and mezzanine interfaces, a base reinforced by reshoring of board assembly. IO/High-Speed Backplane and Pluggable grows fastest as switch and GPU platforms move to 112 Gbps-per-channel cages. RF/VSFF Connectors and Microminiature Connectors occupy smaller but higher-value niches tied to 5G sites and space-constrained devices.
By Mounting Configuration
| Sub-Segment | Key Trend |
|---|---|
| Board-to-Board | Stacked mezzanine designs for low Z-height |
| Wire-to-Board | Serviceable harnesses for EV packs and appliances |
| Wire-to-Wire | Miniaturized sealed variants for robotics |
Board-to-Board leads because laptops and switch blades need stacked, low-profile interconnect between modules. Wire-to-Board grows fastest since harness-based designs simplify field service in battery packs and appliances. Wire-to-Wire keeps its role in motor drives and compressors where board space is limited.
By Data-Rate Class
| Sub-Segment | Key Trend |
|---|---|
| ≤10 Gbps | Cost-optimized links for sensors and embedded systems |
| 10-25 Gbps | Enterprise switch and storage refresh |
| 25-56 Gbps | 400G networking and PCIe 5.0 adoption |
| ≥56 Gbps PAM4 | 224G lanes for AI fabrics and memory pooling |
The ≤10 Gbps class leads on volume because industrial sensors and infotainment units rarely need more bandwidth and benefit from longer reach. The ≥56 Gbps PAM4 class grows fastest as AI inference and NVMe-oF storage fabrics move to 224 Gbps lanes. The 10-25 Gbps and 25-56 Gbps classes track enterprise upgrade cycles between those extremes.
By End-user Industry
| Sub-Segment | Key Trend |
|---|---|
| IT and Telecom (incl. Data Centers) | Hyperscale ODM hardware and backbone refresh |
| Automotive and E-mobility | ADAS camera and radar links, high-current packs |
| Industrial Automation | Edge AI controllers and cobots |
| Medical Devices | Certified miniature connectors for imaging and robotics |
| Consumer Electronics | Thin-profile laptops and wearables |
| Other End-user Industries | Aerospace, defense, and energy programs |
IT and Telecom (incl. Data Centers) leads because hyperscalers buy cages, mezzanines, and twin-ax assemblies in very large volumes. Industrial Automation grows fastest as edge AI and machine vision bring server-grade interconnect into factories. Automotive, E-mobility and Medical Devices add higher-value demand tied to safety and certification requirements.
By Application
| Sub-Segment | Key Trend |
|---|---|
| Servers and Storage | AI super-clusters and orthogonal backplanes |
| Networking and Switching Equipment | 800G and 1.6T port upgrades |
| 5G/6G Base Stations | Compact radio units with SN and MDC fiber links |
| EV Powertrain / ADAS | Zonal networks and battery interconnect |
| Factory Robots | Hot-swap modular connectors for servo drives |
| Other Applications | PCs, peripherals, and test equipment |
Servers and Storage lead because colocation, edge, and AI facilities depend on high-speed cages and orthogonal backplanes. 5G/6G Base Stations grow fastest as operators shrink radio units and raise antenna counts, adopting duplex fiber and coax links in remote radio heads. EV Powertrain / ADAS and Factory Robots follow on electrification and automation.
By Material
| Sub-Segment | Key Trend |
|---|---|
| Standard Thermoplastics | Mature molding and cost leadership |
| Halogen-Free Compounds | RoHS- and REACH-driven conversion programs |
Standard Thermoplastics lead because established molding cycles and broad resin supply keep part costs low. Halogen-Free Compounds grow faster as EU restrictions on brominated flame retardants tighten, and OEMs specify eco-compliant housings. Suppliers that secure UL 94 V-0 approvals early gain an edge in EU automotive design-ins.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA