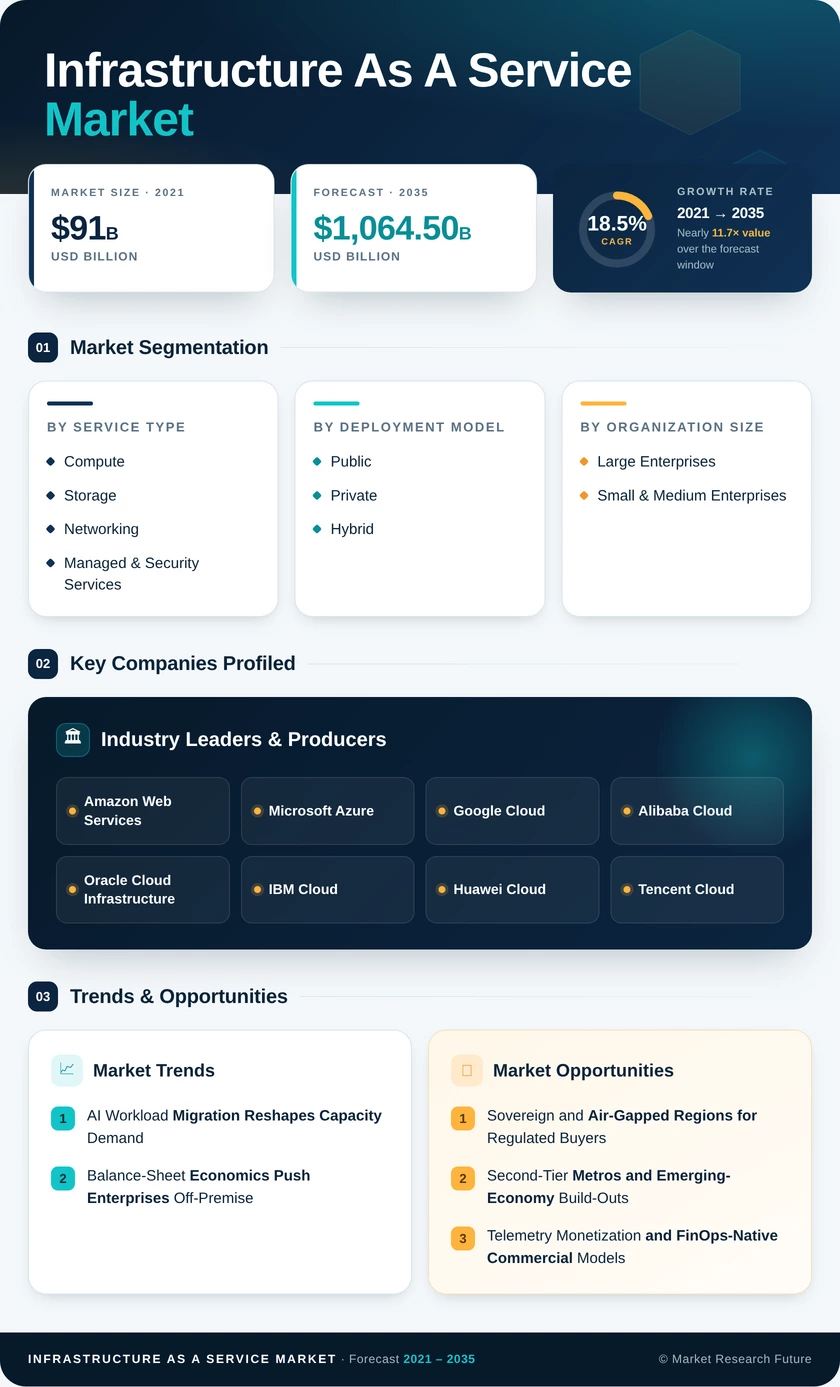
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Service Type | Compute; Storage; Networking; Managed & Security Services | Compute | Managed & Security Services |
| By Deployment Model | Public; Private; Hybrid | Public | Hybrid |
| By Organization Size | Large Enterprises; Small & Medium Enterprises | Large Enterprises | Small & Medium Enterprises |
| By End-User Vertical | BFSI; IT & Telecom; Retail & E-commerce; Healthcare; Manufacturing; Government & Public Sector; Media & Entertainment | BFSI | Healthcare |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | North America | Asia-Pacific |
Market Segmentation Overview
By Service Type
| Sub-Segment | Key Trend |
| Compute | Accelerator-dense instances displacing general-purpose fleets in revenue mix |
| Storage | Tiered archival pricing expands as model checkpoints and telemetry accumulate. |
| Networking | Private interconnect and inter-region bandwidth become negotiated line items. |
| Managed & Security Services | Continuous compliance monitoring bundled into base contracts. |
Service-type mix is drifting toward higher-value lines. Raw capacity resale carries thin margins, so providers increasingly attach monitoring, optimization and compliance tooling to compute commitments rather than selling them separately.
By Deployment Model
| Sub-Segment | Key Trend |
| Public | Remains default for elastic and greenfield workloads |
| Private | Persists in defence, banking and health where isolation is contractually mandated |
| Hybrid | Fastest expansion as burst capacity supplements retained core systems |
Deployment choice is now an architecture decision made workload by workload rather than a single corporate policy. Most large enterprises operate all three models simultaneously and manage them through a common control plane.
By Organization Size
| Sub-Segment | Key Trend |
| Large Enterprises | Multi-year committed-use agreements with negotiated regional pricing |
| Small & Medium Enterprises | Partner-delivered migration bundles unlock previously stalled adoption. |
Large enterprises supply the revenue base; smaller firms supply the growth rate. Channel partners rather than direct sales teams drive most mid-market conversion, which shifts acquisition economics toward ecosystem investment.
By End-User Vertical
| Sub-Segment | Key Trend |
| BFSI | Documented exit plans and provider redundancy required by supervisors |
| IT & Telecom | Network function virtualization and operator-hosted edge zones |
| Retail & E-commerce | Elastic capacity sized around seasonal peaks rather than averages |
| Healthcare | Imaging archives and genomics pipelines outgrow hospital-owned storage. |
| Manufacturing | Industrial telemetry and digital twin simulation workloads |
| Government & Public Sector | Cloud-first mandates paired with national authorization schemes |
| Media & Entertainment | Rendering and transcoding bursts tied to production calendars |
Vertical demand patterns diverge sharply on predictability. Regulated sectors buy slowly but commit deeply, while retail and media buy elastically and treat capacity as a variable production input.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA