India Lead Acid Battery Market (2026 - 2035)

India Lead Acid Battery Market Research Report By Application (SLI (Start, Light, and Ignition) Batteries, Industrial Batteries, Other Applications) - Forecast to 2035
ID: MRFR/EnP/53601-HCR 200 Pages Chitranshi Jaiswal Last Updated: October 07, 2026
India Lead Acid Battery Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)8.4%
2025 Market SizeUSD 6.12 Billion
2035 Market SizeUSD 13.70 Billion
Key Players
Exide Industries Ltd
Amara Raja Energy & Mobility Ltd
Luminous Power Technologies
Livguard
Okaya Power Group
Eastman Auto & Power Ltd
Opportunities
  • Advanced Designs for Start-Stop Vehicles
  • Closed-Loop Recycling Integration
  • Emerging Export Markets in Africa and South Asia

India Lead Acid Battery Market Summary

The India Lead Acid Battery Market was valued at USD 6.12 billion in 2025. It is forecast to grow from USD 6.63 billion in 2026 to USD 13.70 billion by 2035, a CAGR of 8.4% over 2026–2035. Two catalysts anchor this outlook. The Union Cabinet's ₹89,047 crore revival package for BSNL, approved in June 2023, is funding a nationwide 4G and 5G build-out, and every new site needs backup power [9]. The Battery Waste Management Rules, 2022 are moving the industry toward a regulated, closed-loop supply of secondary lead [2].

Technology across the sector is shifting rather than standing still. Tall tubular batteries are replacing flat-plate designs in home inverters. Valve-regulated (VRLA) cells now dominate telecom and data centre UPS banks, and enhanced flooded (EFB) and absorbent glass mat (AGM) types are entering vehicles with start-stop systems. Competitive pressure comes from lithium-ion, which the government backs through an ₹18,100 crore production-linked incentive (PLI) scheme for 50 GWh of advanced chemistry cell capacity [12].

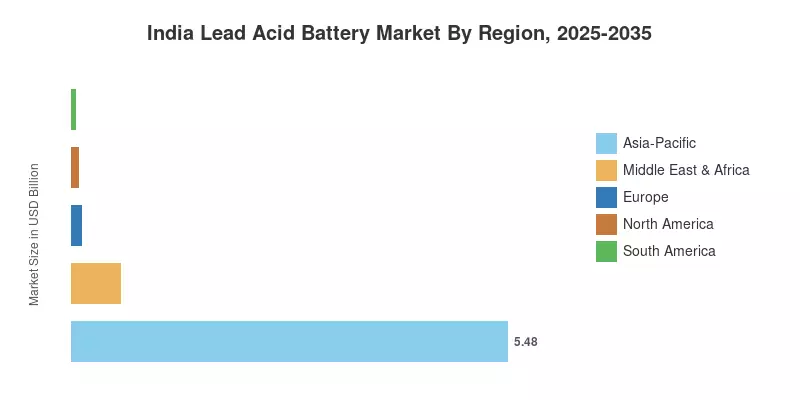
Regionally, this report tracks revenue by destination of India-made batteries. Asia-Pacific, which includes domestic Indian consumption, holds 89.6% of revenue. Middle East & Africa is the fastest-growing destination at a 10.2% CAGR, and it is also the second-largest, served through established distributor networks in the Gulf and East Africa [24]. Over the next decade, the India Lead Acid Battery Market will depend on how well producers defend stationary and replacement demand while lithium-ion captures traction applications.

Key Report Takeaways

• By Application

  • SLI (start, light, and ignition) batteries held a 58.4% share of the India Lead Acid Battery Market in 2025, sustained by a growing vehicle parc and three-to-four-year replacement cycles [1]
  • Demand for industrial batteries in the India Lead Acid Battery Market is projected to expand at a 10.1% CAGR through 2035, led by telecom towers, data centres and railway signalling [7]
  • Revenue from other applications reached USD 0.49 billion in 2025, covering e-rickshaws, solar home systems and portable uses

• By Region

  • Asia-Pacific, anchored by domestic consumption, accounted for 89.6% of India Lead Acid Battery Market revenue in 2025
  • Middle East & Africa is the fastest-growing destination, expanding at a 10.2% CAGR on Gulf telecom and African automotive aftermarket demand [24]
  • Europe absorbed USD 0.12 billion of India-made batteries in 2025, mostly industrial VRLA and small sealed units

Market Size and Forecast (2021–2035)

Market Research Future built the India Lead Acid Battery Market estimates bottom-up from producer revenues, vehicle production and parc data, telecom and data centre installation counts, and export statistics. Results were cross-checked against secondary lead availability and listed-company disclosures [1][14][15][24]. Values for 2021–2024 reflect historical data, 2025 is the base year, and 2026–2035 values are forecasts.
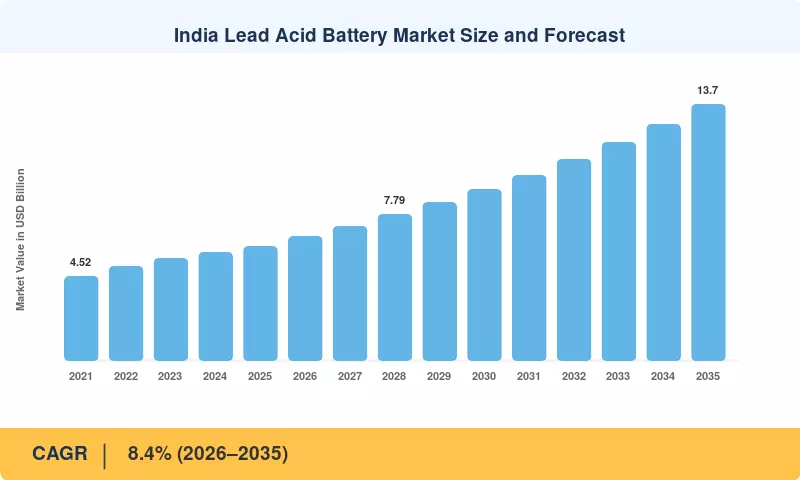
India Lead Acid Battery Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Vehicle parc growth and replacement demand +2.1% Pan-India, strongest in tier-2 and tier-3 cities Long-term (≥4 yr)
Telecom network expansion +1.4% Pan-India, rural circles Medium-term (2–4 yr)
Data centre capacity additions +1.1% Mumbai, Chennai, Hyderabad, NCR Medium-term (2–4 yr)
Railway modernization +0.8% Pan-India rail network Long-term (≥4 yr)
Power-reliability demand for inverters and UPS +1.0% North and East India, semi-urban areas Short-term (≤2 yr)
EPR-led formal recycling +0.6% Pan-India Medium-term (2–4 yr)
Export demand from MEA and SAARC +0.5% Gulf, Africa, South Asia Medium-term (2–4 yr)


Vehicle Parc Growth and Replacement Demand

SIAM project shows, domestic vehicle sales exceeded 25 million units in FY2024–2025, with two-wheelers making up over 19.6 million [1]. Volume is driven by installed parc rather than merely new sales because every internal combustion vehicle sold has a starter battery that needs to be changed every three to four years. The majority of SLI devices sold in India currently come from the aftermarket, which has larger profit margins than the original equipment supplier. As a result, the biggest growth lever for the Indian lead acid battery market is parc expansion.


Telecom Network Expansion

Each of the approximately 800,000 telecom towers in India is equipped with a battery bank to withstand power interruptions [7]. Approved in June 2023, the ₹89,047 crore BSNL package provides 4G and 5G spectrum and funds new sites, many of which are located in rural areas with unstable grid supply [9]. For almost 1.1 billion wireless users, private operators are still expanding 5G networks [8]. Due to their low initial cost, VRLA batteries continue to be the standard at legacy and lower-load locations.


Data Centre Capacity Additions

Colocation data centre capacity in India crossed roughly 1 GW in 2024, with several gigawatts more announced around Mumbai, Chennai and Hyderabad [22]. Large facilities typically size UPS batteries for 5–15 minutes of autonomy until generators start. Lithium-ion is gaining in hyperscale halls, but VRLA strings still win many enterprise and edge projects on capital cost. That keeps industrial demand growing faster than the overall market.

Railway Modernization

Indian Railways relies on lead-acid batteries for coach lighting, signalling, telecommunications and station backup. The Amrit Bharat Station Scheme, launched in 2023, covers redevelopment of more than 1,300 stations, each adding UPS and emergency-lighting loads [10]. Signalling upgrades add further demand for stationary cells built to railway specifications, a niche served by specialists such as HBL Engineering [16]. Procurement runs through multi-year rate contracts, which gives approved vendors predictable volumes.

Power-Reliability Demand for Inverters and UPS

All-India peak electricity demand hit a record of about 250 GW in May 2024, and distribution networks in many semi-urban and rural areas still face scheduled and unscheduled outages [13]. Households and small businesses respond with home inverters paired with tall tubular batteries. Heatwave summers create short, sharp demand spikes that brands now pre-stock for. This makes power reliability a short-term but recurring growth driver.

EPR-Led Formal Recycling

The Battery Waste Management Rules, 2022 assign extended producer responsibility (EPR) targets and require minimum recycled content in new lead-acid batteries, starting at 35% for 2024–25 [2]. Producers must register and file returns on the CPCB's centralized EPR portal [3]. Shifting scrap from informal smelters to registered recyclers improves secondary lead quality. Organized manufacturers gain a steadier, cheaper raw material base than primary lead.

Export Demand from MEA and SAARC

Indian brands export automotive and industrial batteries to the Gulf, Africa and neighbouring South Asian countries, competing on price against Chinese and Korean suppliers [24]. Designs built for high ambient temperatures suit these markets well. Export revenue remains a small share of the total, but it grows faster than domestic sales. It also helps producers use spare plant capacity during domestic demand lulls.

Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Falling lithium-ion pack prices −1.6% Pan-India Medium-term (2–4 yr)
Electrification of two- and three-wheelers −1.0% Urban India, North India e-rickshaw belt Long-term (≥4 yr)
Telecom and data centre shift to lithium −0.7% Metro clusters Medium-term (2–4 yr)
Lead price volatility −0.6% Pan-India Short-term (≤2 yr)
Informal recycling and compliance costs −0.5% Pan-India, unorganized aftermarket Short-term (≤2 yr)


Falling Lithium-Ion Pack Prices

Several projects in 2024 show, average lithium-ion pack prices dropped 20% to USD 115 per kWh, the biggest yearly decline since 2017 [6]. The cost gap should be further reduced by domestic cell plants funded by the ₹18,100 crore ACC PLI project [12]. In heavy-cycling applications, lithium already outperforms lead acid on a lifetime cost-per-cycle basis.


Electrification of Two- and Three-Wheelers

With a budget of ₹10,900 crore, the PM E-DRIVE scheme was approved in September 2024 and provides subsidies for electric busses, two-wheelers, and three-wheelers [23]. Lithium-ion traction packs are used in almost all modern electric vehicles. Once a major volume niche in North India, lead-acid e-rickshaws are losing market share to longer-range lithium models [4].


Telecom and Data Centre Shift to Lithium

Tower companies are installing lithium-ion at high-outage and space-constrained sites because it tolerates heat and partial charging better [7]. Hyperscale data centres are following the same path. This erodes the higher-value end of industrial demand even as unit volumes keep rising.

Lead Price Volatility

Lead makes up most of a battery's material cost, so swings in London Metal Exchange prices squeeze margins until list prices catch up [18][20]. Rupee depreciation adds to the cost of imported primary lead. Smaller brands without hedging capacity carry the most risk.

Informal Recycling and Compliance Costs

Unregulated smelting remains a serious public-health problem; UNICEF and Pure Earth estimated that about 275 million children in India have elevated blood lead levels, with informal battery recycling a major source [19]. Stricter enforcement raises compliance costs. It can also disrupt scrap supply temporarily as informal collectors exit.

India Lead Acid Battery Market Opportunities

Five opportunity areas stand out for producers and investors in the India Lead Acid Battery Market.

Advanced Designs for Start-Stop Vehicles

Carmakers adding idle start-stop systems to meet Corporate Average Fuel Efficiency norms need EFB and AGM batteries, which sell at a meaningful premium over conventional units. Lead-carbon additives improve charge acceptance and cycle life in these duty cycles. Producers that master both VRLA and flooded battery technology for these applications can raise average selling prices within the SLI segment without depending on volume growth.

Closed-Loop Recycling Integration

EPR rules and minimum recycled-content mandates reward manufacturers that control their own scrap collection and smelting [2]. Exide and Amara Raja have invested in captive recycling capacity, and mid-sized brands can follow through tie-ups with registered recyclers [14][15]. A formal battery recycling ecosystem lowers raw material cost, secures compliance and creates a credible environmental story for institutional buyers.

Emerging Export Markets in Africa and South Asia

Africa and South Asia offer the India Lead Acid Battery Market a growth outlet that domestic lithium substitution does not threaten in the near term. Vehicle parcs in Kenya, Nigeria, Bangladesh and Nepal are expanding, grid reliability remains weak, and buyers prioritize upfront price. Indian producers with heat-tolerant designs and dealer financing can take share from Chinese suppliers [24].

Battery-as-a-Service and Connected Products

IoT-enabled tubular batteries with app-based health monitoring are moving from pilot to mainstream. Usage data supports predictive replacement offers, warranty validation and dealer lead generation, turning a one-time sale into a recurring relationship. Telecom operators are also open to subscription-based backup contracts, where the supplier owns, monitors and replaces battery banks for a monthly fee [7].

Hybrid Solar and Rural Backup

PM Surya Ghar: Muft Bijli Yojana targets rooftop solar on 1 crore households with a ₹75,021 crore outlay [11]. Most installations are grid-tied, but hybrid systems in outage-prone areas still need affordable storage. Solar-rated tubular batteries suit rural homes, schools and clinics where lithium's higher upfront price remains a barrier.

India Lead Acid Battery Market Future Outlook

Four themes will shape the India Lead Acid Battery Market over the next decade.

A Two-Speed Vehicle Parc

Electric two-wheelers reached around 6% of India's two-wheeler sales in 2024, and the IEA expects that share to rise steadily [4]. Even so, the internal-combustion parc will keep growing in absolute terms well into the 2030s, and most electric cars still carry a 12 V auxiliary battery. SLI demand should therefore slow rather than shrink, with the aftermarket carrying most of the growth.

Stationary Storage Alongside Lithium

The Central Electricity Authority projects India will need about 47 GW of energy storage by 2031–32, most of it pumped hydro and lithium-ion at grid scale [13]. Lead-acid will not compete for those projects. Its role lies in distributed backup—telecom sites, UPS rooms, railway signalling and small solar systems—where upfront cost and proven recyclability matter more than energy density [5].

Circularity and ESG Reporting

Lead-acid batteries are among the most recycled consumer products worldwide, and the International Lead Association reports near-complete recovery in regulated markets [17]. India's EPR targets and SEBI's Business Responsibility and Sustainability Reporting framework push listed producers to disclose recycled content and emissions [2]. Firms with audited closed-loop supply will find it easier to win institutional tenders and export contracts.

Connected Products and Channel Consolidation

Organized brands are expected to keep gaining share of the India Lead Acid Battery Market as GST compliance, EPR registration and warranty digitization squeeze unbranded assemblers. Leading producers are investing in dealer management systems, QR-coded warranties and smart inverter batteries [14][15]. By 2035, connected products could make up a significant share of premium inverter battery sales.

Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 1.4% share Motorcycle, powersports and small sealed battery replacement
Europe USD 0.12 billion Industrial VRLA and small sealed units
Asia-Pacific 89.6% share Domestic vehicle parc, telecom, data centres, railways
South America USD 0.05 billion Automotive aftermarket through distributors
Middle East & Africa 10.2% CAGR Gulf telecom backup, African automotive aftermarket
Total USD 6.12 billion —

Market Research Future reports regional revenue for the India Lead Acid Battery Market by destination of India-manufactured batteries. Domestic consumption appears under Asia-Pacific (India); all other rows reflect export revenue.


North America

Country Metric (2025) Key Driver
US 58% of region Powersports and small sealed battery importers
Canada 7.6% CAGR Distributor-led aftermarket supply
Mexico USD 0.02 billion Automotive replacement batteries


Exports to North America are small and concentrated in motorcycle, powersports and small sealed VRLA batteries sold through aftermarket importers. US Section 301 tariffs on Chinese-origin batteries have encouraged importers to qualify alternative suppliers, and Indian producers with certified product lines are positioned to benefit [24]. Mexico serves as an entry point for automotive replacement batteries under distributor agreements.

Europe

Country Metric (2025) Key Driver
Germany 21% of region Industrial VRLA for UPS and telecom
UK USD 0.018 billion Small sealed and motorcycle batteries
France 6.9% CAGR Industrial standby demand
Italy 12% of region Automotive aftermarket
Spain USD 0.011 billion Solar standby and UPS
Nordic Countries 7.2% CAGR Telecom backup
Russia 9% of region Price-driven automotive demand
Rest of Europe USD 0.022 billion Eastern European aftermarket


European demand for India-made batteries centres on industrial VRLA units and small sealed batteries. The EU Battery Regulation (EU) 2023/1542 phases in carbon-footprint declarations, due-diligence obligations and recycled-content targets, which raises documentation requirements for exporters [25]. Indian suppliers with traceable secondary-lead sourcing under domestic EPR rules hold an advantage in meeting these obligations. Russia remains a price-driven outlet served mainly through trading houses.

Asia-Pacific

Country Metric (2025) Key Driver
China USD 0.04 billion Niche industrial imports
India 94.8% of region Vehicle parc, telecom, data centres, inverters
Japan 5.8% CAGR Specialized industrial cells
South Korea USD 0.02 billion Industrial standby
ASEAN 9.6% CAGR Tubular inverter and solar batteries
Rest of Asia-Pacific 3.1% of region SAARC neighbours' automotive and inverter demand


Domestic consumption makes up almost all Asia-Pacific revenue and, therefore, the bulk of the India Lead Acid Battery Market. Growth within India rests on the vehicle parc, telecom densification and data centre build-out described in Section 4, while PM E-DRIVE and PM Surya Ghar shape both risk and opportunity [11][23]. Nepal, Bangladesh, Bhutan and Sri Lanka form the core of Rest of Asia-Pacific, where Indian brands benefit from proximity and shared distribution. ASEAN is a smaller but faster-growing outlet for tubular inverter batteries.

South America

Country Metric (2025) Key Driver
Brazil 52% of region Automotive aftermarket distributors
Argentina 7.9% CAGR Eased import procedures
Rest of South America USD 0.014 billion Andean automotive replacement demand


South American revenue comes mainly from automotive replacement batteries shipped to independent distributors in Brazil. Mercosur's common external tariff and Brazil's INMETRO conformity requirements raise entry costs, so Indian exporters target segments where local producers are capacity-constrained. Easier import procedures in Argentina since 2024 support growth from a low base.

Middle East & Africa

Country Metric (2025) Key Driver
Saudi Arabia 24% of region Telecom and utility expansion
UAE USD 0.07 billion Re-export hub for Gulf and East Africa
South Africa 9.4% CAGR Load-shedding backup demand
Egypt 11% of region Automotive aftermarket
Rest of MEA USD 0.11 billion East and West African vehicle and solar demand


Middle East & Africa is the fastest-growing export destination. The India–UAE Comprehensive Economic Partnership Agreement, in force since May 2022, cut tariffs on a wide range of Indian manufactured goods and strengthened Dubai's role as a re-export hub [24]. Saudi Arabia's telecom and utility expansion under Vision 2030 supports industrial demand, while Kenya, Tanzania and Nigeria rely on affordable automotive and solar batteries.

India Lead Acid Battery Market By Region, 2025-2035

India Lead Acid Battery Market Segmentation

By Application

The India Lead Acid Battery Market is segmented by application into SLI (start, light, and ignition) batteries, industrial batteries, and other applications, with revenue tracked in USD billion.

Segment Metric (2025) Primary Demand Driver
SLI (start, light, and ignition) batteries 58.4% share Vehicle parc growth and aftermarket replacement
industrial batteries 10.1% CAGR (2026–2035) Telecom towers, data centres, railways, UPS
other applications USD 0.49 billion E-rickshaws, solar home systems, portable devices


SLI (start, light, and ignition) batteries remain the largest application in the India Lead Acid Battery Market, because cars, two-wheelers, tractors and commercial vehicles all need a starter battery replaced every few years. The fastest growth comes from industrial batteries, where stationary VRLA and tubular cells back up telecom towers, data centres, railway signalling and UPS systems, alongside motive-power units for forklifts. The smaller other applications segment faces the most lithium substitution, especially in e-rickshaws, though solar home systems provide a steady base.

Competitive Benchmarking

The India Lead Acid Battery Market is moderately concentrated, with an estimated Herfindahl-Hirschman Index of 1,700–1,900. The top five producers hold roughly 70–75% of revenue, led by two listed incumbents with national distribution networks [14][15]. Below them, a mid-tier of consumer brands competes in inverter and e-rickshaw batteries, while a long tail of regional and unbranded assemblers serves price-sensitive aftermarket buyers.

Company Est. Revenue Share Range Key Offerings for India Lead Acid Battery Market Strategic Positioning
Exide Industries Ltd ~30–34% Automotive, inverter, VRLA, traction and submarine batteries Market leader with the deepest aftermarket network; diversifying into lithium-ion cells
Amara Raja Energy & Mobility Ltd ~22–26% Amaron automotive, Quanta VRLA, tubular inverter batteries Strong OEM and telecom ties; building a lithium cell plant in Telangana
Luminous Power Technologies ~7–10% Tubular inverter batteries, home UPS, solar batteries Schneider Electric-backed leader in home backup
Livguard (SAR Group) ~4–6% Inverter and automotive batteries Fast-growing consumer brand with smart battery range
Okaya Power Group ~3–5% Inverter, solar and e-rickshaw batteries Strong presence in North India
Eastman Auto & Power Ltd ~3–5% Tubular inverter, solar and e-rickshaw batteries Export-oriented with a broad international footprint
Tata AutoComp GY Batteries ~2–4% Automotive SLI batteries for OEMs and aftermarket Tata AutoComp–GS Yuasa joint venture focused on OEM supply
Microtek International ~2–4% Inverter batteries and UPS systems Value-priced inverter-battery bundles
HBL Engineering Ltd ~1–3% Specialized VRLA, railway and defence batteries Niche industrial and railway specialist
Base Corporation Ltd ~1–2% Automotive and inverter batteries Regional brand with South India focus


Recent News & Developments

  • Union Cabinet (June 2023): Approved a ₹89,047 crore revival package for BSNL, including 4G and 5G spectrum; the resulting site rollout raises demand for telecom backup batteries. [9]
  • Ministry of Railways (August 2023): Laid the foundation for redevelopment of 508 stations under the Amrit Bharat Station Scheme, expanding UPS and emergency-lighting requirements. [10]
  • Amara Raja (September 2023): Adopted the name Amara Raja Energy & Mobility, signalling expansion into lithium-ion and EV charging while retaining its lead-acid core. [15]
  • Government of India (February 2024): Approved PM Surya Ghar: Muft Bijli Yojana with a ₹75,021 crore outlay for rooftop solar, adding demand for hybrid inverter batteries. [11]
  • Ministry of Heavy Industries (September 2024): Approved the ₹10,900 crore PM E-DRIVE scheme, accelerating lithium substitution in two- and three-wheeler traction. [23]
  • BloombergNEF (December 2024): Reported a 20% fall in lithium-ion pack prices to USD 115 per kWh, sharpening competition in stationary backup. [6]
  • SIAM (April 2025): Reported FY2024-25 domestic vehicle sales above 25 million units, widening the SLI replacement base. [1]

India Lead Acid Battery Market Report Scope

Parameter Details
Market Scope Revenue from lead-acid batteries manufactured in India, covering domestic sales and exports by destination; the India Lead Acid Battery Market is segmented By Application and By Region
Study Period 2021–2035 (Historical: 2021–2024; Base Year: 2025; Forecast: 2026–2035)
CAGR 8.4% (2026–2035)
Market Size checkpoints USD 6.12 billion (2025); USD 6.63 billion (2026); USD 9.15 billion (2030); USD 13.70 billion (2035)
Fastest Growing Segments industrial batteries (By Application); Middle East & Africa (By Region)
Companies Profiled Exide Industries, Amara Raja Energy & Mobility, Luminous Power Technologies, Livguard, Okaya Power Group, Eastman Auto & Power, Tata AutoComp GY Batteries, Microtek International, HBL Engineering, Base Corporation
Valuation Currency USD Billion, constant exchange rate basis

FAQs

What warranty terms are typical in the India Lead Acid Battery Market?
Car batteries usually carry 36–60 months of cover, split into a free-replacement period and a pro-rata period. Tall tubular inverter batteries often carry 36–72 months. Buyers should confirm the warranty is honoured through any authorised dealer, not only the selling outlet [14].
Which BIS standards apply to lead-acid batteries?
IS 7372 covers starter batteries for motor vehicles, and IS 15549 covers stationary valve-regulated cells [21]. Railway, telecom and government tenders commonly require compliance with these standards, making certification a practical precondition for institutional sales.
How does EPR registration affect new entrants to the India Lead Acid Battery Market?
Producers and importers must register on the CPCB portal and meet collection and recycled-content targets before selling [3]. Shortfalls attract environmental compensation, so most entrants sign agreements with registered recyclers from the first day of operation.
Do grid-connected rooftop solar systems need lead-acid batteries?
Grid-tied rooftop systems under PM Surya Ghar export surplus power to the grid and generally need no battery [11]. Hybrid and off-grid systems do use storage, and solar-rated tubular batteries remain the low-cost option there.
Which emerging use cases could add demand to the India Lead Acid Battery Market?
EV charging stations use small VRLA banks to back up control electronics and communication modules. Most current electric cars also retain a 12 V auxiliary battery, which partly offsets volume lost in traction applications [4].
How long does an inverter battery typically last?
Flat-plate inverter batteries usually last three to four years, while tall tubular designs often deliver five to seven years [17]. Service life across the India Lead Acid Battery Market depends heavily on regular water top-ups and correct charger settings.
How do lead price changes reach end customers?
Across the India Lead Acid Battery Market, manufacturers typically revise distributor price lists one to two quarters after sustained moves in LME lead prices [20]. Institutional contracts often include price-variation clauses indexed to published lead benchmarks.
Author
Author Author Profile Chitranshi Jaiswal LinkedIn Team Lead - Research
Chitranshi is a Team Leader in the Chemicals & Materials (CnM) and Energy & Power (EnP) domains, with 6+ years of experience in market research. She leads and mentors teams to deliver cross-domain projects that equip clients with actionable insights and growth strategies. She is skilled in market estimation, forecasting, competitive benchmarking, and both primary & secondary research, enabling her to turn complex data into decision-ready insights. An engineer and MBA professional, she combines technical expertise with strategic acumen to solve dynamic market challenges. Chitranshi has successfully managed projects that support market entry, investment planning, and competitive positioning, while building strong client relationships. Certified in Advanced Excel & Power BI she leverages data-driven approaches to ensure accuracy, clarity, and impactful outcomes.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.



















