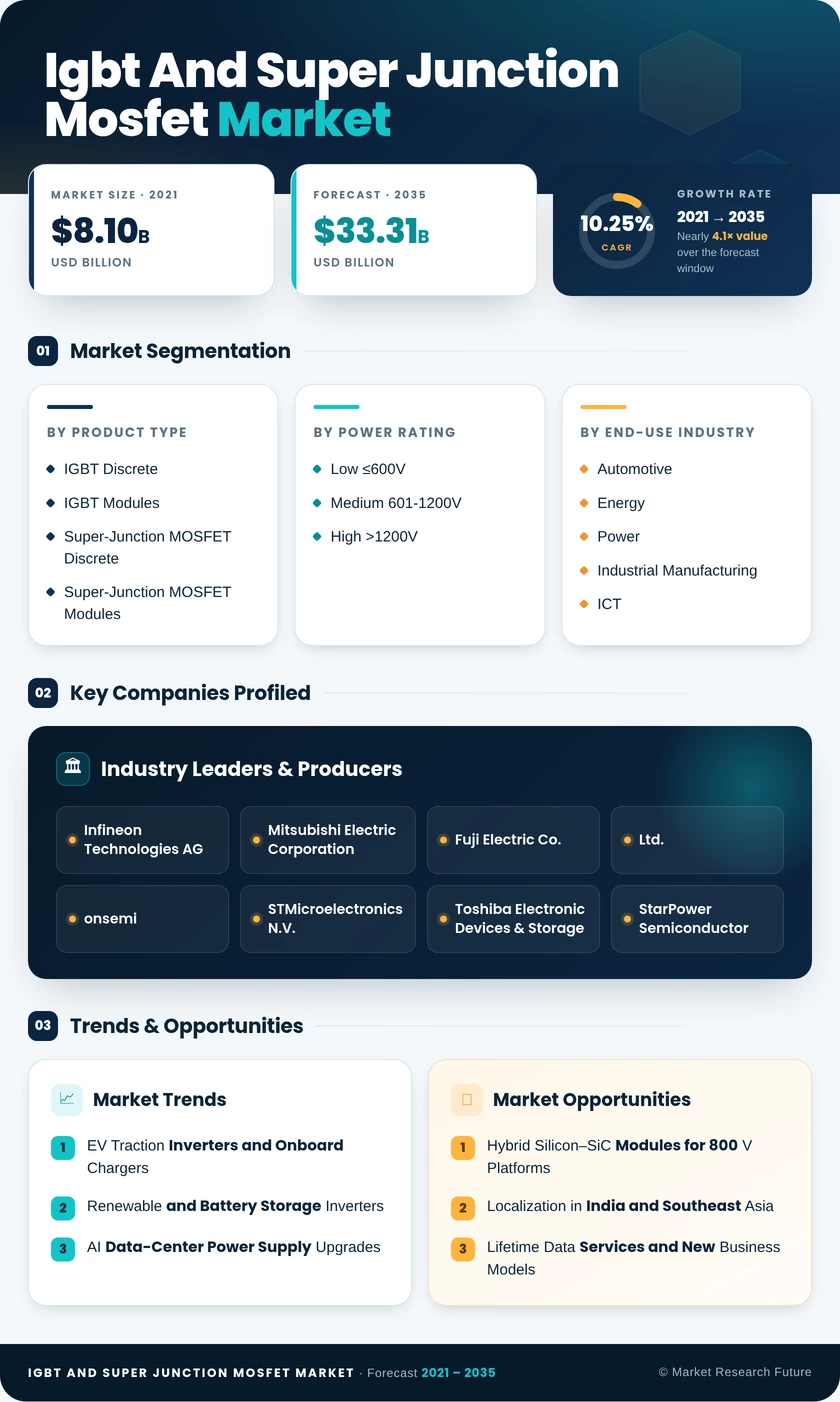
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Product Type | IGBT Discrete; IGBT Modules; Super-Junction MOSFET Discrete; Super-Junction MOSFET Modules | IGBT Modules (51.0% share) | Super-Junction MOSFET Modules (12.1% CAGR) |
| By Power Rating | Low ≤600V; Medium 601-1200V; High >1200V | Medium 601-1200V (38.5% share) | High >1200V (12.4% CAGR) |
| By End-Use Industry | Automotive; Energy and Power; Industrial Manufacturing; ICT and Data Centers; Consumer Electronics; Other End-Use Industries | Automotive (43.6% share) | Energy and Power (13.4% CAGR) |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | Asia-Pacific (52.0% share) | North America (11.4% CAGR) |
Market Segmentation Overview
By Product Type
| Sub-Segment | Key Trend |
|---|---|
| IGBT Discrete | Kelvin-emitter packages improve efficiency in sub-2 kW appliance inverters |
| IGBT Modules | Double-sided cooling raises current density in traction inverters |
| Super-Junction MOSFET Discrete | Lower on-resistance per die area for adapters and PFC |
| Super-Junction MOSFET Modules | Adoption in server PSUs and hybrid residential inverters |
IGBT Modules lead because traction and drive inverter makers value pre-validated thermal stacks that shorten assembly and qualification. Super-Junction MOSFET Modules grow fastest, pulled by server and telecom supplies that need high switching frequency at 230 VAC input. IGBT Discrete and Super-Junction MOSFET Discrete parts hold volume in cost-driven appliances and adapters, where single-package designs still meet power needs.
By Power Rating
| Sub-Segment | Key Trend |
|---|---|
| Low ≤600V | Price erosion in commoditized adapter and LED applications |
| Medium 601-1200V | 750 V and 1,200 V devices standardize around 800 V EV platforms |
| High >1200V | Press-pack and 3.3 kV modules for grid storage and wind |
Medium 601-1200V devices dominate because both 800 V EV traction and three-phase industrial drives fall in this band, supported by mature multi-fab supply. High >1200V devices grow fastest as utility-scale storage, wind converters, and rail traction require 1.7 kV to 3.3 kV ratings with field-stop structures that cut switching loss. Low ≤600V parts keep large unit volumes but face falling average selling prices.
By End-Use Industry
| Sub-Segment | Key Trend |
|---|---|
| Automotive | Rising device content per vehicle in 800 V battery-electric models |
| Energy and Power | Grid-forming storage inverters and pumped-storage converter retrofits |
| Industrial Manufacturing | IE4 motor rules expand variable-speed drive installations |
| ICT and Data Centers | Higher rack power and 800 V DC distribution |
| Consumer Electronics | Inverter appliance penetration across South and Southeast Asia |
| Other End-Use Industries | Rail traction and medical imaging power stages |
Automotive leads because each battery-electric vehicle combines traction, charging, DC-DC, and compressor stages, multiplying device demand per unit. Energy and Power grows fastest as utilities replace synchronous generation with four-quadrant storage inverters and retrofit pumped-storage plants with high-voltage converters. Industrial Manufacturing and ICT and Data Centers add steady demand through efficiency regulation and rising server power density.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA