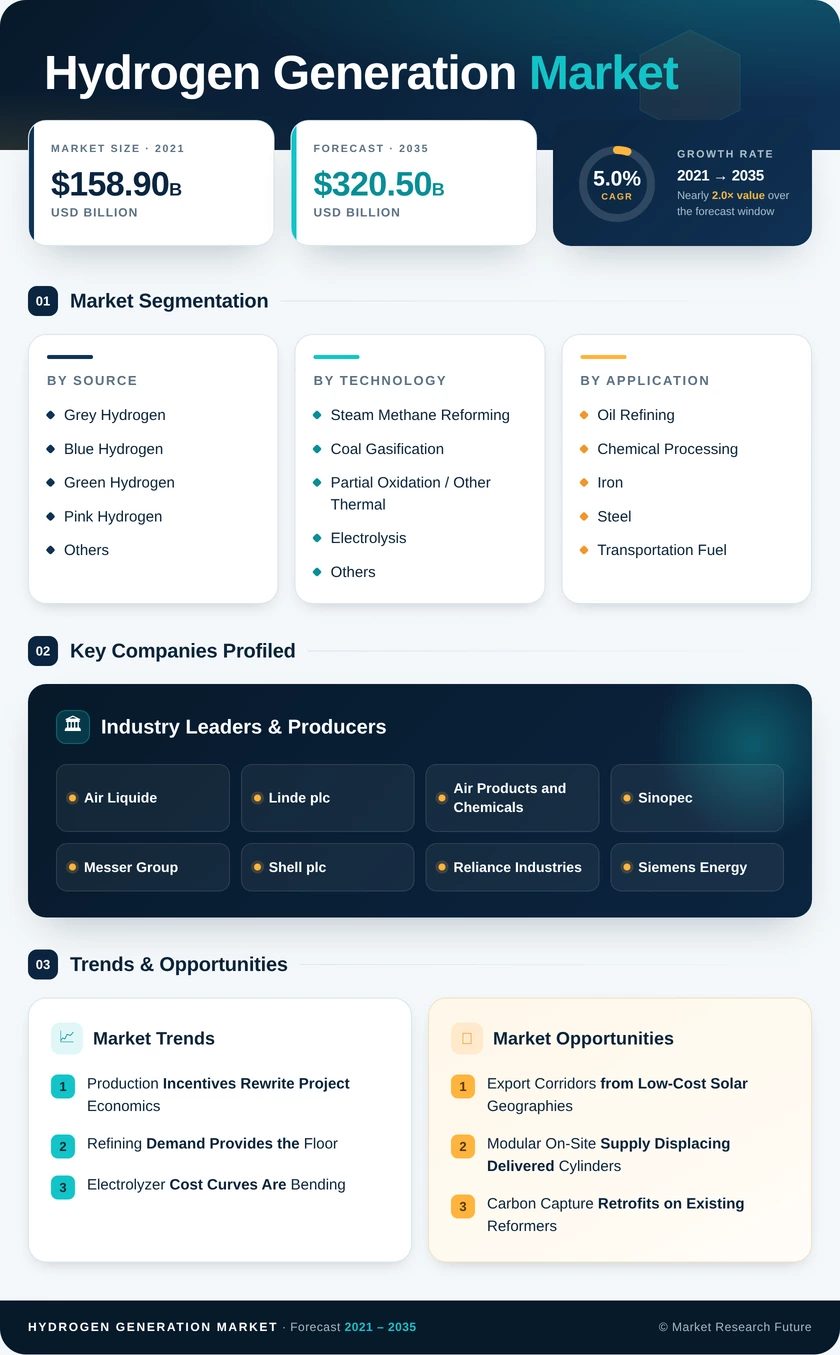
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Source | Grey Hydrogen, Blue Hydrogen, Green Hydrogen, Pink Hydrogen, Others | Grey Hydrogen | Green Hydrogen |
| By Technology | Steam Methane Reforming, Coal Gasification, Partial Oxidation / Other Thermal, Electrolysis, Others | Steam Methane Reforming | Electrolysis |
| By Application | Oil Refining, Chemical Processing, Iron and Steel, Transportation Fuel, Power and Energy Storage, Others | Chemical Processing | Transportation Fuel |
| By Geography | North America, Europe, Asia-Pacific, South America, Middle East & Africa | Asia-Pacific | Asia-Pacific |
Market Segmentation Overview
Segmentation across the Hydrogen Generation Market is built around three commercially meaningful axes — how the molecule is made, what equipment makes it, and who consumes it.
By Source
| Sub-Segment | Key Trend |
| Grey Hydrogen | Retains scale advantage where pipeline gas is cheap; share erodes gradually rather than collapsing |
| Blue Hydrogen | Growth tracks CO2 transport and storage permitting more than capture technology itself |
| Green Hydrogen | Steepest growth rate in the report, concentrated in subsidized and low-cost-power jurisdictions |
| Pink Hydrogen | Niche but strategically interesting in France, Sweden and select U.S. nuclear sites |
| Others | Includes chlor-alkali by-product recovery, waste pyrolysis and emerging thermochemical routes |
Source mix will shift more slowly than headline announcements imply. Sunk reformer capital and integrated chemical complexes create genuine inertia, and buyers switch only when regulation or subsidy makes switching cheaper than not switching.
By Technology
| Sub-Segment | Key Trend |
| Steam Methane Reforming | Benchmark cost route; capture retrofits extend asset life beyond 2035 |
| Coal Gasification | Concentrated in China; exposed to provincial carbon intensity tightening after 2027 |
| Partial Oxidation / Other Thermal | Valorizes refinery residues where feedstock is effectively free |
| Electrolysis | Alkaline dominates installed base; PEM wins where load ramping matters; solid oxide gains in waste-heat settings |
| Others | Methane pyrolysis and biomass-derived routes remain pre-commercial at scale |
Technology selection increasingly depends on the electricity contract rather than the equipment specification. Sponsors who secure firm, cheap and verifiably clean power find that stack choice becomes a secondary optimization problem.
By Application
| Sub-Segment | Key Trend |
| Oil Refining | Stable, price-inelastic demand driven by sulfur specifications and heavier crude slates |
| Chemical Processing | Ammonia and methanol offer the largest single decarbonization target with no substitution pathway |
| Iron and Steel | DRI conversion accelerating under border carbon adjustment exposure |
| Transportation Fuel | Fastest growth rate; heavy-duty and maritime segments outpace passenger vehicles |
| Power and Energy Storage | Long-duration storage and turbine blending pilots building toward the 2030s |
| Others | Electronics, float glass, food processing and specialty metallurgy |
Application mix determines contract structure more than any other variable. Captive industrial demand supports long-tenor take-or-pay agreements, while mobility and power applications remain merchant-exposed and therefore harder to finance.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA