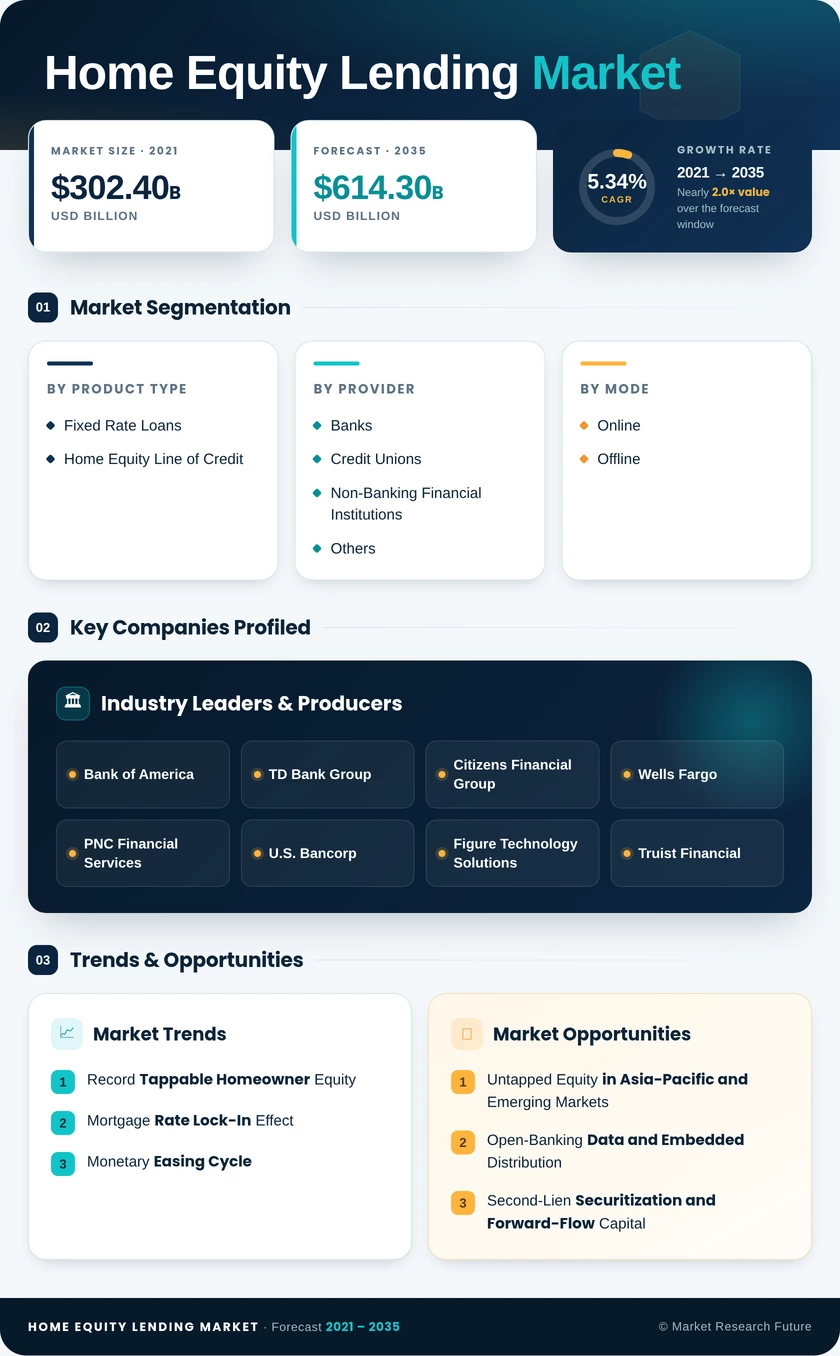
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Product Type | Fixed Rate Loans, Home Equity Line of Credit | Fixed Rate Loans | Home Equity Line of Credit |
| By Provider | Banks, Credit Unions, Non-Banking Financial Institutions, Others | Banks | Credit Unions |
| By Mode | Online, Offline | Online | Offline |
| By Region | North America, South America, Europe, Asia-Pacific, Middle East and Africa | North America | Asia-Pacific |
Market Segmentation Overview
By Product Type
| Sub-Segment | Key Trend |
|---|---|
| Fixed Rate Loans | Payment certainty for single-purpose projects |
| Home Equity Line of Credit | Flexible draws for staged expenses |
Home Equity Line of Credit products lead the Home Equity Lending Market and grow faster than closed-end alternatives because revolving draws match episodic needs such as tuition, phased renovations, solar installations, and medical bills. Interest accrues only on drawn balances, an advantage when rates are elevated. Fixed Rate Loans hold a defensive niche among borrowers who want a locked payment, while hybrid products that fix an initial tranche are blurring the boundary.
By Provider
| Sub-Segment | Key Trend |
|---|---|
| Banks | Deposit-funded pricing and cross-sell |
| Credit Unions | Member pricing and higher CLTV tolerance |
| Non-Banking Financial Institutions | Cloud-native, mobile-first underwriting |
| Others | Brokers, insurers, and specialty lenders |
Banks dominate the Home Equity Lending Market through low-cost deposit funding and servicing retention that deepens relationships across checking, mortgage, and wealth products. Credit Unions compete on price and often accept higher CLTVs for members. Non-Banking Financial Institutions grow fastest, using real-time income verification and automated valuations, then monetizing through securitization or forward-flow sales; FDIC research flags their reliance on warehouse lines as a liquidity risk [11].
By Mode
| Sub-Segment | Key Trend |
|---|---|
| Online | E-signature, remote ID, and digital closing |
| Offline | Notarization, appraisals, and borrower trust |
Offline channels still anchor the Home Equity Lending Market because notarization laws, physical appraisals, and borrower caution keep many closings in branches or title offices. Older homeowners, who hold the most equity, remain largely branch-oriented. Online origination grows fastest as younger borrowers start applications digitally, and leading lenders now run omni-channel journeys in which applicants upload documents by phone but sign at a title office.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA