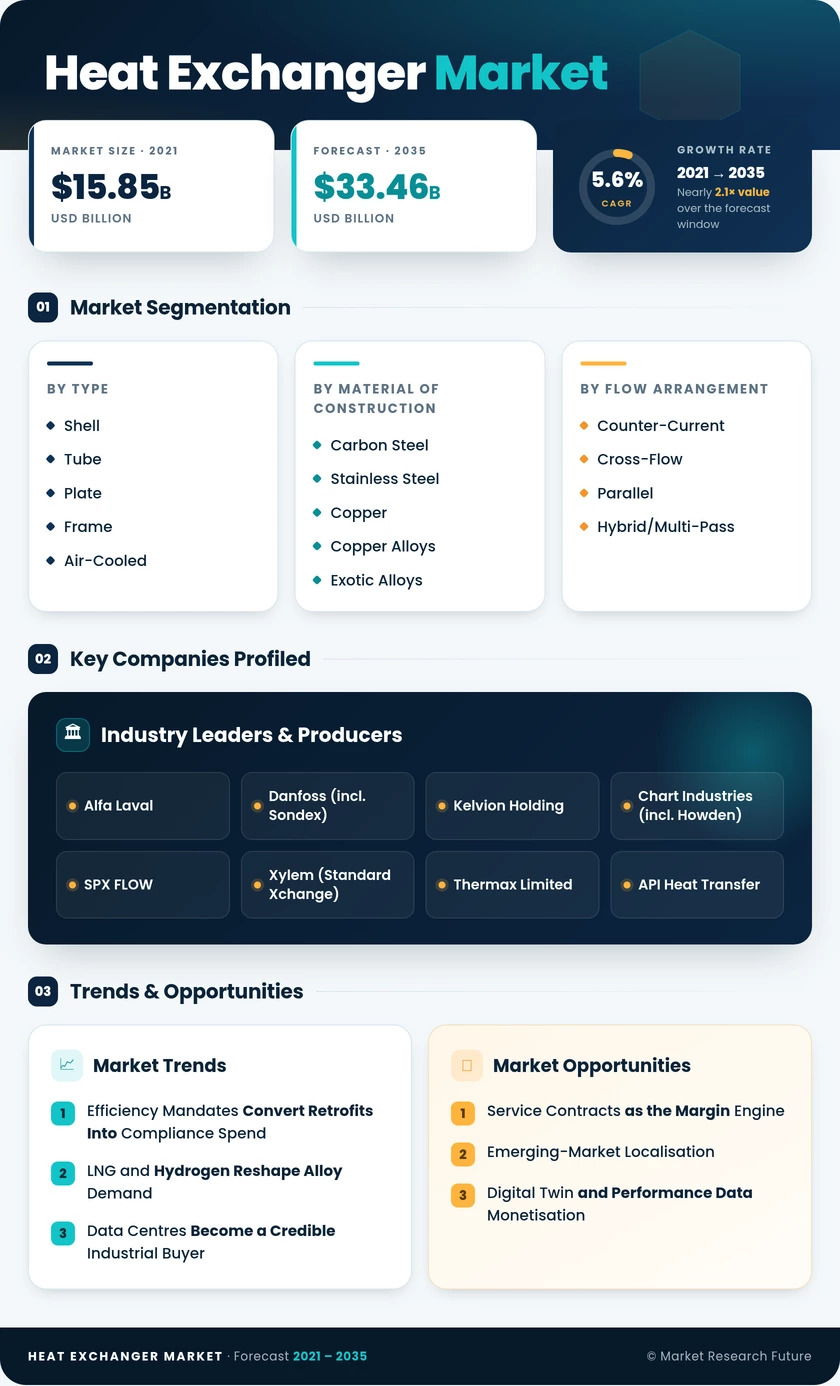
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Type | Shell and Tube; Plate and Frame; Air-Cooled; Brazed and Welded Plate; Others | Shell and Tube | Air-Cooled |
| By Material of Construction | Carbon Steel; Stainless Steel; Copper and Copper Alloys; Exotic Alloys; Others | Carbon Steel | Exotic Alloys |
| By Flow Arrangement | Counter-Current; Cross-Flow; Parallel; Hybrid/Multi-Pass | Counter-Current | Cross-Flow |
| By End-User Industry | Chemical and Petrochemical; Oil and Gas; Power Generation; HVACR; Food and Beverage; Water and Waste-Water; Others | Chemical and Petrochemical | HVACR |
| By Geography | North America; Europe; Asia-Pacific; South America; Middle East & Africa | Europe | Asia-Pacific |
Market Segmentation Overview
By Type
| Sub-Segment | Key Trend |
| Shell and Tube | Retains default status for high-pressure refinery duty; share erodes gradually as duty-specific alternatives claim edge cases |
| Plate and Frame | Standard for hygienic processing and district energy substations; gasket lifecycle costs drive supplier selection |
| Air-Cooled | Fastest expansion as water-scarcity permitting blocks evaporative alternatives in Gulf and South Asian projects |
| Brazed and Welded Plate | Gains in refrigeration, cryogenic, and high-pressure service where gasket elastomers cannot survive |
| Others (Printed-Circuit, Spiral, Coil) | Diffusion-bonded cores unlock 600-bar hydrogen duty and weight-constrained offshore topsides |
Product mix is shifting toward configurations that solve constraint problems rather than efficiency problems. Permitting, footprint, and pressure rating now determine specification more often than pure thermal performance, which is why compact and air-cooled categories grow faster despite higher installed cost.
By Material of Construction
| Sub-Segment | Key Trend |
| Carbon Steel | Largest volume base; margins compressed by regional fabricators competing on standard utility duty |
| Stainless Steel | Core material for food, pharmaceutical, and general chemical corrosion service |
| Copper and Copper Alloys | Concentrated in HVACR coils; substitution pressure from aluminium on cost grounds |
| Exotic Alloys | Highest-growth category; duplex, titanium, and nickel grades command 25–40% premiums in sour and seawater duty |
| Others | Graphite and clad constructions serve concentrated acid and highly specialised corrosive applications |
Metallurgical qualification is becoming a competitive moat. Suppliers holding certified welding procedures for duplex, super-duplex, and nickel-based grades operate in a materially less crowded field than those bidding conventional carbon-steel bundles.
By Flow Arrangement
| Sub-Segment | Key Trend |
| Counter-Current | Preferred wherever thermal effectiveness governs, minimising surface area and steel content per unit duty |
| Cross-Flow | Growth tracks air-cooled adoption, since fan-driven ambient air naturally arranges in cross-flow |
| Parallel | Retained for temperature-limited and viscous fluids where outlet temperature control matters more than effectiveness |
| Hybrid / Multi-Pass | Selected for space-constrained brownfield retrofits and prefabricated skid packages |
Configuration remains the most stable segmentation dimension because thermodynamics, not commercial preference, drives the choice. Movement between sub-segments occurs only as a second-order consequence of shifts in product type.
By End-User Industry
| Sub-Segment | Key Trend |
| Chemical and Petrochemical | Largest buyer; world-scale crackers specify several hundred discrete units per complex |
| Oil and Gas | Cyclical demand keyed to turnaround calendars, LNG final investment decisions, and gas processing build-out |
| Power Generation | Condenser replacement and combined-cycle duty sustain steady replacement volume |
| HVACR | Fastest-growing sector, driven by data-center liquid cooling and district energy networks |
| Food and Beverage | Hygienic design standards and pasteurisation duty support premium plate pricing |
| Water and Waste-Water | Desalination pretreatment and sludge heat recovery expand alongside water-stress investment |
| Others | Pulp, marine, and pharmaceutical applications provide diversified replacement demand |
Buyer concentration cuts both ways. Two sectors deliver more than half of revenue and set specification norms for everyone else, yet the fastest growth now comes from a computing-infrastructure buyer that barely registered five years ago.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA