Heat Exchanger Market Summary
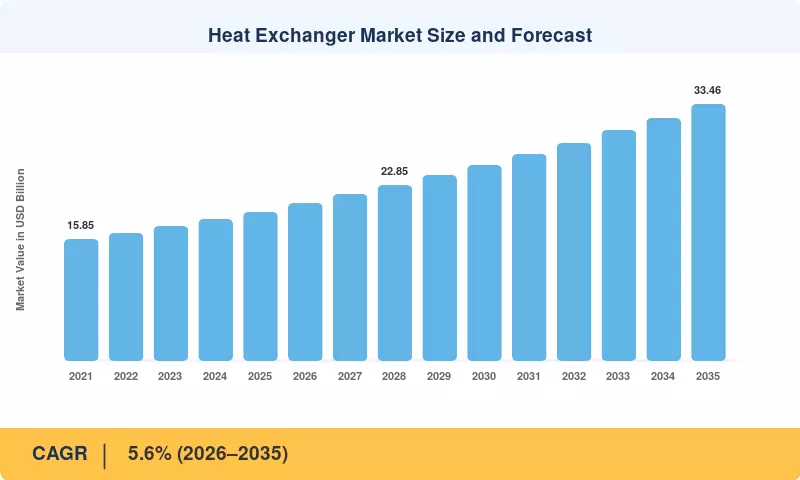
The Heat Exchanger Market was valued at USD 19.40 Billion in 2025 and opens the forecast window at USD 20.49 Billion in 2026, climbing to USD 33.46 Billion by 2035 at a 5.6% CAGR between 2026 and 2035. Two catalysts anchor that trajectory. The European Union's recast Energy Efficiency Directive (EU) 2023/1791 obliges large industrial energy users to run certified energy management systems, which pushes thermal recovery equipment from optional retrofit to compliance line item [4]. Parallel to that, the U.S. Industrial Decarbonization Roadmap earmarks process heat and heat recovery as one of four priority pathways, backed by more than USD 6 billion in demonstration funding [3].
Technology is turning over quickly. Oversized carbon-steel shell bundles designed in the 1980s are being displaced by compact welded plate packs, printed-circuit cores, and prefabricated skid modules that cut delivery cycles by up to 40% [6]. Digital twins now sit behind bid submissions, letting fabricators guarantee duty before steel is cut. Water-scarcity rules are simultaneously shifting new-build refineries toward finned-tube air-cooled banks, a swap that trades footprint for zero make-up water [11]. Hydrogen compression and LNG liquefaction add a third demand layer, with global liquefaction capacity under construction exceeding 170 MTPA [12].
Regionally, Europe holds 30.7% of the Heat Exchanger Market on the strength of district energy retrofits and a dense chemical corridor. Asia-Pacific grows fastest at a 7.0% CAGR, carried by Chinese ethylene expansions and India's PAT efficiency cycles [15][16]. North America ranks second, where LNG export terminals and data-center liquid cooling retrofits dominate order books. Through 2035, the Heat Exchanger Market rewards suppliers who can pair alloy metallurgy with service coverage rather than those competing on plate price alone.
Key Report Takeaways
• By Type
- Shell and Tube designs held 32.9% revenue share in 2025, still the default for high-pressure hydrocarbon duty
- Air-Cooled units are advancing at a 7.0% CAGR through 2035 as water permits tighten
• By Flow Arrangement
- Counter-Current flow arrangements accounted for 60.5% of installed value in 2025
• By End User Industry
- Chemical and Petrochemical operations captured 32.3% of the Heat Exchanger Market in 2025
- Oil and Gas contributed roughly USD 4.19 Billion in 2025 revenue
- HVACR demand is compounding at a 6.4% CAGR, lifted by data-center liquid cooling
• By Region
- Europe led the Heat Exchanger Market with 30.7% share in 2025
- Asia-Pacific posts the fastest regional expansion at a 7.0% CAGR to 2035
- Middle East & Africa generated close to USD 1.28 Billion in 2025
Market Size and Forecast (2021–2035)
Figures below combine bottom-up fabricator shipment tracking, EPC project award databases, customs trade flows for plate and tube assemblies, and audited disclosures from listed thermal equipment suppliers. Historical years are reconciled against installed-base attrition rates; forecast years apply capacity announcements weighted by final-investment-decision probability. All values for the Heat Exchanger Market are expressed in USD Billion at constant 2025 prices.
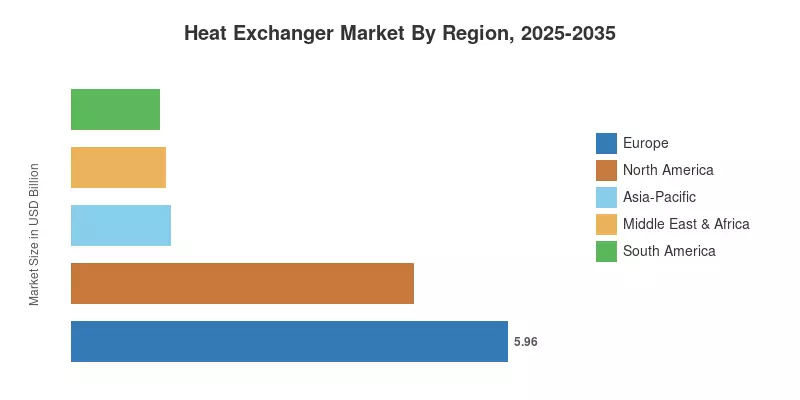



 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


