Healthcare Data Storage Market Summary
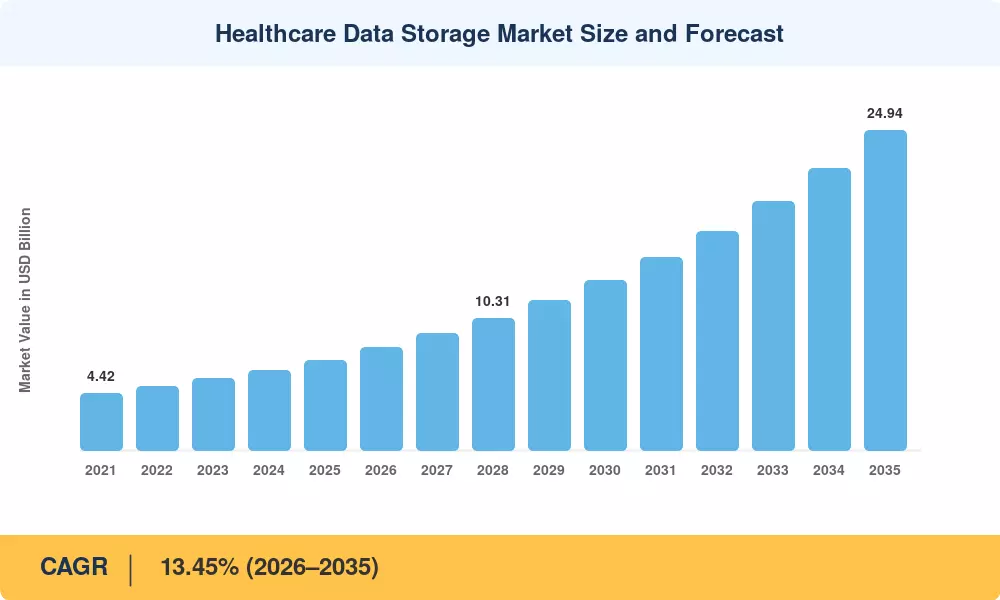
The Healthcare Data Storage Market was valued at USD 7.05 billion in 2025 and is projected to grow to USD 24.94 billion by 2035, expanding at a compound annual growth rate (CAGR) of 13.45% between 2026 and 2035. Market value is expected to reach USD 8.01 billion in 2026 as the first year of the forecast period. This growth is being driven primarily by new interoperability mandates in the United States and Europe, alongside a broader shift from legacy, capital-heavy storage infrastructure toward subscription-based, vendor-neutral archiving.
The CMS Interoperability and Prior Authorization Final Rule (CMS-0057-F) forces payers and providers to exchange records through FHIR APIs at a far higher frequency, significantly increasing the volume and speed of data movement that hospital storage systems must support. In Europe, the European Health Data Space (EHDS) Regulation, in force since March 2025, obliges member states to make electronic health records accessible for both primary and secondary use, creating similar infrastructure pressure across the region.
Hospitals are also retiring storage infrastructure built a decade ago. Departmental PACS silos, tape-only retention, and capital-refreshed SAN arrays are giving way to vendor-neutral archives, object storage tiers, and immutable snapshot copies purchased as subscriptions rather than owned outright. IBM's breach cost research put the average healthcare data breach incident near USD 9.8 million, the highest of any sector for the fourteenth straight year. This single figure has done more to unlock hospital storage budgets than any efficiency argument on its own.
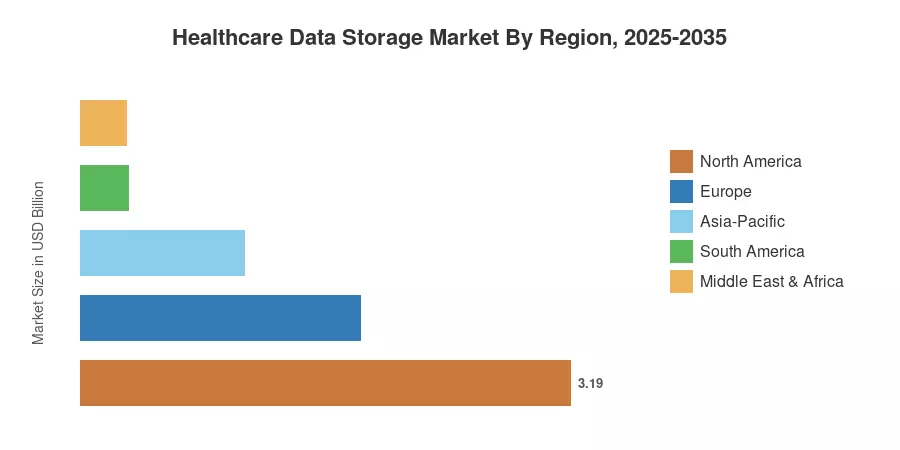
By region, North America holds the largest share of the Healthcare Data Storage Market, at 45.2% of 2025 revenue, supported by TEFCA exchange volumes and a dense installed base of imaging equipment. Asia-Pacific is the fastest-growing region, with a projected CAGR of 15.2%, as India's Ayushman Bharat Digital Mission and China's provincial health cloud programs scale. Europe holds the second-largest position, where data sovereignty rules push sensitive workloads onto in-region infrastructure. Over the next decade, market leadership is expected to belong to whoever makes data retention cheap and retrieval instant.
Key Report Takeaways
• By Deployment Mode
- Cloud deployment commanded 46.9% of Healthcare Data Storage Market revenue in 2025, the largest single deployment mode
• By Architecture
- File storage architecture is projected to expand at a 14.2% CAGR through 2035 as unstructured imaging and pathology volumes outpace block workloads.
• By Storage Medium
- SSD and flash media generated USD 3.04 billion in 2025 revenue across the Healthcare Data Storage Market
• By End user
- Hospitals and clinics accounted for 46.8% of end-user demand in 2025
- Pharmaceutical and biotechnology companies are set to grow at a 14.7% CAGR, the fastest of any end user
• By Application
- PACS and enterprise imaging applications contributed USD 2.92 billion in 2025
• By Region
- North America retained 45.2% revenue share in 2025
- Asia-Pacific is forecast to advance at a 15.2% CAGR through 2035
- Europe generated USD 1.82 billion in 2025, second only to North America
Market Size and Forecast (2021–2035)
Estimates blend vendor storage-segment disclosures, hospital IT capital surveys, national digital health budget filings, and imaging volume statistics, triangulated top-down against installed-base petabyte counts and bottom-up against per-bed spending benchmarks. Historical years are reconciled to reported revenues; forecast years apply demand elasticity to retention-period mandates and imaging study growth.



 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


