Goat Milk Products Market (2026 - 2035)

Goat Milk Products Market Size, Share, Industry Trend & Analysis Research Report Information By Product Type (Fluid Milk, Cheese, Milk Powder, Yogurt, Butter and Ghee, Ice Cream and Desserts), By Packaging (Glass Bottle, Tetra Pack, Stand Up Pouches, Tins), By Distribution Channel (On-Trade, Off-Trade), By Geography (North America, Europe, Asia-Pacific, South America, Middle East & Africa) – Forecast Till 2035
ID: MRFR/FnB/5018-HCR 100 Pages Pradeep Nandi Last Updated: September 15, 2026
Goat Milk Products Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)8.56%
2025 Market SizeUSD 15.81 Billion
2035 Market SizeUSD 33.44 Billion
Key Players
Ausnutria Dairy Corporation Ltd.
Emmi Group
AVH Dairy Trade B.V.
Meyenberg
Delamere Dairy Ltd.
St Helen's Farm
Opportunities
  • Nutrition-Grade Powder for Emerging Retail
  • Sustainable Packaging as a Pricing Lever
  • Beyond the Dairy Aisle

Goat Milk Products Market Summary

The Goat Milk Products Market was valued at USD 15.81 billion in 2025 and opens the forecast horizon at USD 15.96 billion in 2026, climbing to USD 33.44 billion by 2035 at an 8.56% CAGR. Two catalysts anchor that trajectory. First, regulators in Brussels, Beijing and Ottawa have progressively cleared caprine protein for use in infant and follow-on nutrition, unlocking the single highest-margin channel in dairy [Ref 5][Ref 7]. Second, Gulf and Asian sovereign food-security budgets are financing herd expansion at a scale the sector has never seen [Ref 10]. The Goat Milk Products Market is no longer a provenance-driven cottage trade; it is an industrialising category with real capital behind it.

The shift is most apparent in processing. Multi-stage spray-drying towers, membrane filtration lines and inline near-infrared solids monitoring are replacing small-batch pasteurizers and drum dryers - the legacy backbone of caprine dairy. Since 2023, Ausnutria alone has invested over USD 180 million in powder capacity in Heerenveen and Changsha [Ref 14]. Cold chain build-out is just as critical: Tetra Pak says that their aseptic lines for filling goat milk are expanding faster than any other specialty white-milk product in its dairy product range [Ref 13]. The Goat Milk Products Market Competes on Yield and Shelf Life, Not Story Now.


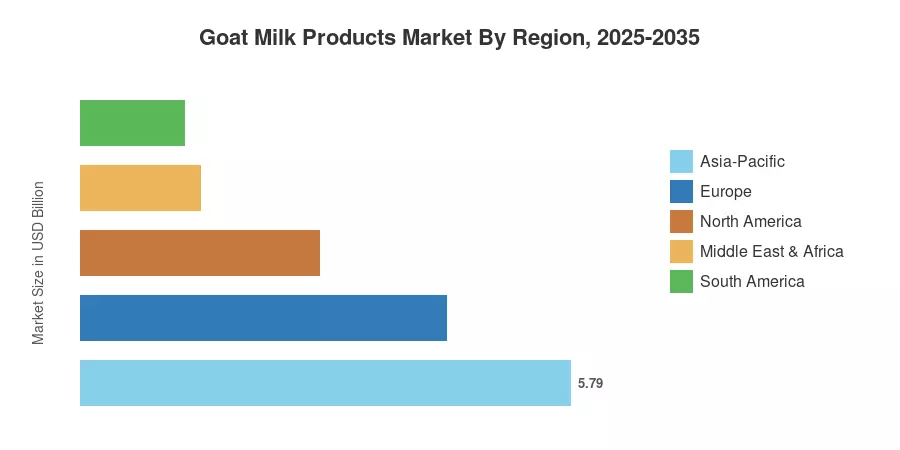
The Asia-Pacific region contributes 36.6% of the 2025 revenue, primarily from formula registrations in China and institutional dairy programs in India. Middle East & Africa is fastest growing at 9.0% CAGR to 2035 as Saudi and Emirati livestock plans come online. Europe is second with USD 4.33 billion, where protected-designation cheeses and a strong retail base support the ability to charge premium prices. In the next 10 years, the Goat Milk Products Market will be determined by the battle for powder throughput and shelf space ownership in growing retail.


Key Report Takeaways

• By Product Type

  • Fluid milk anchored the Goat Milk Products Market with a 43.8% revenue share in 2025, retaining the widest household penetration.
  • Milk powder is the growth engine at an 8.75% CAGR through 2035, driven by nutrition-grade exports.
  • Cheese contributed USD 3.57 billion in 2025 on artisanal and PDO premiumisation.

• By Packaging

  • Tetra pack led packaging with 33.7% of 2025 revenue on ambient distribution economics.
  • Stand-up pouches expand at a 9.2% CAGR as recyclable mono-material formats scale.


• By Geography

  • Asia-Pacific commanded 36.6% of global revenue in 2025
  • Middle East & Africa posts the fastest 9.0% CAGR to 2035
  • North America generated USD 2.83 billion in 2025 on lighter labelling barriers


Market Size and Forecast (2021–2035)

Figures combine farm gate volumes from national statistical agencies, trade flows at the customs level of powder and cheese, retail scanner panels in 31 countries and audited declarations from listed processors. Historical years are reconciled to dairy herd censuses; prospective years employ channel-weighted demand modeling. The Goat Milk Products Market is represented in USD billion at current pricing. The Goat Milk Products Market is segmented as follows.
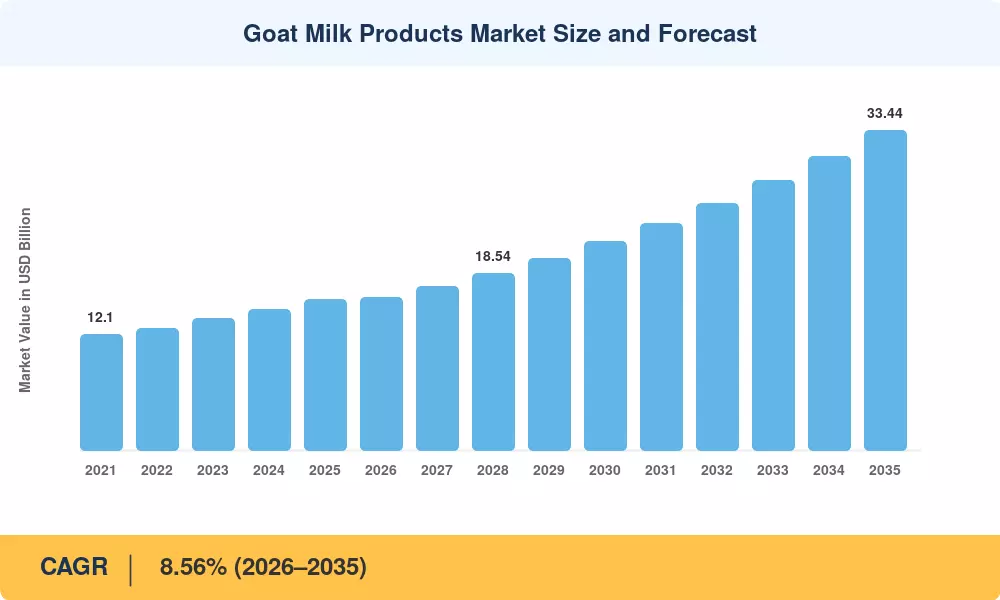
Goat Milk Products Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Regulatory clearance of caprine protein in infant nutrition +1.6 Global Medium-term (2–4 yr)
Spray-drying and membrane capacity investment +1.3 Asia-Pacific, Europe Medium-term (2–4 yr)
Rising lactose-intolerance and gut-health awareness +1.2 Global Long-term (≥4 yr)
E-commerce and cold-chain expansion +1.0 Asia-Pacific, MEA Short-term (≤2 yr)
Gulf food-security and livestock programmes +0.8 Middle East & Africa Long-term (≥4 yr)
Artisanal and PDO cheese premiumisation +0.7 Europe, North America Short-term (≤2 yr)
Smart-farming subsidies for smallholder herds +0.6 Asia-Pacific, South America Long-term (≥4 yr)


Nutrition Regulation Unlocks the Premium Tier

EFSA's 2024 opinion confirming caprine protein as a suitable nitrogen source for infant and follow-on formula removed the last scientific objection in the EU, and China's SAMR catalogue has since admitted more than 20 caprine formula SKUs under its revised registration regime [Ref 5][Ref 7]. That matters commercially because formula carries gross margins roughly three times that of fluid white milk. Chinese caprine formula retail value grew an estimated 11% in 2025 against 2% for bovine equivalents [Ref 11].

Capital Flows Into Powder Throughput

Processors have learned that seasonality is survivable only if surplus spring milk can be dried; between 2023 and 2025, disclosed capital commitments to caprine drying and evaporation assets exceeded USD 400 million globally, concentrated in the Netherlands, New Zealand and Hunan province [Ref 14][Ref 9]. Yield economics improved alongside: modern multi-stage towers recover solids at rates 6–8 percentage points above the drum systems they replace.

Digestive Health Reframes the Category

Roughly 68% of the global adult population carries reduced lactase persistence, and caprine milk's smaller fat globules and lower αS1-casein fraction make it a practical bridge product [Ref 12]. Retailers have responded by moving it out of specialty aisles. In the United States, mainstream grocery distribution for caprine fluid milk widened by an estimated 14% in door count between 2023 and 2025 [Ref 4].

Sovereign Food-Security Spending

Saudi Arabia's National Livestock Development Programme allocated over SAR 1.1 billion to small-ruminant productivity between 2023 and 2026, targeting a measurable lift in domestic dairy self-sufficiency [Ref 10]. Similar frameworks in the UAE and Egypt are pulling processing equipment imports upward, which is why the Goat Milk Products Market grows faster in this region than anywhere else.


Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Seasonal lactation curves and kid mortality risk −1.1 Global Long-term (≥4 yr)
Fragmented smallholder farm structure −0.9 Asia-Pacific, South America Long-term (≥4 yr)
Price premium versus bovine dairy −0.8 Global Short-term (≤2 yr)
Plant-based beverage substitution −0.6 North America, Europe Medium-term (2–4 yr)
Export certification and residue-testing complexity −0.5 MEA, Asia-Pacific Medium-term (2–4 yr)


Supply Does Not Arrive Evenly

Does are seasonal breeders. Without photoperiod manipulation or staggered kidding, farm-gate supply in temperate zones swings by a factor of three between peak and trough, and kid mortality in unmanaged systems still runs 12–18% in the first month [Ref 19]. Processors without drying assets are forced to dump or discount surplus. That volatility is the structural reason capacity investment has become the industry's dominant competitive lever.

Fragmentation Blocks Consistency

IFCN data indicate the median caprine dairy holding worldwide runs under 40 head, versus several hundred for bovine operations [Ref 25]. Small herds mean inconsistent somatic cell counts, patchy cold-chain compliance and negligible bargaining power. Collection costs per litre in fragmented Indian and Brazilian catchments run an estimated 20–30% above consolidated European equivalents.

The Premium Is Real, and It Bites

Shelf pricing typically sits 55–90% above comparable bovine SKUs [Ref 11]. In cost-sensitive baskets, that premium collapses trial rates the moment household budgets tighten — a dynamic visible in 2022, when volume growth in the category slowed sharply while value held up on price alone.


Goat Milk Products Market Opportunities

Nutrition-Grade Powder for Emerging Retail

Southeast Asia and the Gulf import nearly all their caprine nutrition powder. Local blending and canning under licence would cut landed cost materially and shorten replenishment cycles, particularly for infant formula applications now clearing regional registration [Ref 6]. Early movers building blending capacity in Malaysia and the UAE gain first claim on registration slots.

Sustainable Packaging as a Pricing Lever

Recyclable mono-material stand-up pouches and low-carbon foil lids reduce packaging weight by up to 40% versus rigid formats while satisfying EU packaging directives [Ref 24]. In a category where the shopper already pays a premium, credible sustainability claims defend that premium rather than erode it.

Beyond the Dairy Aisle

Caprine solids move readily into adjacent categories with far higher value density. Goat milk skincare, protein powders and senior clinical nutrition all draw on the same upstream stream, letting processors monetise fractions that would otherwise be commoditised [Ref 12]. This is the clearest route to margin expansion in mature Western retail.

Data-Led Farm Services and Traceability Monetisation

Herd sensors, automated parlour records and blockchain provenance logs generate assets processors can sell twice — once as milk, once as verified origin data to brands and regulators. Chinese formula importers already pay premiums for batch-level traceability [Ref 7]. Subscription farm-management platforms represent a genuine new revenue line for the Goat Milk Products Market.

Latin American Retail Whitespace

Brazil and Argentina together account for under 8% of global revenue despite substantial herd bases [Ref 1]. Modernising collection and introducing ambient formats would convert existing production into branded retail value inside the Goat Milk Products Market.


Goat Milk Products Market Future Outlook

Precision Herd Management Goes Mainstream

Sensor-based oestrus detection, automated parlour identification and predictive kidding analytics are migrating from bovine operations into caprine herds. FAO modelling suggests precision tools can lift small-ruminant productivity by 15–20% within three lactation cycles [Ref 1]. For a category constrained by seasonality, that is transformative rather than incremental.

Powder Economics Determine Winners

Whoever controls drying throughput controls the arbitrage between surplus spring milk and year-round demand. Rabobank expects specialty powder capacity utilisation to tighten through 2029 as new nutrition registrations outpace commissioning schedules [Ref 11]. Processors without their own towers will find toll-drying costs rising against them.

Sustainability Reporting Becomes a Trade Condition

CSRD-aligned disclosure and the EU packaging directive are pushing carbon and recyclability data into commercial negotiation, not just marketing decks [Ref 24]. Buyers in the Goat Milk Products Market increasingly request per-litre emissions figures at tender stage, and caprine systems' lower absolute footprint per animal is a defensible advantage — provided it is measured.

Channel Shift Reshapes Brand Economics

OECD-FAO projections put emerging-market dairy consumption growth at roughly double the OECD rate through 2034 [Ref 2]. Most of that incremental demand will be served through mobile commerce and quick-commerce platforms rather than traditional grocery. Brands built for shelf will need to rebuild for the feed, which reshuffles competitive advantage across the Goat Milk Products Market.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America USD 2.83 billion Mainstream retail distribution, clinical nutrition
Europe 27.4% share PDO cheese, sustainable packaging, export powder
Asia-Pacific 36.6% share Formula registration, spray-drying, e-commerce
South America 7.8% share Collection modernisation, ambient formats
Middle East & Africa 9.0% CAGR Sovereign herd programmes, import substitution
Total USD 15.81 billion —

Regional performance across the Goat Milk Products Market splits cleanly between volume-rich Asia-Pacific, value-rich Europe, and fast-compounding Middle East & Africa.


North America

Country Metric (2025) Key Driver
US 62.5% share of region Mainstream grocery distribution gains
Canada USD 0.48 billion Compositional standards clarity for formula
Mexico 8.2% CAGR Modern-trade expansion in urban centres


Lighter labelling requirements have let American brands move caprine fluid milk and cheese out of specialty channels and into national grocery banners, a shift USDA NASS herd data corroborates through steady dairy-goat inventory growth [Ref 19]. Health Canada's 2024 clarification of compositional requirements for infant formula gave importers the regulatory certainty they had been waiting on [Ref 22]. FDA GRAS notifications covering caprine-derived ingredients have further widened formulation latitude for clinical and sports nutrition brands [Ref 21].

Europe

Country Metric (2025) Key Driver
Germany 21.4% share of region Organic retail penetration
UK USD 0.61 billion Established fluid and cheese distribution
France 17.8% share of region PDO cheese heritage and export
Italy 7.4% CAGR Artisanal cheese premiumisation
Spain USD 0.43 billion Large herd base, export orientation
Nordic Countries 6.9% share of region Sustainability-led packaging adoption
Russia 5.8% CAGR Domestic substitution policy
Rest of Europe USD 0.53 billion Netherlands powder export hub


Europe converts modest volume into outsized value. DG AGRI's Milk Market Observatory shows caprine deliveries broadly flat across the bloc. At the same time, unit values climbed, a signal that PDO designations and artisanal positioning are doing the heavy lifting [Ref 3]. The Netherlands functions as the continent's export engine, drying surplus from Dutch, Belgian and French catchments for shipment into Asia [Ref 9]. Eurostat herd figures nonetheless show contraction in several southern member states, tightening raw supply and reinforcing the price floor [Ref 18].

Asia-Pacific

Country Metric (2025) Key Driver
China 34.8% share of region Formula registration and e-commerce
India USD 1.42 billion Large herd base, institutional dairy schemes
Japan 6.4% CAGR Clinical and senior nutrition demand
South Korea 7.1% share of region Premium infant nutrition imports
ASEAN 9.6% CAGR Modern trade and cold-chain build-out
Rest of Asia-Pacific USD 0.51 billion Australia and New Zealand export supply


China remains the pivot. SAMR's registration catalogue determines which brands may sell formula domestically, and each approval is effectively a licence to compete in the highest-margin slice of the Goat Milk Products Market [Ref 7]. India's scale is different in character: FSSAI's tightened milk and milk-product regulations are formalising a vast informal trade, converting unrecorded volume into measurable retail value [Ref 8]. Australian and New Zealand exporters supply much of the region's powder deficit [Ref 9].

South America

Country Metric (2025) Key Driver
Brazil 46.3% share of region Northeast herd base, retail modernisation
Argentina USD 0.31 billion Cheese production and regional export
Rest of South America 7.6% CAGR Peru and Colombia collection investment


Brazil's northeastern states hold one of the largest caprine herds outside Asia, yet the majority of that milk never reaches branded retail [Ref 1]. Federal and state collection-infrastructure programmes are slowly changing that. Argentina's contribution skews toward cheese, where existing artisanal capacity and Mercosur access give producers a route into neighbouring markets without heavy capital outlay [Ref 17].

Middle East & Africa

Country Metric (2025) Key Driver
Saudi Arabia 31.2% share of region Vision 2030 livestock investment
UAE USD 0.29 billion Premium retail and expatriate demand
South Africa 8.7% CAGR Formal retail chain expansion
Egypt 13.5% share of region Large herd base, import substitution
Rest of MEA USD 0.34 billion Gulf import demand


The Saudi National Livestock Development Programme is the single most consequential policy intervention in the region, pairing capital grants for productivity upgrades with import-substitution targets [Ref 10]. Emirati demand skews premium and import-dependent, which sustains high unit values. Across the broader region, World Bank food-security monitoring flags dairy self-sufficiency as a standing policy priority — a tailwind unlikely to reverse this decade [Ref 17].


Goat Milk Products Market By Region, 2025-2035

Goat Milk Products Market Segmentation

By Product Type

Product mix within the Goat Milk Products Market remains anchored by fluid milk, but value is migrating steadily toward dried and cultured formats.

Segment Metric (2025) Primary Demand Driver
Fluid Milk 43.8% share Household penetration and digestibility positioning
Cheese USD 3.57 billion Artisanal and PDO premiumisation
Milk Powder 8.75% CAGR Nutrition-grade export demand
Yogurt USD 1.49 billion Functional and probiotic formulation
Butter and Ghee 5.6% share South Asian culinary and clinical use
Ice Cream and Desserts 7.9% CAGR Premium foodservice innovation


Fluid milk retains scale because it is the entry point — most households meet the category through a chilled bottle before they ever try anything else. Milk powder is where the profit pool is shifting. Export-grade drying converts a seasonal, perishable stream into a tradeable commodity with an 18-month shelf life, and it is the only format that scales into infant nutrition [Ref 14]. Cheese occupies the middle ground: high value, geographically concentrated, and defended by designation-of-origin rules that new entrants cannot replicate [Ref 3].

By Packaging

Packaging choices in the Goat Milk Products Market now carry both cost and brand consequences.

Segment Metric (2025) Primary Demand Driver
Tetra Pack 33.7% share Ambient distribution economics
Glass Bottle USD 4.49 billion Premium and artisanal positioning
Tins 22.6% share Powder and formula protection
Stand Up Pouches 9.2% CAGR Recyclable mono-material adoption


Aseptic cartons dominate because ambient logistics slash the cost of reaching secondary cities in Asia and the Gulf [Ref 13]. Pouches grow fastest for a different reason: they weigh less, ship denser and satisfy recyclability targets that retailers now write into supplier agreements [Ref 24].

By Distribution Channel

Channel structure across the Goat Milk Products Market has tilted decisively toward retail and away from foodservice.

Segment Metric (2025) Primary Demand Driver
Off-Trade 61.2% share Supermarket listings and e-commerce
On-Trade 6.9% CAGR Specialty cafés and premium foodservice


Off-trade dominance reflects the category's household-consumption logic, amplified by e-commerce reach into markets where physical specialty retail never existed [Ref 11]. On-trade grows more slowly but punches above its weight in brand-building, since café and restaurant placement drives trial that later converts to retail repeat purchase.


Competitive Benchmarking

Poor concentration. Estimated HHI is close to 520, with the five largest suppliers capturing around 30% of worldwide revenue – a structure more suggestive of fragmented upstream supply than strategic intent. Scale is only possible if processors have vertically integrated collection with drying capacity. The extended tail of regional cheesemakers and single-origin products below that tier competes on provenance, not cost. Consolidation pressure builds in powder export; artisanal cheese still a structurally viable space for smaller businesses.

Company Est. Revenue Share Range Key Offerings for Goat Milk Products Market Strategic Positioning
Ausnutria Dairy Corporation Ltd. ~9–12% Infant formula, nutrition powder, fluid Vertically integrated Dutch–Chinese powder leader
Emmi Group ~6–8% Cheese, fluid milk, specialty dairy Premium European portfolio with US footprint
AVH Dairy Trade B.V. ~4–6% Bulk and nutrition-grade powder Export-focused ingredient supplier
Meyenberg (Carrera Foods) ~3–5% Fluid milk, powder, cheese, butter Dominant US retail brand
Delamere Dairy Ltd. ~2–4% Fluid, cheese, butter, powder UK multi-format specialist
St Helen's Farm ~2–4% Fluid milk, yogurt, cheese Farm-branded UK retail leader
Bubs Australia Ltd. ~2–3% Infant and toddler nutrition Registration-led Asian export strategy
Holle baby food AG ~2–3% Organic infant formula Certified-organic European positioning
Granarolo S.p.A. ~1–3% Cheese, fluid milk Italian PDO cheese heritage
Sanyuan Foods Co. Ltd. ~1–3% Fluid milk, formula Domestic Chinese distribution scale
Hay Dairies Pte Ltd ~1–2% Fresh fluid milk Singapore-based fresh-supply niche
Australian Dairy Park (CapriLac) ~1–2% Fluid, powder, yogurt Oceania supply into Asian retail


Recent News & Developments

  • EFSA (March 2024): Published a favourable scientific opinion on caprine protein in infant and follow-on formula, removing the final regulatory obstacle to EU-wide formulation and accelerating investment across the Goat Milk Products Market.
  • Ausnutria (July 2024): Commissioned expanded spray-drying capacity at its Heerenveen complex, adding nutrition-grade powder output aimed at Asian registration channels.
  • Health Canada (September 2024): Clarified compositional requirements for caprine-based infant formula, giving importers a defined approval pathway.
  • Bubs Australia (February 2025): Reported double-digit growth in caprine toddler nutrition revenue and signalled expansion into additional Gulf markets.
  • Saudi MEWA (May 2025): Expanded the National Livestock Development Programme with new productivity grants targeting small-ruminant dairy operations.
  • Emmi Group (August 2025): Extended its specialty cheese portfolio through targeted North American distribution agreements.
  • China SAMR (October 2025): Admitted a further tranche of caprine formula SKUs to the national registration catalogue, widening brand access to domestic retail.


Goat Milk Products Market Report Scope

Parameter Detail
Market Scope Global caprine dairy across product type, packaging, distribution channel and geography
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 8.56% (2026–2035)
Market Size Checkpoints USD 15.81 billion (2025); USD 15.96 billion (2026); USD 33.44 billion (2035)
Fastest Growing Segments Milk Powder (product type); Stand Up Pouches (packaging); Off-Trade (channel); Middle East & Africa (region)
Companies Profiled 12 leading suppliers including Ausnutria, Emmi, AVH Dairy Trade, Meyenberg, Delamere Dairy, St Helen's Farm, Bubs Australia, Holle, Granarolo, Sanyuan, Hay Dairies, Australian Dairy Park
Valuation Currency USD billion, current prices

FAQs

What due diligence should investors run before backing a Goat Milk Products Market processor?
Verify contracted raw milk volume against installed drying capacity, and confirm registration status in destination markets. Unregistered nutrition assets carry stranded-capital risk [Ref 7].
How should procurement teams structure supply contracts in a seasonal category?
Index pricing to solids content rather than volume, and negotiate winter allocation separately from spring surplus. Fixed annual volumes at flat pricing consistently disadvantage the buyer [Ref 11].
What certification hurdles most often delay Goat Milk Products Market export shipments?
Residue-testing panels and Codex-aligned compositional documentation cause the majority of delays. Building destination-country lab partnerships before first shipment shortens clearance materially [Ref 6].
Is toll-drying a viable alternative to owning spray-drying assets?
It works below roughly 8,000 tonnes annual throughput. Above that, toll fees and scheduling risk usually justify owned capacity [Ref 14].
Which competitive moat proves most durable in the Goat Milk Products Market?
Designation-of-origin cheese rights, because they cannot be replicated by capital alone. Powder capacity advantages erode as rivals commission comparable towers [Ref 3].
How do caprine and bovine operations differ on integration complexity?
Parlour equipment, cooling thresholds and somatic-cell benchmarks all require recalibration. Retrofitting bovine plants typically costs less than greenfield but constrains achievable throughput [Ref 25].
What emerging application deserves closest commercial attention?
Senior and clinical nutrition. Ageing populations in Japan and Western Europe are driving hospital and aged-care formulation demand faster than retail channels [Ref 2].    
Author
Author Author Profile Pradeep Nandi LinkedIn Senior Research Analyst
I have a bachelor's degree in mechanical engineering and an MBA. I have more than two years of expertise in the retail, food, and beverage, chemical, and material industries, and hence have developed a sound cross-domain expertise. A firm believer in lifelong learning and sharing of knowledge. Having a proclivity for hatching ideas and trying to absorb as much information as possible in a short amount of time. Introducing corporates to the data and insight, which enables them to move from probability to possibility, has been my key areas of interest. 

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, dairy industry publications, agricultural statistics, and authoritative food & beverage organizations. Key sources included the US Food & Drug Administration (FDA), European Food Safety Authority (EFSA), Codex Alimentarius Commission (FAO/WHO), Food Standards Australia New Zealand (FSANZ), International Dairy Federation (IDF), Agricultural and Processed Food Products Export Development Authority (APEDA), National Agricultural Statistics Service (NASS/USDA), European Dairy Association (EDA), Dairy Australia, New Zealand Ministry for Primary Industries (MPI), China National Health Commission, Food and Agriculture Organization (FAO) Statistical Database, USDA Foreign Agricultural Service (FAS) Global Agricultural Information Network, Eurostat Agricultural Database, and national dairy council reports from key markets. These sources were used to collect livestock statistics, dairy production volumes, regulatory approval data, import-export trade flows, consumer consumption patterns, and market landscape analysis for fermented goat milk, powdered goat milk, concentrated products, and fat-rich formulations.


Primary Research

As part of the initial research process, stakeholders from both the supply and demand sides were interviewed to get both qualitative and quantitative information. CEOs, VPs of Operations, directors of herd management, and marketing directors from goat dairy processors, farm cooperatives, and organic dairy manufacturers were on the supply side. On the demand side, there were procurement managers from supermarket companies, buyers from health food stores, category managers for e-commerce platforms, and distribution leads from specialty grocery stores, convenience store networks, and direct-to-consumer subscription services. Primary research proved market segmentation, made sure that products would be coming out on time, and gave information on new formulations, pricing strategies, shelf-space dynamics, and the requirements for organic certification.

Primary Respondent Breakdown:

By Designation: C-level Primaries (42%), Director Level (25%), Others (33%)

By Region: North America (40%), Europe (30%), Asia-Pacific (22%), Rest of World (8%)


Market Size Estimation

Global market valuation was derived through revenue mapping and production volume analysis. The methodology included:

Identification of 50+ key manufacturers and dairy cooperatives across North America, Europe, Asia-Pacific, and Oceania

Product mapping across fermented (yogurt/kefir), powdered (infant formula/cooking), concentrated, and fat-rich categories

Analysis of reported and modeled annual revenues specific to goat milk product portfolios

Coverage of processors representing 75-80% of global market share in 2024

Extrapolation using bottom-up (production volume × ASP by country/region) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations for bottles, cartons, cans, and tubs packaging formats across store-based and non-store distribution channels

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















