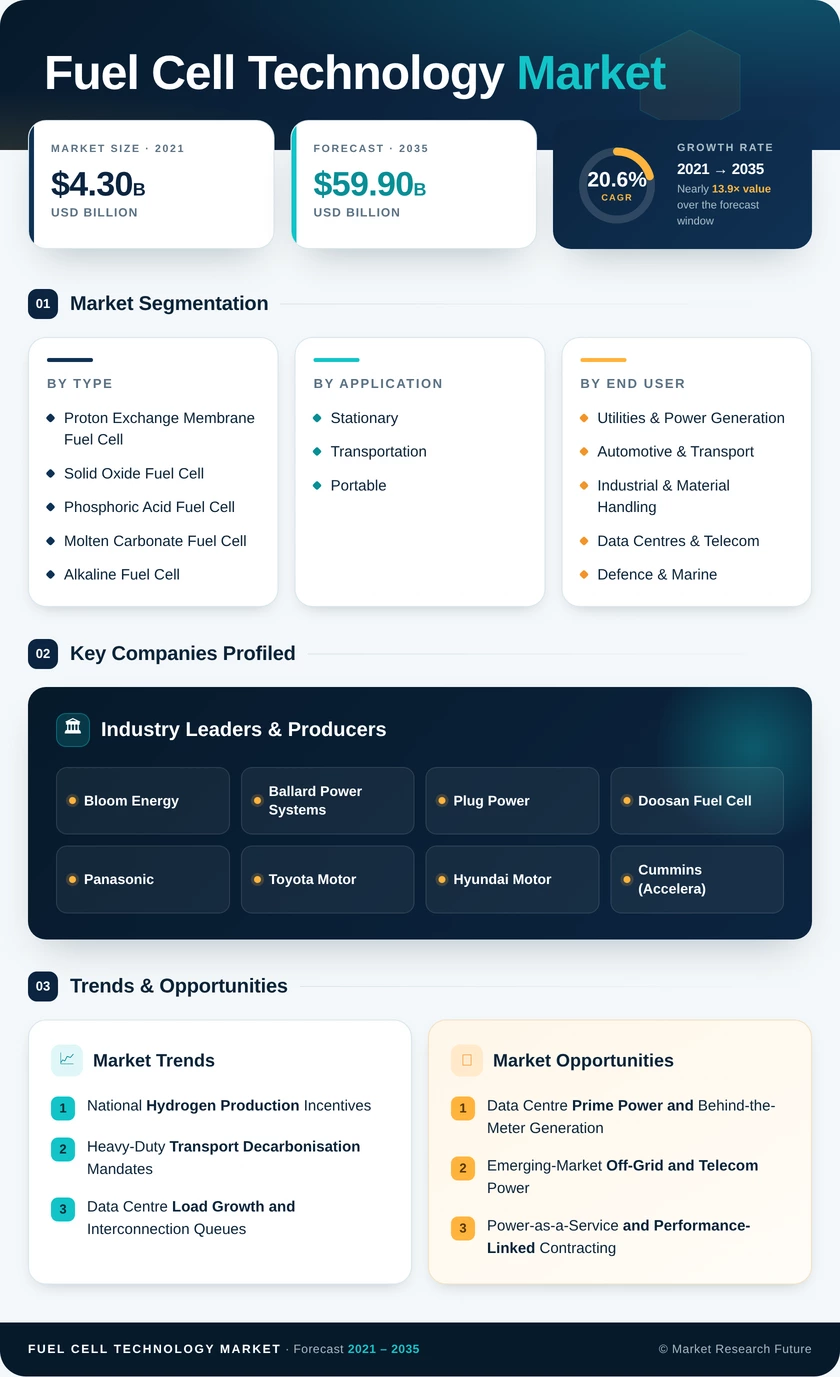
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Type | Proton Exchange Membrane Fuel Cell; Solid Oxide Fuel Cell; Phosphoric Acid Fuel Cell; Molten Carbonate Fuel Cell; Alkaline Fuel Cell; Direct Methanol Fuel Cell | Proton Exchange Membrane Fuel Cell (61.5% share) | Solid Oxide Fuel Cell (23.4% CAGR) |
| By Application | Stationary; Transportation; Portable | Stationary (48.0% share) | Transportation (24.9% CAGR) |
| By End User | Utilities & Power Generation; Automotive & Transport; Industrial & Material Handling; Data Centres & Telecom; Defence & Marine | Utilities & Power Generation (31.8% share) | Automotive & Transport (26.1% CAGR) |
| By Power Output | Under 200 kW; 200 kW – 1 MW; Above 1 MW | Under 200 kW (42.6% share) | 200 kW – 1 MW (23.9% CAGR) |
Market Segmentation Overview
By Type
| Sub-Segment | Key Trend |
| Proton Exchange Membrane Fuel Cell | Platinum loading reduction and heavy-duty module standardisation |
| Solid Oxide Fuel Cell | Fuel-flexible architectures targeting ammonia and natural gas feedstocks |
| Phosphoric Acid Fuel Cell | Replacement orders within legacy district energy estates |
| Molten Carbonate Fuel Cell | Integration with post-combustion carbon capture at industrial sites |
| Alkaline Fuel Cell | Non-precious-metal catalyst development for cost-sensitive duty |
| Direct Methanol Fuel Cell | Miniaturisation for defence and remote instrumentation loads |
Proton exchange membrane systems lead this dimension with 61.5% of 2025 revenue because their sub-minute start-up and low operating temperature suit forklift fleets and commercial vehicle drivetrains, where duty cycles run constantly. Solid oxide is the fastest-growing sub-segment at a 23.4% CAGR, winning stationary tenders on electrical efficiency above 55% and the ability to run on carriers other than pure hydrogen. Molten carbonate holds a narrow but defensible position where regulators require capture-ready generation, while phosphoric acid volumes now depend on installed-base replacement rather than new capacity.
By Application
| Sub-Segment | Key Trend |
| Stationary | Behind-the-meter prime power displacing backup-only configurations |
| Transportation | Depot-based refuelling models replacing public station dependence |
| Portable | Energy-density-driven procurement in defence and field monitoring |
Stationary applications hold 48.0% of revenue because continuous operation spreads capital cost across far more annual operating hours than mobility duty allows, and because grid interconnection delay has turned on-site generation into a scarcity purchase. Transportation grows fastest at 24.9%, propelled by heavy-duty emissions rules that leave few compliant alternatives for long-range freight. Portable remains the smallest sub-segment by revenue yet carries the strongest margins, since defence buyers value logistics simplification over cost per watt.
By End User
| Sub-Segment | Key Trend |
| Utilities & Power Generation | Obligated procurement under national portfolio standards |
| Automotive & Transport | Lease and availability contracting replacing outright purchase. |
| Industrial & Material Handling | Subsidy-independent economics in multi-shift warehousing |
| Data Centres & Telecom | Long-tenor availability agreements for prime power |
| Defence & Marine | Compliance-driven auxiliary power retrofit demand |
Utilities and power generation dominate with a 31.8% share because Korean and Japanese procurement obligations guarantee offtake regardless of merchant power prices, giving vendors bankable revenue visibility. Automotive and transport buyers grow fastest at a 26.1% CAGR as fleet mandates convert into firm multi-year orders. Industrial and material handling is the most commercially mature category and the only one operating profitably without policy support, which makes it the base load of vendor revenue. At the same time, data centre demand supplies the volatility.
By Power Output
| Sub-Segment | Key Trend |
| Under 200 kW | High-volume shipments from forklift and residential CHP platforms |
| 200 kW – 1 MW | Commercial building and edge facility adoption at modular scale |
| Above 1 MW | Concentrated large-contract awards for campus and utility duty |
Units under 200 kW hold 42.6% of revenue on shipment volume alone, since warehouse fleets and the Japanese residential installed base ship in quantities no other class approaches. The 200 kW to 1 MW band grows fastest at 23.9% because commercial buildings and edge data facilities can adopt modular on-site generation without utility-scale interconnection complexity or project finance. Above 1 MW, a handful of campus and district contracts drive the entire figure, producing lumpy year-to-year revenue that nonetheless anchors vendor backlog quality.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA