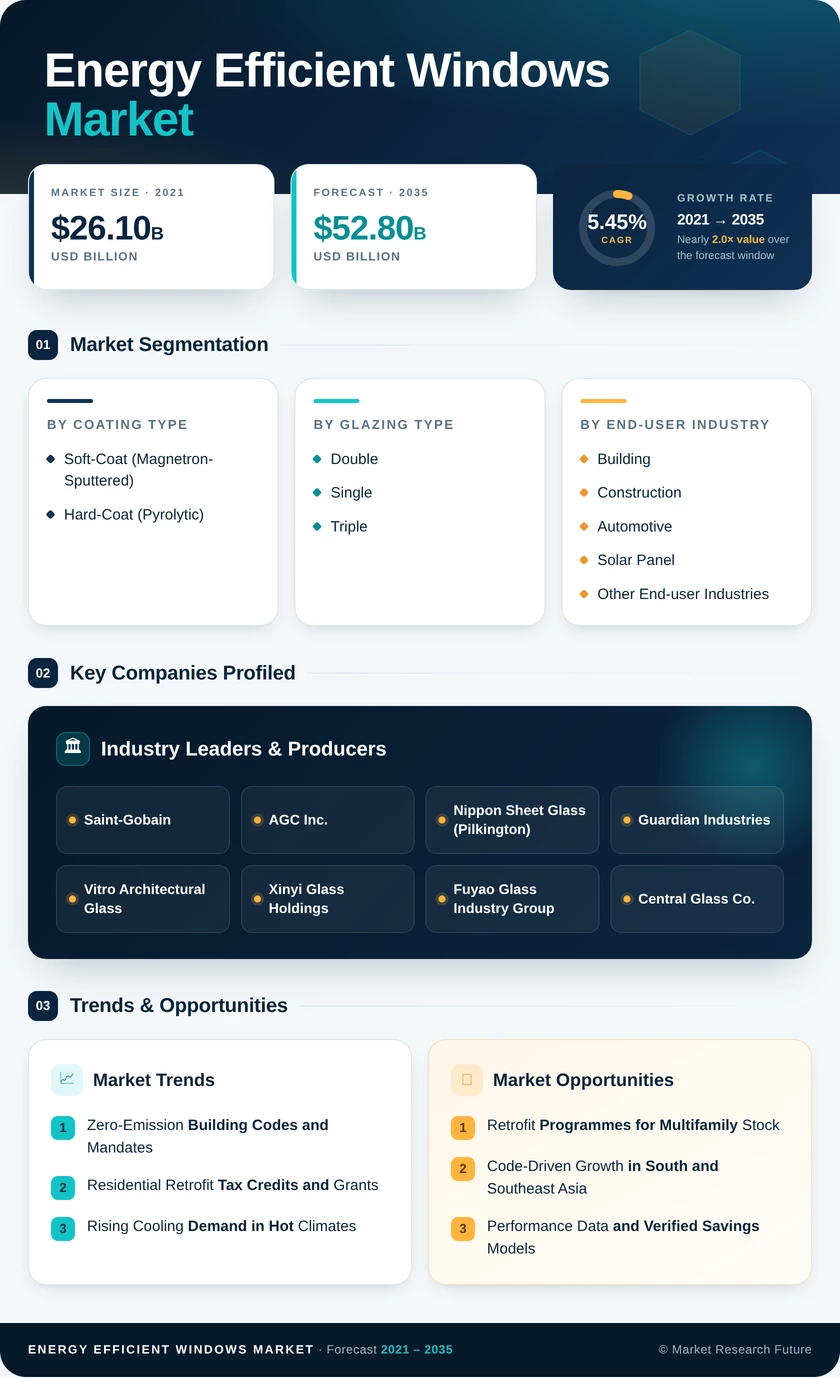
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|
| By Coating Type | Soft-Coat (Magnetron-Sputtered); Hard-Coat (Pyrolytic) | Soft-Coat (Magnetron-Sputtered) (58.5% share) | Soft-Coat (Magnetron-Sputtered) (outpaces Hard-Coat) |
| By Glazing Type | Double; Single; Triple | Double (44.2% share) | Triple (5.8% CAGR) |
| By End-user Industry | Building and Construction; Automotive; Solar Panel; Other End-user Industries | Building and Construction (63.8% share) | Solar Panel (6.9% CAGR) |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | Europe (36.8% share) | Asia-Pacific (6.62% CAGR) |
Market Segmentation Overview
| Sub-Segment | Key Trend |
|---|
| Soft-Coat (Magnetron-Sputtered) | Multi-silver stacks moving into mid-market residential as deposition costs fall. |
| Hard-Coat (Pyrolytic) | Retained in humid climates and tempering-intensive safety applications |
Soft-Coat (Magnetron-Sputtered) leads and also grows faster, because only sputtered multi-silver layers reach the very low emissivity that zero-emission codes demand. Hard-Coat (Pyrolytic) keeps its position where durability, long-distance handling, and on-site tempering matter more than peak performance, mainly in mass housing across Southeast Asia and Africa.
| Sub-Segment | Key Trend |
|---|
| Double | Standard compliance format in new residential and commercial construction |
| Single | Gradual substitution by laminated coated products in regulated markets |
| Triple | Rapid uptake in cold-climate retrofits and passive-house projects |
Double units lead because they meet most codes within standard frame depths at moderate cost. Triple units grow fastest as European retrofit finance, U.S. state performance standards, and Japanese cold-region rules reward U-values below 1.0 W/m²K. Single units persist in greenhouses, partitions, and heritage settings but lose ground as carbon rules tighten.
| Sub-Segment | Key Trend |
|---|
| Building and Construction | Zero-emission mandates and multifamily retrofits sustain volume |
| Automotive | Infrared-reflective glazing protects electric vehicle range. |
| Solar Panel | Anti-reflective, textured cover glass lifts module efficiency |
| Other End-user Industries | Cold-chain logistics and airport upgrades add incremental demand. |
Building and Construction leads by a wide margin, driven by renovation obligations and municipal penalties on inefficient façades. Solar Panel grows fastest as module makers add dedicated cover-glass capacity in China and India, while Automotive follows electric vehicle production and larger panoramic roofs that raise coated glass area per vehicle.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA