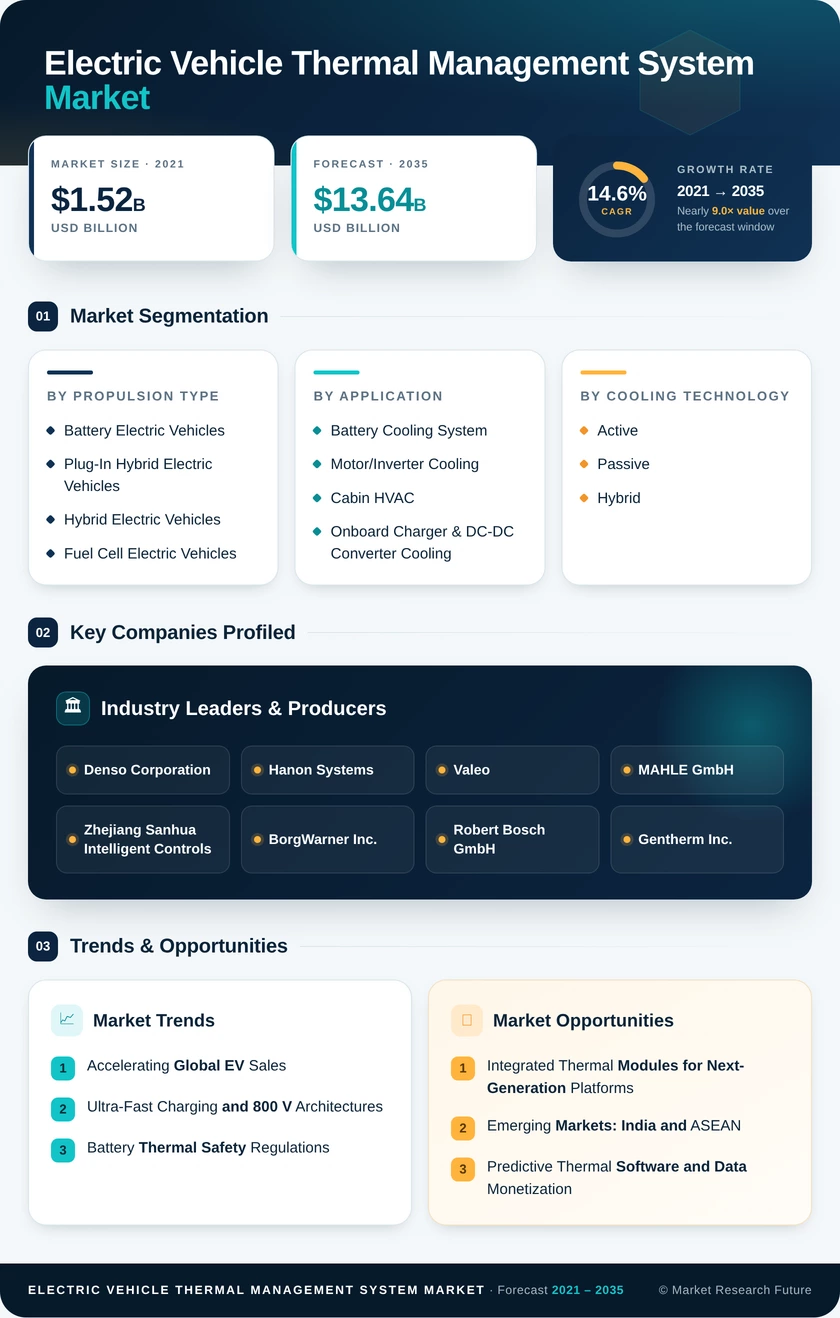
EV Thermal Management System Market (2026 - 2035)

ID: MRFR/AT/6679-HCR 150 Pages Shubham Munde Last Updated: October 16, 2026
Electric Vehicle Thermal Management System Market Research Report By Propulsion Type (Battery Electric Vehicles, Plug-In Hybrid Electric Vehicles, Hybrid Electric Vehicles, Fuel Cell Electric Vehicles), By Application (Battery Cooling System, Motor/Inverter Cooling, Cabin HVAC, Onboard Charger & DC-DC Converter Cooling), By Cooling Technology (Active, Passive, Hybrid), By Component (Heat Exchangers and Cold Plates, Coolant Pumps and Valves, Compressors, Thermal Interface Materials, Sensors and Controllers), By Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles, Two-Wheelers) - Forecast to 2035
EV Thermal Management System Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)14.62%
2025 Market SizeUSD 3.97 Billion
2035 Market SizeUSD 15.52 Billion
Key Players
Denso Corporation
Hanon Systems
Valeo
MAHLE GmbH
Zhejiang Sanhua Intelligent Controls
BorgWarner Inc.
Opportunities
  • Integrated Thermal Modules for Next-Generation Platforms
  • Emerging Markets: India and ASEAN
  • Predictive Thermal Software and Data Monetization
  1. 1 Market Summary | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Propulsion Type | |
    2. 2.2 By Application | |
    3. 2.3 By Cooling Technology | |
    4. 2.4 By Component | |
    5. 2.5 By Vehicle Type | |
    6. 2.6 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Forecast Market Size (2026–2035) | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Accelerating Global EV Sales | |
    2. 4.2 Ultra-Fast Charging and 800 V Architectures | |
    3. 4.3 Battery Thermal Safety Regulations | |
    4. 4.4 Heat Pump Adoption for Cold-Climate Range | |
    5. 4.5 Zero-Emission Mandates and Durability Rules | |
    6. 4.6 Commercial Vehicle Electrification | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Cost Pressure from EV Price Competition | |
    2. 5.2 Refrigerant and PFAS Regulatory Uncertainty | |
    3. 5.3 Withdrawal of US Purchase Incentives | |
    4. 5.4 Tariff-Driven Material Cost Inflation | |
    5. 5.5 System Integration and Validation Complexity | |
  6. 6 Opportunities | |
    1. 6.1 Integrated Thermal Modules for Next-Generation Platforms | |
    2. 6.2 Emerging Markets: India and ASEAN | |
    3. 6.3 Predictive Thermal Software and Data Monetization | |
    4. 6.4 Fast-Charging Infrastructure and Immersion Cooling | |
    5. 6.5 Battery Passport and Second-Life Thermal Services | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of MEA | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 AI-Driven Predictive Thermal Control | |
    2. 8.2 Integrated Architectures and Platform Economics | |
    3. 8.3 The Megawatt Charging Era | |
    4. 8.4 Natural Refrigerants and Sustainability Reporting | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Propulsion Type | | |
      1. 9.1.1 Battery Electric Vehicles | | |
      2. 9.1.2 Plug-In Hybrid Electric Vehicles | | |
      3. 9.1.3 Hybrid Electric Vehicles | | |
      4. 9.1.4 Fuel Cell Electric Vehicles | |
    2. 9.2 By Application | | |
      1. 9.2.1 Battery Cooling System | | |
      2. 9.2.2 Motor/Inverter Cooling | | |
      3. 9.2.3 Cabin HVAC | | |
      4. 9.2.4 Onboard Charger & DC-DC Converter Cooling | |
    3. 9.3 By Cooling Technology | | |
      1. 9.3.1 Active | | |
      2. 9.3.2 Passive | | |
      3. 9.3.3 Hybrid | |
    4. 9.4 By Component | | |
      1. 9.4.1 Heat Exchangers and Cold Plates | | |
      2. 9.4.2 Coolant Pumps and Valves | | |
      3. 9.4.3 Compressors | | |
      4. 9.4.4 Thermal Interface Materials | | |
      5. 9.4.5 Sensors and Controllers | |
    5. 9.5 By Vehicle Type | | |
      1. 9.5.1 Passenger Cars | | |
      2. 9.5.2 Light Commercial Vehicles | | |
      3. 9.5.3 Heavy Commercial Vehicles | | |
      4. 9.5.4 Two-Wheelers | |
  10. 10 Competitive Landscape | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Report Summary Snapshot, 2025–2035 | |
  16. TABLE 2 Global Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis on CAGR, 2026–2035 | |
  18. TABLE 4 Restraints Impact Analysis on CAGR, 2026–2035 | |
  19. TABLE 5 Regional Summary, by Region, 2025 | |
  20. TABLE 6 North America Market, by Country, 2025–2035 | |
  21. TABLE 7 Europe Market, by Country, 2025–2035 | |
  22. TABLE 8 Asia-Pacific Market, by Country, 2025–2035 | |
  23. TABLE 9 South America Market, by Country, 2025–2035 | |
  24. TABLE 10 Middle East & Africa Market, by Country, 2025–2035 | |
  25. TABLE 11 Global Market, by Propulsion Type, 2025–2035 | |
  26. TABLE 12 Global Market, by Application, 2025–2035 | |
  27. TABLE 13 Global Market, by Cooling Technology, 2025–2035 | |
  28. TABLE 14 Global Market, by Component, 2025–2035 | |
  29. TABLE 15 Global Market, by Vehicle Type, 2025–2035 | |
  30. TABLE 16 Competitive Benchmarking Matrix, 2025 | |
  31. TABLE 17 Report Scope and Methodology | |
  32. TABLE 18 Detailed Sources and Citations | |
  33. TABLE 19 Segmentation Quick Reference | | LIST OF FIGURES | |
  34. FIGURE 1 Market Dynamics Overview (Drivers, Restraints, Opportunities) | |
  35. FIGURE 2 Industry Value Chain Analysis | |
  36. FIGURE 3 Porter's Five Forces Analysis | |
  37. FIGURE 4 Global Market Size Trend (USD Billion), 2021–2035 | |
  38. FIGURE 5 Market Share, by Propulsion Type, 2025 | |
  39. FIGURE 6 Market Share, by Application, 2025 | |
  40. FIGURE 7 Market Share, by Cooling Technology, 2025 | |
  41. FIGURE 8 Market Share, by Component, 2025 | |
  42. FIGURE 9 Market Share, by Vehicle Type, 2025 | |
  43. FIGURE 10 Regional Market Share, 2025 | |
  44. FIGURE 11 Competitive Landscape — Estimated Revenue Share Ranges of Key Players, 2025

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Propulsion TypeBattery Electric Vehicles; Plug-In Hybrid Electric Vehicles; Hybrid Electric Vehicles; Fuel Cell Electric VehiclesBattery Electric Vehicles (67.0% share)Fuel Cell Electric Vehicles (15.1% CAGR)
By ApplicationBattery Cooling System; Motor/Inverter Cooling; Cabin HVAC; Onboard Charger & DC-DC Converter CoolingBattery Cooling System (39.8% share)Battery Cooling System (39.8% share)
By Cooling TechnologyActive; Passive; HybridActive (55.2% share)Hybrid (16.0% CAGR)
By ComponentHeat Exchangers and Cold Plates; Coolant Pumps and Valves; Compressors; Thermal Interface Materials; Sensors and ControllersHeat Exchangers and Cold Plates (35.0% share)Thermal Interface Materials (15.6% CAGR)
By Vehicle TypePassenger Cars; Light Commercial Vehicles; Heavy Commercial Vehicles; Two-WheelersPassenger Cars (60.8% share)Heavy Commercial Vehicles (16.3% CAGR)
By RegionNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaAsia-Pacific (52.4% share)Asia-Pacific (52.4% share)


Market Segmentation Overview

By Propulsion Type

Sub-SegmentKey Trend
Battery Electric VehiclesLarger packs and 800 V platforms raise thermal content per vehicle
Plug-In Hybrid Electric VehiclesStable volumes, but fewer new dedicated thermal architectures
Hybrid Electric VehiclesCompact battery cooling, often air-based
Fuel Cell Electric VehiclesSeparate stack, hydrogen, and battery circuits


Battery Electric Vehicles lead because full liquid cooling, heat pumps, and inverter loops are standard on every pack. Fuel Cell Electric Vehicles grow fastest, since stacks running near 80 °C need their own circuits alongside the traction battery, multiplying valves and sensors. Plug-In Hybrid Electric Vehicles hold volume but attract less new engineering as automakers prioritize pure electric platforms.

By Application

Sub-SegmentKey Trend
Battery Cooling SystemMicro-channel cold plates for 4C charging
Motor/Inverter CoolingTighter junction limits on silicon carbide inverters
Cabin HVACHeat pumps replacing resistive PTC heaters.
Onboard Charger & DC-DC Converter CoolingHigher on-board charging power levels


Battery Cooling System both leads and grows fastest, because fast charging and high-nickel chemistries demand tighter cell temperature uniformity. Motor/Inverter Cooling is second, driven by 800 V silicon carbide switching. Cabin HVAC expands steadily as heat pumps become standard to protect winter range.

By Cooling Technology

Sub-SegmentKey Trend
ActiveLiquid and refrigerant loops as the passenger EV default
PassivePhase-change panels and forced air in small packs
HybridHeat pipes and immersion combined with cold plates


Active systems lead because liquid and refrigerant loops are the only practical option for large, fast-charging passenger packs. Hybrid architectures grow fastest by combining heat pipes, immersion, and cold plates to balance weight and energy draw. Passive cooling stays relevant in two-wheelers and for peak-load support.

By Component

Sub-SegmentKey Trend
Heat Exchangers and Cold PlatesUniversal fitment on liquid-cooled packs and inverters
Coolant Pumps and ValvesBrushless variable-flow pumps and sensor-equipped valves
CompressorsElectric compressors for heat pumps and battery chillers
Thermal Interface MaterialsHigh-conductivity gap fillers and mica barriers
Sensors and ControllersMulti-loop temperature and flow monitoring


Heat Exchangers and Cold Plates lead because every liquid-cooled pack and inverter requires them. Thermal Interface Materials grow fastest as cell-to-pack designs remove module housings and rely on gap fillers and mica barriers to move heat and contain thermal runaway. Coolant Pumps and Valves add value through brushless motors and integrated position sensing.

By Vehicle Type

Sub-SegmentKey Trend
Passenger CarsHigh-volume BEV platforms with standard heat pumps
Light Commercial VehiclesStandardized under-floor cooling modules for delivery vans
Heavy Commercial VehiclesRedundant pumps and dual-flow plates for 300+ kWh packs
Two-WheelersLow-cost air and passive cooling


Passenger Cars lead on volume, carrying full liquid loops and heat pumps across mainstream platforms. Heavy Commercial Vehicles grow fastest because packs above 300 kWh and continuous duty cycles require redundant pumps and oversized chillers. Light Commercial Vehicles expand with delivery fleet electrification, while Two-Wheelers rely on simpler, low-cost cooling.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.