Electric Vehicle High Voltage Dc Dc Converter Market (2026 - 2035)

Electric Vehicle High Voltage DC-DC Converter Market Research Report By Vehicle Type (Passenger Cars, Commercial Vehicles), By Propulsion Type (Plug-In Hybrid Vehicles, Battery Electric Vehicles, Fuel Cell Electric Vehicles), By Cooling Method (Liquid Cooled, Air-Cooled), By Input Voltage (200 V – 450 V, 450 V - 800 V, 800 V - 1000 V), By Output Voltage (12 V – 24 V, 24 V – 48 V), By Output Power (Less Than 2kW, 2kW and Above) - Forecast to 2035
ID: MRFR/AT/33458-HCR 100 Pages Abbas Raut, Swapnil Palwe Last Updated: November 08, 2026
Electric Vehicle High Voltage Dc Dc Converter Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)3.86%
2025 Market SizeUSD 125.2 Billion
2035 Market SizeUSD 182.85 Billion
Key Players
Robert Bosch GmbH
Denso Corporation
Toyota Industries Corporation
Valeo SA
Schaeffler AG
BorgWarner Inc.
Opportunities
  • High-Voltage-to-48 V Converters for Zonal Architectures
  • Localized Supply in Emerging Markets
  • Bidirectional Converters and Vehicle-to-Load

Electric Vehicle High Voltage Dc Dc Converter Market Summary

The Electric Vehicle High Voltage DC-DC Converter Market was valued at USD 1.78 Billion in 2025. It is projected to reach USD 2.03 Billion in 2026 and USD 6.15 Billion by 2035, a CAGR of 13.1% over 2026–2035. Two policy catalysts anchor that path. Regulation (EU) 2023/851 requires a 100% cut in fleet CO2 emissions for new cars and vans from 2035 [3], and China's extended new energy vehicle purchase-tax exemption, valued at roughly CNY 520 billion over 2024–2027, keeps domestic volumes rising [7]. Every battery electric and plug-in vehicle needs at least one converter to step traction-battery voltage down to its 12 V or 48 V rail, so converter demand follows EV output closely.

Under that volume growth, the technology itself is changing. Silicon MOSFET and IGBT designs with bulky magnetics are giving way to silicon carbide (SiC) and gallium nitride (GaN) switches that run at higher frequencies, shrink passive components and lift peak efficiency above 96%. Standalone converter boxes are also being folded into integrated units shared with the onboard charger. This redesign of electric vehicle power electronics is capital-intensive: Infineon has committed up to EUR 7 billion to its SiC fab in Kulim, Malaysia [10].

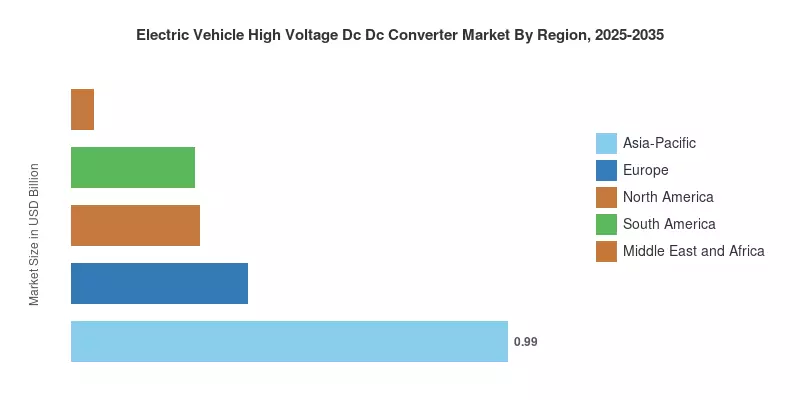
Asia-Pacific leads the Electric Vehicle High Voltage DC-DC Converter Market with a 55.4% share in 2025, reflecting China's position as the source of more than 60% of global electric car sales [2]. South America is the fastest-growing region at a 15.6% CAGR, supported by new local EV assembly in Brazil. Europe ranks second with a 22.6% share, sustained by fleet CO2 targets and a dense Tier-1 supplier base. Over the next decade, growth will depend less on unit volume alone and more on voltage architecture, integration and semiconductor content per vehicle.

Key Report Takeaways

• By Vehicle Type

  • Passenger Cars account for 78.4% of the Electric Vehicle High Voltage DC DC Converter Market in 2025, led by electric SUVs with heavy auxiliary loads.
  • Commercial Vehicles are the fastest-growing vehicle category at a 15.4% CAGR as vans, pickups and trucks electrify.

• By Propulsion Type

  • Battery Electric Vehicles hold 67.2% of revenue because the converter is their only source of low-voltage power once the vehicle is running.
  • Plug-In Hybrid Vehicles expand at a 15.1% CAGR, the quickest among propulsion types, on the back of China's PHEV surge.
  • Fuel Cell Electric Vehicles generate USD 0.05 Billion in 2025, concentrated in Japan, South Korea and China.

• By Cooling Method

  • Liquid-cooled converters grow at a 13.9% CAGR within the Electric Vehicle High Voltage DC-DC Converter Market as output ratings move above 3 kW.
  • Air-cooled units retain a 28.4% share, mainly on compact and lower-power platforms.

• By Region

  • Asia-Pacific commands a 55.4% share, anchored by Chinese vehicle and component production.
  • South America posts the highest regional CAGR at 15.6%.
  • North America generates USD 0.29 billion in 2025.

Market Size and Forecast (2021–2035)

Estimates for the Electric Vehicle High Voltage DC-DC Converter Market combine a bottom-up model and a top-down cross-check. The bottom-up model multiplies EV production by propulsion type, converter attach rate and average selling price by power class. The top-down check reconciles those results against disclosed segment revenues from leading Tier-1 suppliers [20][21] and against EV sales data from the International Energy Agency [1][2]. Primary interviews with converter engineers, purchasing managers and semiconductor suppliers informed price-erosion and integration assumptions.
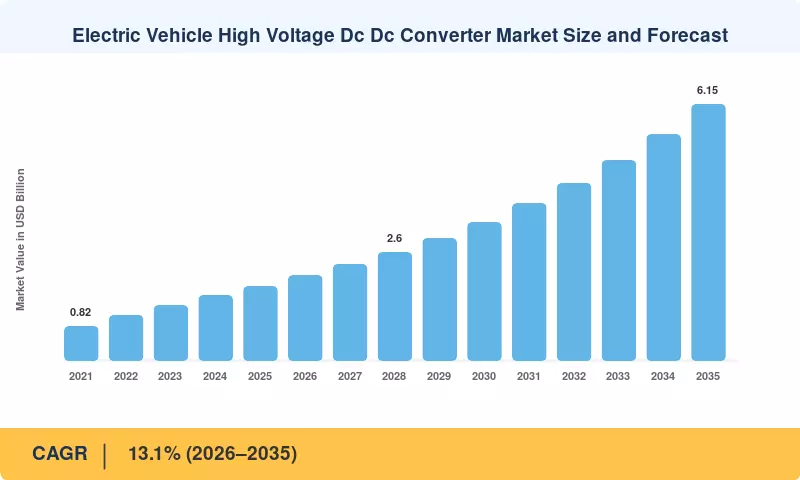
Electric Vehicle High Voltage Dc Dc Converter Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Impact percentages below are directional estimates of each driver's influence on the 13.1% CAGR of the Electric Vehicle High Voltage DC-DC Converter Market. They are not additive and should be read as relative weightings, since drivers overlap. Short-term means two years or less, medium-term two to four years, and long-term four years or more.

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Rising EV production and zero-emission mandates +3.2% Global Medium-term
Migration to 800 V vehicle architectures +2.4% Asia-Pacific, Europe Medium-term
Wide-bandgap semiconductor adoption +2.0% Global Long-term
Purchase incentives and industrial policy +1.8% China, India, Europe Short-term
Growing low-voltage auxiliary loads +1.6% North America, Europe Long-term
Commercial vehicle electrification +1.4% Europe, China, North America Medium-term


Rising EV Production and Zero-Emission Mandates

More than 17 million electric cars were sold worldwide in 2024, over 20% of new car sales, according to the IEA's Global EV Outlook 2025 [2]. Regulation (EU) 2023/851 sets a 55% fleet CO2 cut for new cars by 2030 and 100% by 2035 [3]. Each plug-in vehicle carries at least one high-voltage converter, so these mandates translate almost directly into converter volume across the Electric Vehicle High Voltage DC-DC Converter Market.

Migration to 800 V Vehicle Architectures

Hyundai's E-GMP platform brought 800 V charging into mass production [12], and BYD's Super e-Platform, announced in March 2025, pushes system voltage to 1,000 V [13]. Higher input voltage requires converters rated for 550–920 V, with 1,200 V switches and wider insulation clearances. These redesigns raise content value per unit and force suppliers to requalify product lines, favoring firms with established SiC design experience.

Wide-Bandgap Semiconductor Adoption

Yole Group projects the power SiC device segment to approach USD 10 billion by 2029, with automotive traction and conversion as its main outlet [11]. SiC switches cut switching losses sharply and allow operating frequencies several times higher than silicon, shrinking transformers and capacitors. Infineon's Kulim fab, budgeted at up to EUR 7 billion, is one of several capacity additions aimed at automotive demand [10].

Purchase Incentives and Industrial Policy

China's purchase-tax exemption for new energy vehicles runs through 2025 at full value and continues at half value in 2026–2027 [7]. India's PM E-DRIVE scheme, notified in September 2024, carries an outlay of INR 10,900 crore for electric two-wheelers, three-wheelers, buses and trucks [8]. These programs sustain near-term EV volumes even as incentives recede in some Western markets.

Growing Low-Voltage Auxiliary Loads

Driver assistance sensors, domain computers, electric steering, heat pumps and heated surfaces all draw from the low-voltage rail. Typical converter ratings have climbed from 1.5–2.5 kW toward 3–4 kW on premium platforms. Tesla's Cybertruck moved its low-voltage network to 48 V to handle these loads with thinner wiring [14], a design shift that requires new converter topologies.

Commercial Vehicle Electrification

Regulation (EU) 2024/1610 requires heavy-duty vehicle CO2 reductions of 45% by 2030, 65% by 2035 and 90% by 2040 versus 2019 levels [4]. Electric trucks and buses run larger auxiliary loads, including air compressors, refrigeration and hydraulic systems, which call for converters rated well above passenger-car levels. Suppliers with robust, high-power liquid-cooled designs stand to gain most.

Restraints Impact Analysis

Restraint impacts are directional estimates of downward pressure on the forecast CAGR. They overlap with one another and with the drivers above, so they should not be summed or netted against driver impacts.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
SiC substrate cost and supply concentration −1.5% Global Medium-term
OEM price pressure and EV price wars −1.2% China, Europe Short-term
EV policy volatility −1.0% North America, Europe Short-term
Integration compressing standalone converter value −0.9% Global Long-term
Functional safety and validation burden −0.7% Global Medium-term


SiC Substrate Cost and Supply Concentration

Substrate manufacture is concentrated among a few suppliers, and SiC devices are still two to three times more expensive than comparable silicon parts [11]. The vulnerability of the supply source was made clear by Wolfspeed's June 2025 Chapter 11 filing [17]. When compelled to switch substrate or device vendors, converter manufacturers incur both certification delays and cost risk.


OEM Price Pressure and EV Price Wars

Throughout 2024 and 2025, Chinese automakers consistently lowered the cost of EVs; in May 2025, BYD lowered the price of some models by as much as 34%. OEMs use yearly cost-cutting demands—typically 3–5% annually—to transfer such pressure to suppliers. In certain product classes, converter ASPs erode more quickly than volume increases, putting pressure on smaller suppliers.


EV Policy Volatility

US federal EV tax credits under Section 30D ended after 30 September 2025 under Public Law 119-21 [23], and federal vehicle emissions standards finalized in 2024 are under reconsideration [5]. The EU also granted automakers a three-year averaging window for 2025–2027 compliance [3]. Such shifts delay platform launches and make capacity planning harder for converter suppliers.

Integration Compressing Standalone Converter Value

Automakers increasingly buy multi-in-one power units that combine the converter, onboard charger and power distribution in a single housing. Shared cooling plates, enclosures and control boards cut total cost, but the converter's standalone value shrinks. Schaeffler's combination with Vitesco Technologies reflects consolidation toward system-level suppliers [18].

Functional Safety and Validation Burden

Converters feeding braking and steering loads must meet ISO 26262 functional safety requirements, often at ASIL C or D [15]. UN Regulation No. 100 adds electrical safety requirements for high-voltage systems [16]. Validation cycles of 18–30 months raise entry costs and slow product refreshes.

Electric Vehicle High Voltage Dc Dc Converter Market Opportunities

High-Voltage-to-48 V Converters for Zonal Architectures

A few regional controllers on a 48 V backbone take the role of numerous dedicated control units in zonal vehicle designs. Converters that step 400 V or 800 V directly to 48 V are in demand as a result of this change, and they are frequently combined with a secondary 48 V-to-12 V stage for legacy loads [14]. Larger content per vehicle is awarded to suppliers who provide both phases as a matched set.


Localized Supply in Emerging Markets

India, ASEAN countries and Brazil are building local EV supply chains behind tariff and incentive walls. Brazil's import duty on electric vehicles is rising in steps to 35% by July 2026 [24], and India's Production Linked Incentive scheme for automobiles and components carries an outlay of INR 25,938 crore [25]. Converter makers that localize assembly early can secure nominations in these fast-growing corners of the Electric Vehicle High Voltage DC DC Converter Market.

Bidirectional Converters and Vehicle-to-Load

Converters that can transfer electricity in both directions are necessary for vehicle-to-load and vehicle-to-home applications. External power output is already available in Hyundai's E-GMP cars [12], and other OEMs have comparable options planned for 2026–2028 models. Bidirectional designs allow vendors to differentiate themselves beyond efficiency metrics and seek higher prices.


Converter Telemetry and Service-Based Revenue

Converters sit at the center of low-voltage energy flow, which makes their operating data valuable. Temperature cycles, load profiles and efficiency drift can feed predictive maintenance for fleet operators, and suppliers can license analytics or offer over-the-air performance updates. Commercial fleets, where downtime costs are high, are the most likely early buyers of such services.

Fuel Cell and Heavy-Duty Platforms

Fuel cell trucks and buses in Japan, South Korea and China need both boost converters for the fuel cell stack and high-power step-down converters for auxiliaries. Volumes are small today, but content per vehicle is several times higher than in passenger cars. Suppliers that develop modular high-power platforms can serve this niche and heavy battery electric trucks with shared designs.

Electric Vehicle High Voltage Dc Dc Converter Market Future Outlook

800 V Becomes the Mainstream Platform

Across the Electric Vehicle High Voltage DC DC Converter Market, 800 V will move from premium models into mid-priced vehicles over the forecast period. The IEA expects electric cars to exceed 40% of global car sales by 2030 under stated policies [2], and a growing share of those will use 800 V or higher. Converter suppliers will need 1,200 V device supply and insulation designs as standard capabilities.

Wide-Bandgap Cost Curves Reshape Design Choices

Through the late 2020s, SiC wafer transitions from 150 mm to 200 mm should reduce device costs [11]. GaN will replace lower-voltage stages where magnetics are most reduced by its switching speed. Revenue growth will depend on greater power ratings since converters will get lighter and smaller, but their cost per kilowatt will decrease.


Software-Defined Vehicles and Zonal Power

Software-defined vehicles force onboard power distribution into zonal controllers and concentrate computation in central units. Converters will turn into managed nodes that can be controlled by software to report health data and modify output. In addition to hardware knowledge, suppliers will require experience in embedded software, cybersecurity, and over-the-air updates [16].


Supply Chain Transparency and Circularity

Regulation (EU) 2023/1542 introduces carbon footprint declarations and due diligence duties for batteries [22], and OEMs are extending similar expectations to power electronics. Converter makers in the Electric Vehicle High Voltage DC DC Converter Market will face audits covering copper, rare-earth magnets and semiconductor sourcing. Designs that ease disassembly and material recovery will gain an advantage in European tenders.

Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America USD 0.29 Billion Domestic sourcing rules, electric pickups, 48 V architectures
Europe 22.6% share Fleet CO2 compliance, heavy-duty electrification, SiC capacity
Asia-Pacific 55.4% share Chinese NEV scale, 800 V platforms, PHEV growth
South America 15.6% CAGR Brazilian local assembly, tariff-driven localization
Middle East and Africa 2.7% share Gulf EV industrial programs, early fleet adoption
Total USD 1.78 Billion —

Regional performance in the Electric Vehicle High Voltage DC DC Converter Market follows EV production more than EV sales, because converters are sourced where vehicles are assembled. Asia-Pacific holds the largest base, Europe and North America follow on regulation-driven demand, and South America and the Middle East and Africa grow from small starting points.


North America

Country Metric (2025) Key Driver
US 82.0% of region Electric pickup and SUV platforms; 48 V adoption
Canada 13.4% CAGR Battery and EV plant investments in Ontario and Quebec
Mexico 6.5% of region Near-shore electronics manufacturing

North America's Electric Vehicle High Voltage DC-DC Converter Market is shaped by domestic content rules introduced under the Inflation Reduction Act [6] and by electric pickups and SUVs with heavy auxiliary loads. The end of federal consumer credits in September 2025 [23] slows near-term volume, but platform commitments already in place keep converter sourcing active. The United States dominates regional demand, and Mexico gains share as a manufacturing base for power electronics exported to US assembly plants.


Europe

Country Metric (2025) Key Driver
Germany 27.5% of region Premium 800 V platforms and Tier-1 R&D base
UK USD 0.06 Billion ZEV mandate for new car sales
France 14.2% of region Domestic EV assembly and bonus schemes
Italy 12.6% CAGR Commercial van electrification
Spain 7.1% of the region New EV and battery plant investments
Nordic Countries 9.5% of region High EV penetration and electric trucks
Russia 2.4% of the region Limited domestic EV production
Rest of Europe USD 0.07 Billion Central European component manufacturing

European demand is regulation-led. Regulation (EU) 2023/851 for cars and vans [3] and Regulation (EU) 2024/1610 for heavy-duty vehicles [4] give suppliers a clear compliance timeline through 2040. Germany hosts most Tier-1 converter engineering centers, while France, Italy and Spain combine vehicle assembly with EU-funded semiconductor projects. The Nordic Countries lead in EV adoption rates and early electric truck deployment.


Asia-Pacific

Country Metric (2025) Key Driver
China 71.5% of region NEV scale, PHEV growth, price-competitive supply
India 21.4% CAGR PM E-DRIVE and PLI incentives
Japan 8.9% of region Hybrid and fuel cell platforms
South Korea USD 0.08 Billion 800 V platforms and export-oriented OEMs
ASEAN 18.2% CAGR Thai and Indonesian EV hubs
Rest of Asia-Pacific 3.1% of region Australian EV adoption

China anchors Asia-Pacific, supplying more than 60% of global electric car sales in 2024 [2] and producing converters at costs few Western rivals match. BYD's 1,000 V Super e-Platform [13] signals how quickly Chinese OEMs push voltage limits. Japan and South Korea lead in fuel cell vehicles and SiC device know-how, while India and ASEAN are the region's fastest risers under PM E-DRIVE [8] and local incentive programs.


South America

Country Metric (2025) Key Driver
Brazil 64.0% of region Local EV assembly by Chinese OEMs
Argentina 13.9% CAGR Lithium-linked battery investment
Rest of South America 17.5% of region Electric bus adoption in Chile and Colombia

South America grows fastest from a small base. Brazil's stepped import tariffs [24] have drawn Chinese OEMs into local assembly, which in turn pulls converter sourcing into the region. Argentina's lithium resources attract battery investment, although macroeconomic volatility limits near-term vehicle production.


Middle East and Africa

Country Metric (2025) Key Driver
Saudi Arabia 17.2% CAGR State-backed domestic EV manufacturing
UAE 30.5% of region Fleet electrification targets
South Africa 18.0% of region Export-linked EV production
Egypt 14.1% CAGR Electric bus and light vehicle assembly
Rest of MEA 17.0% of the region Early-stage adoption

Gulf states are building EV industries from scratch, with Saudi Arabia backing domestic vehicle brands and the UAE promoting fleet electrification. South Africa exports vehicles to Europe and must follow EU zero-emission timelines to keep that trade. Egypt is emerging as a lower-cost assembly location for electric buses and light vehicles.


Electric Vehicle High Voltage Dc Dc Converter Market By Region, 2025-2035

Electric Vehicle High Voltage Dc Dc Converter Market Segmentation

By Vehicle Type

Passenger Cars lead the Electric Vehicle High Voltage DC DC Converter Market with a 78.4% share, driven by electric SUVs, which need higher-rated converters for climate control, driver assistance and infotainment. Sedans and hatchbacks add volume with compact, lower-power designs. Commercial Vehicles grow faster, at a 15.4% CAGR, as electric vans, pickup trucks and buses enter logistics and municipal fleets. Their larger auxiliary loads and duty cycles raise converter power ratings and unit value well above passenger-car averages.

Segment Metric (2025) Primary Demand Driver
Passenger Cars 78.4% share Electric SUV volumes and rising auxiliary loads
Commercial Vehicles 15.4% CAGR Fleet electrification and heavy-duty CO2 rules


By Propulsion Type

Battery Electric Vehicles hold 67.2% of the Electric Vehicle High Voltage DC DC Converter Market because the converter is their sole low-voltage power source while driving, which demands high ratings and redundancy. Plug-In Hybrid Vehicles are the fastest-growing propulsion type at a 15.1% CAGR, lifted by China's rapid PHEV and range-extender adoption. Fuel Cell Electric Vehicles generate USD 0.05 billion, concentrated in Japanese, Korean and Chinese commercial fleets that also use boost converters for the fuel cell stack.

Segment Metric (2025) Primary Demand Driver
Plug-In Hybrid Vehicles 15.1% CAGR Chinese PHEV and range-extender growth
Battery Electric Vehicles 67.2% share Zero-emission mandates and 800 V platforms
Fuel Cell Electric Vehicles USD 0.05 Billion Hydrogen truck and bus programs in Asia


By Cooling Method

Liquid-cooled converters dominate the Electric Vehicle High Voltage DC DC Converter Market and also grow fastest, at a 13.9% CAGR, because they share coolant loops with inverters and chargers inside integrated power units. Ratings above 3 kW are difficult to cool with air in sealed underhood enclosures. Air-cooled units retain a 28.4% share on compact cars, mild-power PHEVs and cost-sensitive platforms where simpler packaging outweighs thermal limits.

Segment Metric (2025) Primary Demand Driver
Liquid Cooled 13.9% CAGR Integrated power units and higher power ratings
Air Cooled 28.4% share Low-cost, lower-power vehicle platforms


Competitive Benchmarking

The Electric Vehicle High Voltage DC-DC Converter Market shows medium concentration, with an estimated Herfindahl-Hirschman Index of about 1,050 and a top-five share of roughly 42%. Japanese and European Tier-1 suppliers lead on established OEM relationships, while Chinese suppliers gain share through cost and speed. Consolidation toward integrated power-unit suppliers, as in Schaeffler's combination with Vitesco Technologies [18], is reshaping the field.

Company Est. Revenue Share Range Key Offerings for Electric Vehicle High Voltage DC-DC Converter Market Strategic Positioning
Robert Bosch GmbH ~9–12% High-voltage converters, integrated power units Broad OEM access and SiC in-house capability [20]
Denso Corporation ~8–11% Converters for hybrid and battery electric platforms Deep ties with Japanese OEMs [21]
Toyota Industries Corporation ~7–10% Converters and onboard chargers Anchored in Toyota electrified vehicles
Valeo SA ~6–9% 400 V and 800 V converters, charger combinations European platform wins and 48 V expertise
Schaeffler AG (Vitesco Technologies) ~6–8% Integrated high-voltage power electronics System-level supplier after merger [18]
BorgWarner Inc. ~4–6% Converters and integrated drive modules North American and Chinese OEM exposure
Delta Electronics, Inc. ~4–6% Converters and multi-in-one power units Power conversion expertise from industrial markets
Hyundai Mobis Co., Ltd. ~3–5% Integrated charging control units Captive supply to Hyundai and Kia 800 V platforms [12]
LG Magna e-Powertrain ~3–5% Converters, inverters and chargers Joint venture scale with global OEMs
TDK Corporation ~2–4% Converters and passive components Component-level integration and miniaturization


Recent News & Developments

  • - Robert Bosch (DE) — (2026): Bosch highlights its Generation 3evo high-voltage DC-DC converter, which converts high-voltage battery power to a 12V vehicle electrical network, with peak efficiency of up to 95%.
  • - Toyota Industries (JP) — (July, 2026): Toyota Industries verified bidirectional on-board charging for vehicle-to-grid applications, advancing power-conversion technology that enables EV batteries to supply electricity back to the grid.
  • - BorgWarner (US) — (August, 2026): BorgWarner secured extensions to high-volume inverter programs for plug-in hybrids and 800V battery-electric vehicles, strengthening its high-voltage automotive power-electronics portfolio.
  • - Hyundai Mobis (KR) — (May, 2026): Hyundai Mobis developed a 160-kW power-electric drive system and is expanding its range of EV drive systems, supporting broader electrification across vehicle segments.
  • - TDK (JP) — (June, 2026): TDK introduced compact automotive gate-drive transformers designed for 500V battery systems, supporting electrical isolation in traction inverters and compact DC-DC converters for electrified vehicles.
  • - Schaeffler / Vitesco Technologies (DE) — (January 2026): Schaeffler showcased Generation 4 and Generation 5 high-voltage DC-DC converters; Generation 5 supports 3.7-kW conversion with 400–800V input and 12–48V output.
  • - Valeo (FR) — (July, 2025): Valeo announced a 5-in-1 EV power-electronics module integrating an inverter, on-board charger, DC-DC converter, power distribution unit and eFuse, with production planned for 2026.
  • - Delta Electronics (TW) — Delta's current EV converter portfolio supports 400V and 800V battery inputs, with low-voltage outputs for vehicle electronics; no newer dated product announcement was verified.
  • - DENSO (JP) — DENSO's power-control unit integrates a DC-DC converter with other power-electronics components for hybrid and electric vehicles; no newer dated, converter-specific announcement was verified.
  • - LG Magna e-Powertrain (KR) — LG Magna offers on-board charging systems with integrated low-voltage DC-DC conversion for 400V and 800V architectures; no newer dated, high-voltage DC-DC-specific announcement was verified.

Electric Vehicle High Voltage Dc Dc Converter Market Report Scope

Report Attribute/Metric Details
Market Scope Electric Vehicle High Voltage DC-DC Converter Market by Vehicle Type, Propulsion Type, Cooling Method and Region
Study Period 2021-2035
Base Year 2025
Historical Data 2021–2024
Forecast Period 2026–2035
Market Size in 2025 USD 125.2 Billion
Market Size in 2035 USD 182.85 Billion
CAGR (2026–2035) 3.86%
Fastest Growing Segments Commercial Vehicles (15.4% CAGR); Plug-In Hybrid Vehicles (15.1% CAGR); Liquid Cooled (13.9% CAGR)
Regions Covered North America, Europe, South America, Asia Pacific, Middle East and Africa and ROW
Companies Profiled Robert Bosch, Denso, Toyota Industries, Valeo, Schaeffler (Vitesco Technologies), BorgWarner, Delta Electronics, Hyundai Mobis, LG Magna e-Powertrain, TDK
Valuation Currency USD Billion
Methodology 350+ primary expert interviews; bottom-up market sizing; top-down validation; data triangulation; scenario-based forecasting; real-time project tracking

FAQs

How does an 800 V input change converter design in the Electric Vehicle High Voltage DC-DC Converter Market?
Converters on 800 V platforms need 1,200 V-rated switches instead of 650 V parts, and SiC MOSFETs usually fill that role. Creepage and clearance distances also widen, which affects housing size and insulation cost [11].
What should OEM procurement teams prioritize when sourcing converters?
Dual-sourced semiconductor supply comes first, since switch shortages halted vehicle lines in 2021–2022. Buyers should also require documented ASIL ratings and field-failure rates per million units before nominating a supplier [15].
Is GaN a realistic alternative to SiC in the Electric Vehicle High Voltage DC-DC Converter Market?
GaN suits lower-voltage stages such as 48 V-to-12 V conversion, where its switching speed shrinks magnetics sharply. For 800 V inputs, SiC remains the practical choice until vertical GaN devices reach automotive qualification [11].
How do cybersecurity rules affect converter suppliers?
UN Regulation No. 155 has required a certified cybersecurity management system for all new vehicles registered in the EU since July 2024. Converters with firmware update or diagnostic interfaces fall within scope, adding secure-boot and event-logging requirements [16].
What investment risk matters most for new entrants to the Electric Vehicle High Voltage DC DC Converter Market?
Platform lock-in is the largest risk. Contracts are typically awarded three to four years before launch and run for the platform's life, so one missed nomination can exclude a supplier for most of a decade.
Do retrofit applications create converter demand outside new vehicles?
Yes, electric retrofit kits for buses and delivery vans in India and Europe need standalone converters matched to non-native low-voltage systems. Volumes are modest, but margins exceed OEM supply because units ship in small, customized batches [8].
How does converter efficiency affect vehicle range?
Each percentage point of efficiency saves roughly 20–40 W at typical 2–4 kW auxiliary loads. On long drives with heating and driver assistance active, that recovers a few kilometers of range and eases the thermal load on the cooling loop.
Author
Author Author Profile Abbas Raut LinkedIn Research Analyst
Abbas Raut is a Senior Research Analyst with 5+ years of experience delivering data-driven insights and strategic recommendations across the Automotive and Aerospace & Defense sectors. He specializes in emerging technologies, industry value chains, and global market dynamics shaping the future of mobility and defense. In automotive, Abbas has led studies on EVs, charging stations, BMS, superchargers, and more, guiding stakeholders through electrification and regulatory shifts. In Aerospace & Defense, he has analyzed markets for military electronics, drones, radars, and electronic warfare solutions, supporting procurement and investment strategies. With expertise in market sizing, forecasting, benchmarking, and technology adoption, Abbas is known for transforming complex datasets into actionable insights that drive strategy, innovation, and growth.
Co-Author Co-Author Profile Swapnil Palwe LinkedIn Team Lead - Research
With a technical background as Bachelor's in Mechanical Engineering, with MBA in Operations Management , Swapnil has 6+ years of experience in market research, consulting and analytics with the tasks of data mining, analysis, and project execution. He is the POC for our clients, for their consulting projects running under the Automotive/A&D domain. Swapnil has worked on major projects in verticals such as Aerospace & Defense, Automotive and many other domain projects. He has worked on projects for fortune 500 companies' syndicate and consulting projects along with several government projects.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















