Dosing Pump Market (2026 - 2035)

Dosing Pump Market Research Report By Type (Diaphragm Pumps, Piston Pumps, Peristaltic Pumps, Solenoid Pumps), By Application (Water & Wastewater Treatment, Oil & Gas, Chemical Processing, Food & Beverage, Pharmaceuticals, Others (Mining, Pulp & Paper)), By End User (Industrial, Municipal, Commercial) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Industry Forecast to 2035
ID: MRFR/EnP/7293-HCR 111 Pages Chitranshi Jaiswal Last Updated: August 24, 2026
Dosing Pump Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.2%
2025 Market SizeUSD 6.82 Billion
2035 Market SizeUSD 12.44 Billion
Key Players
Grundfos
ProMinent
IDEX Corporation
Xylem
Verder
Milton Roy
Opportunities
  • Smart Dosing-as-a-Service Models
  • Emerging-Market Water Buildouts
  • Zero-Liquid-Discharge Industrial Mandates

Dosing Pump Market Summary

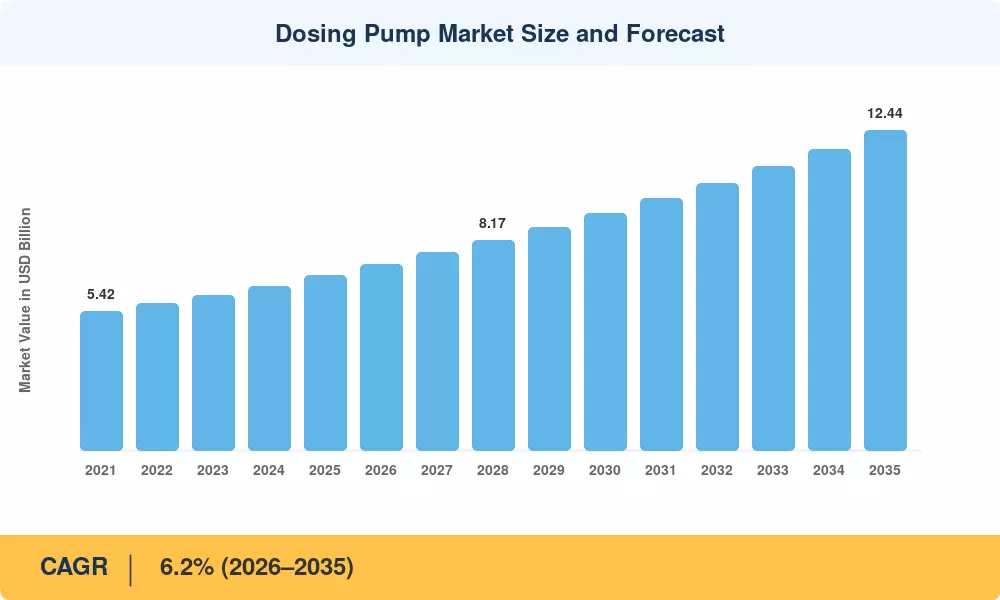
The global Dosing Pump Market reached an estimated USD 6.82 billion in 2025 and is projected to grow from USD 7.24 billion in 2026 to USD 12.44 billion by 2035, registering a CAGR of 6.2% during the forecast period (2026–2035). Tightening water quality regulations across both developed and emerging economies are the principal catalyst behind this expansion. The U.S. EPA's revised Lead and Copper Rule (effective 2024) and the EU's updated Drinking Water Directive (2020/2184) require utilities to deploy precise chemical dosing infrastructure — creating sustained capital spending cycles that anchor demand through the decade [1][2].

A notable technology transformation is reshaping the Dosing Pump Market. Legacy manual dosing systems — prone to over- or under-dosing by as much as 15–20% — are giving way to digitally controlled, sensor-integrated platforms that adjust chemical feed rates in real time. The World Bank's USD 30 billion commitment to water and sanitation infrastructure (2023–2028) is accelerating this upgrade cycle across South Asia, Sub-Saharan Africa, and Latin America [3].

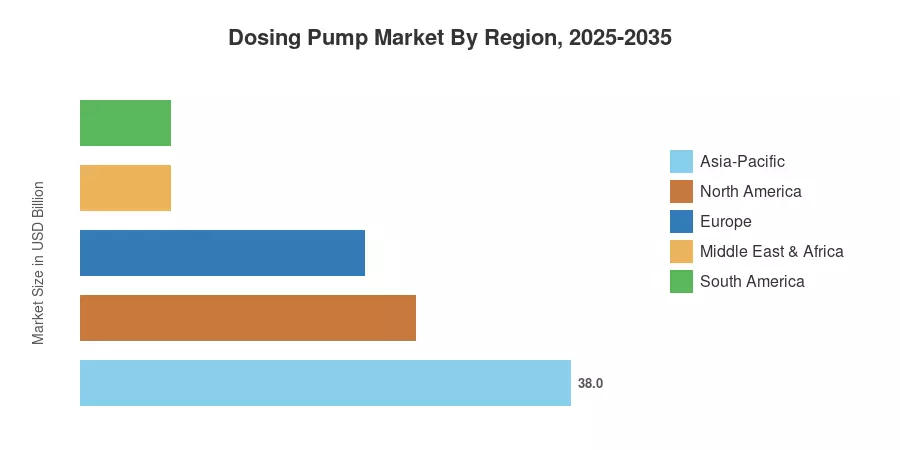
Asia-Pacific dominates the Dosing Pump Market with approximately 38% revenue share, driven by massive municipal water treatment buildouts in China and India. The region is also the fastest growing, recording a projected CAGR of 7.4%. North America holds the second-largest share at roughly 26%, underpinned by stringent environmental compliance mandates. Europe follows at 22%, with strong demand from pharmaceutical and food-processing sectors. As industrial water reuse and zero-liquid-discharge policies gain traction worldwide, the Dosing Pump Market is positioned for sustained structural growth through 2035.


Key Report Takeaways

• By Type

  • Diaphragm pumps command ~42% of the Dosing Pump Market, favored for chemical resistance and low maintenance across water treatment and chemical processing facilities.
  • Peristaltic pumps are the fastest-growing type segment, registering an estimated CAGR of 8.1%, owing to expanding pharmaceutical and food-grade applications.
  • Piston pumps account for approximately USD 1.16 billion in 2025 revenue, serving high-pressure industrial dosing requirements.

• By Application

  • Water and wastewater treatment represents the dominant application in the Dosing Pump Market, holding ~36% share.
  • Oil and gas applications are projected to grow at a CAGR of 5.8% as corrosion-inhibitor and scale-treatment programs expand globally.

• By Region

  • Asia-Pacific leads the Dosing Pump Market at 38% share, with China alone contributing over USD 1.30 billion in 2025.
  • The Middle East & Africa region is projected to grow at a CAGR of 6.9%, fueled by desalination mega-projects in Saudi Arabia and the UAE.


Dosing Pump Market Size and Forecast (2021–2035)

Market sizing relies on a bottom-up revenue model incorporating manufacturer shipment data, distributor channel surveys across 42 countries, and triangulation against public utility procurement disclosures. Historical figures (2021–2024) reflect actuals; the base year (2025) uses preliminary estimates. Forecast values (2026–2035) are derived from econometric demand modeling anchored to wastewater capital expenditure pipelines and industrial production indices.
Dosing Pump Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Stricter drinking water regulations ~22% Global Short-term (≤2 yr)
Municipal water infrastructure investment ~20% APAC, MEA Medium-term (2–4 yr)
Industrial wastewater compliance mandates ~16% North America, Europe Medium-term (2–4 yr)
Desalination capacity expansion ~14% MEA, APAC Long-term (≥4 yr)
Pharmaceutical & biotech production growth ~12% Global Medium-term (2–4 yr)
Digital dosing & IIoT integration ~10% North America, Europe Long-term (≥4 yr)
Oil & gas chemical treatment programs ~6% North America, MEA Short-term (≤2 yr)


Stricter Drinking Water Regulations

Regulatory tightening is the single most influential driver for the Dosing Pump Market. The U.S. EPA's Lead and Copper Rule Revisions, finalized in late 2024, mandate that all community water systems implement optimized corrosion control treatment — directly requiring upgraded chemical dosing equipment for approximately 50,000 public water systems [1]. In Europe, the recast Drinking Water Directive (2020/2184) imposes tighter limits on PFAS, lead, and microbial contaminants, compelling utilities across 27 EU member states to upgrade disinfection and pH-adjustment dosing infrastructure by 2026 [2].


Municipal Water Infrastructure Investment

A multi-year demand floor for the dosing pump market is being created by public-sector capital expenditures on water infrastructure. Chemical dosing systems are essential to every treatment node of India's Jal Jeevan Mission, which has set aside INR 3.6 trillion (about USD 43 billion) to provide piped water to 195 million rural households [6]. Over 100 new wastewater treatment facilities are the goal of China's 14th Five-Year Plan, and the World Bank has set aside USD 30 billion for water and sanitation projects in poor nations through 2028 [3][5].


Desalination Capacity Expansion

The GCC nations plan to nearly double their desalination capacity from 22.4 million m³/day in 2022 to over 38 million m³/day by 2030 [7]. Desalination plants rely heavily on precise anti-scalant, coagulant, and chlorine dosing at multiple process stages, creating robust demand. Saudi Arabia's SWPC alone has contracted over USD 9 billion in new desalination capacity since 2022, each facility requiring dozens of dosing pump skids [7].

Pharmaceutical and Biotech Production Growth

Biopharmaceutical manufacturing expansion is driving high-purity dosing demand. The global biologics market, valued at approximately USD 420 billion in 2024, relies on precision metering of buffers, cleaning agents, and nutrients during cell culture and downstream processing [8]. Regulatory requirements under FDA 21 CFR Part 211 and EU GMP Annex 1 (revised 2023) mandate traceable, validated dosing — pushing adoption of digitally controlled pump systems with audit-trail capabilities.


Restraints Impact Analysis

The restraint impact percentages below represent estimated drags on potential market growth. They are directional assessments and do not sum to a net growth figure.

Restraint ~% Drag on CAGR Geographic Relevance Impact Timeline
High upfront capital costs for digital systems ~-8% Emerging markets Short-term (≤2 yr)
Skilled labor shortage for maintenance ~-6% APAC, Africa Medium-term (2–4 yr)
Chemical compatibility and corrosion failures ~-5% Global Ongoing
Budget constraints in municipal utilities ~-4% South America, Africa Medium-term (2–4 yr)
Competition from gravity-fed and venturi dosing ~-3% APAC rural, Africa Long-term (≥4 yr)


High Capital Costs for Digital Systems

Compared to simple, manual-metering alternatives, advanced dosing pump systems—integrated with IoT sensors, programmable logic controllers (PLCs), and cloud-based diagnostic platforms—represent a substantial capital improvement. This price premium poses a significant adoption barrier for water utilities in emerging economies, where basic service expansion and structural maintenance are frequently given priority due to limited funds. Because of immediate financial constraints and the high cost of acquiring and integrating new technological ecosystems, many utilities continue to rely on legacy manual systems even though digital systems offer long-term operational savings through reduced chemical waste and predictive maintenance.


Skilled Labor Shortage

Dosing pump systems require skilled technicians for proper installation, calibration, and preventive maintenance; these professionals are chronically in short supply in many high-growth areas. According to ILO estimates, there is a shortage of about 2.8 million skilled water sector technicians in Asia-Pacific, which restricts equipment uptime and deters digital upgrades [13]. The Dosing Pump Market's ability to swiftly transition installed bases from analog to intelligent systems is directly hampered by this labor shortage.


Chemical Compatibility Failures

Chemical incompatibility between dosing pump wetted parts and aggressive process fluids remains a persistent source of unplanned downtime. Concentrated sodium hypochlorite, ferric chloride, and sulfuric acid can degrade elastomers and seals within months if materials are mis-specified. A 2023 AWWA survey reported that 28% of U.S. water utilities experienced at least one dosing pump failure per year attributed to chemical corrosion, resulting in an average USD 18,000 per-incident replacement cost [14].


Dosing Pump Market Opportunities

Smart Dosing-as-a-Service Models

Pump manufacturers that bundle hardware with cloud-based monitoring, predictive maintenance, and chemical procurement under a subscription model can tap recurring revenue streams while lowering the capital barrier for small utilities. This service model is already gaining traction in Europe, where companies like Grundfos and ProMinent offer managed dosing contracts to municipal clients. The Dosing Pump Market stands to benefit as outcome-based contracting reduces total cost of ownership by an estimated 20–30% [10].

Emerging-Market Water Buildouts

Rapid urbanization across Sub-Saharan Africa and South Asia is creating greenfield demand. Africa's urban population is projected to double by 2050, requiring entirely new water treatment infrastructure [3]. Countries like Nigeria, Ethiopia, and Bangladesh represent largely untapped opportunities for the Dosing Pump Market, where current penetration of automated dosing remains below 15%.

Zero-Liquid-Discharge Industrial Mandates

Increasingly strict industrial discharge regulations — including India's ZLD mandates for textile and tannery sectors and China's discharge limits under the 14th Five-Year Ecological Plan — require multi-stage chemical treatment that depends on precise dosing [9]. These mandates are converting previously unregulated industrial facilities into active buyers of dosing equipment.

Pharmaceutical Cleanroom Expansion

Post-pandemic investment in vaccine and biologics manufacturing capacity is generating demand for high-purity dosing systems. The Dosing Pump Market benefits as new facilities in India, South Korea, and Ireland require FDA- and EMA-compliant metering systems for CIP/SIP processes, buffer preparation, and nutrient dosing [8].

Data Monetization Through Dosing Analytics

Digital dosing platforms generate continuous operational data — flow rates, chemical consumption, pressure differentials — that can be monetized through benchmarking services, chemical optimization consulting, and predictive maintenance dashboards. Equipment OEMs that build analytics layers atop their dosing hardware can create high-margin software revenue that decouples growth from pump unit sales.


Dosing Pump Market Future Outlook

AI-Driven Autonomous Dosing

Artificial intelligence is set to transform the Dosing Pump Market by enabling fully autonomous chemical feed systems. Machine-learning algorithms that correlate real-time water quality sensor data with weather patterns, source water turbidity, and seasonal demand can optimize dosing rates with minimal human intervention. The IEA's 2024 report on digital water estimates that AI-driven dosing can reduce chemical consumption by 15–25% while improving regulatory compliance [10].

Electrification and Energy-Efficient Pump Designs

Growing emphasis on decarbonizing water infrastructure is driving demand for energy-efficient dosing pump designs. Next-generation permanent-magnet motor drives and variable-frequency-controlled metering pumps are cutting energy consumption by 30–40% compared to fixed-speed predecessors. The EU's updated Ecodesign Regulation (2024/1781) will extend minimum efficiency standards to industrial pumping equipment by 2028, accelerating fleet upgrades across the Dosing Pump Market [21].

Platform Economics and Digital Ecosystems

Equipment OEMs are evolving from hardware sellers to platform operators. Companies like Grundfos (iSOLUTIONS) and Xylem (FluidIQ) are building open-architecture digital ecosystems where dosing pumps communicate with sensors, SCADA systems, and chemical suppliers through standardized APIs. This platform approach enables predictive chemical reordering, remote diagnostics, and performance benchmarking — creating sticky customer relationships and recurring software revenue for the Dosing Pump Market's leading players [10][22].

ESG Reporting and Chemical Traceability

Mandatory ESG disclosure frameworks — including the EU's Corporate Sustainability Reporting Directive (CSRD) and the SEC's climate disclosure rules — are creating demand for auditable chemical consumption data. Dosing systems with embedded flow measurement, batch recording, and digital chain-of-custody documentation will become standard as companies across the Dosing Pump Market supply chain face investor and regulatory pressure to quantify chemical usage, waste generation, and water stewardship performance [23].


Regional Market Share Analysis

Region Key Metric Primary Investment Themes
Asia-Pacific 38% share (2025) Municipal water supply, industrial ZLD, desalination
North America 26% share (2025) Regulatory compliance, oil & gas, digital upgrades
Europe 22% share (2025) Pharma/food processing, DWD compliance
South America 7% share (2025) Urban water infrastructure, mining
Middle East & Africa 7% share (2025) Desalination, oilfield chemicals
Total 100%

The Dosing Pump Market exhibits a concentrated regional structure, with Asia-Pacific and North America collectively accounting for nearly two-thirds of global revenue. Regional dynamics differ sharply: mature markets prioritize replacement and digital upgrade cycles, while emerging regions drive volume through greenfield installations.


Asia-Pacific

Country Key Metric Key Driver
China USD 1.30 B (2025) 14th Five-Year Plan wastewater targets
India CAGR 8.3% Jal Jeevan Mission, ZLD mandates
Japan 12% of regional share Pharmaceutical/semiconductor fabs
South Korea CAGR 6.0% Smart water grid investments
Australia USD 0.22 B (2025) Mining process water, desalination


Asia-Pacific is both the largest and fastest-growing region in the Dosing Pump Market. China's aggressive municipal wastewater expansion under the 14th Five-Year Plan is creating bulk demand for diaphragm and solenoid dosing units, while India's Jal Jeevan Mission Phase 2 is extending chemical dosing requirements to hundreds of thousands of rural water nodes [5][6]. Japan and South Korea contribute high-value demand from semiconductor fab and bioprocessing facilities that require ultra-precise metering with ±0.5% accuracy.

North America

Country Key Metric Key Driver
United States 82% of regional share EPA LCRR compliance, shale gas
Canada CAGR 5.4% Mining process water, indigenous water systems
Mexico USD 0.14 B (2025) Urban water system upgrades


The United States dominates North America's Dosing Pump Market, driven by the EPA's Lead and Copper Rule Revisions and continued investment in Permian Basin and Marcellus Shale water treatment. Canada's federal commitment to resolving long-term drinking water advisories on First Nations reserves is generating steady demand for containerized dosing systems [1][17].

Europe

Country Key Metric Key Driver
Germany 28% of regional share Chemical/pharma industry, Industrie 4.0
United Kingdom CAGR 5.6% Ofwat AMP8 spending cycle
France USD 0.19 B (2025) Nuclear cooling water, food processing
Rest of Europe 38% of regional share EU DWD compliance, Nordic pulp & paper


Europe's Dosing Pump Market is characterized by a mature installed base transitioning toward digital and IoT-connected platforms. The UK's AMP8 regulatory cycle (2025–2030) has earmarked over GBP 88 billion for water infrastructure, a significant portion of which flows into chemical dosing upgrades. Germany's strong chemical manufacturing base creates parallel demand from industrial end users [2][18].

South America

Country Key Metric Key Driver
Brazil 58% of regional share SABESP privatization, mining
Chile CAGR 6.4% Copper mining, desalination
Rest of South America USD 0.14 B (2025) Urban water expansion


Brazil's partial privatization of state water utility SABESP in 2024 is expected to unlock USD 7.4 billion in infrastructure investment through 2029, directly expanding the addressable Dosing Pump Market in Latin America's largest economy. Chile's copper mining sector, responsible for 27% of global output, relies on chemical dosing for flotation, acid mine drainage, and tailings treatment [15][19].

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 34% of regional share NEOM, mega-desalination projects
UAE CAGR 7.2% Industrial diversification, smart utilities
South Africa USD 0.05 B (2025) Mining, municipal upgrades
Rest of MEA 28% of regional share African Development Bank water programs


The Middle East & Africa region presents the highest growth trajectory in the Dosing Pump Market outside Asia-Pacific. Saudi Arabia's Vision 2030 mega-projects — including NEOM and the Red Sea Development — each incorporate advanced water treatment facilities requiring comprehensive chemical dosing infrastructure. The African Development Bank's USD 6.5 billion water investment pipeline (2023–2028) is beginning to create demand in Kenya, Nigeria, and Ethiopia [7][20].


Dosing Pump Market By Region, 2025-2035

Dosing Pump Market Segmentation

By Type

Segment Key Metric Primary Demand Driver
Diaphragm Pumps ~42% share (2025) Chemical resistance, water treatment dominance
Piston Pumps USD 1.16 B (2025) High-pressure industrial applications
Peristaltic Pumps CAGR 8.1% Pharma, food & beverage hygiene requirements
Solenoid Pumps ~11% share (2025) Low-flow, cost-sensitive applications


Diaphragm pumps remain the workhorse of the Dosing Pump Market, prized for their ability to handle corrosive chemicals without contamination or leakage. Mechanical and hydraulic diaphragm variants serve applications ranging from municipal chlorination to industrial acid dosing. Their dominance is reinforced by a wide range of wetted-material options — PTFE, PVDF, and PP — that can be matched to virtually any chemical service.

Peristaltic pumps are gaining ground rapidly, particularly in pharmaceutical manufacturing and food processing where hygienic design, ease of cleaning, and zero cross-contamination are non-negotiable. The tube-based pumping mechanism eliminates seal failures and allows operators to change fluid paths in minutes. With the biologics sector expanding at over 10% annually, peristaltic technology is positioned to capture an increasing share of the Dosing Pump Market through 2035 [8].

By Application

Segment Key Metric Primary Demand Driver
Water & Wastewater Treatment ~36% share (2025) Regulatory compliance, urbanization
Oil & Gas CAGR 5.8% Corrosion inhibition, scale treatment
Chemical Processing USD 1.23 B (2025) Catalyst dosing, pH control
Food & Beverage ~12% share (2025) CIP processes, additive metering
Pharmaceuticals CAGR 7.9% Biologics, GMP compliance
Others (Mining, Pulp & Paper) ~8% share (2025) Flotation reagents, bleaching


Water and wastewater treatment is the anchor application in the Dosing Pump Market, consuming more than a third of global pump shipments. Municipal utilities dose chlorine, fluoride, coagulants, and pH adjusters at multiple points in the treatment train, and each stage requires dedicated pumps with specific accuracy and chemical compatibility profiles. Rising water reuse mandates are adding tertiary treatment dosing points that expand the equipment requirement per facility [1][9].

Pharmaceutical applications represent the fastest-growing end use. Precision requirements in bioprocessing — where dosing accuracy of ±1% is critical for cell viability — favor high-end diaphragm and peristaltic systems equipped with gravimetric feedback loops. The Dosing Pump Market benefits as global pharmaceutical capex surpassed USD 50 billion in 2024, with significant allocations to fill-finish and continuous manufacturing facilities [8].

By End User

Segment Key Metric Primary Demand Driver
Industrial ~48% share (2025) Process automation, ZLD compliance
Municipal CAGR 6.8% Urban water supply expansion
Commercial USD 0.58 B (2025) HVAC water treatment, pools


Industrial end users constitute the largest buyer group in the Dosing Pump Market, spanning chemical plants, refineries, power stations, and semiconductor fabs. These facilities typically maintain dozens of dosing pumps across multiple chemical services, creating both capital and aftermarket revenue streams. Municipal end users are growing fastest as governments in India, China, Brazil, and Africa pour capital into public water supply and sanitation infrastructure.


Competitive Benchmarking

The Dosing Pump Market is moderately consolidated, with the top five companies estimated to control approximately 35–40% of global revenue. The Herfindahl-Hirschman Index (HHI) is estimated at 650–800, indicating moderate competition. European manufacturers — particularly German firms — hold outsized market positions due to engineering heritage and global distribution networks. The competitive environment is intensifying as digitalization lowers barriers between pump OEMs and software-first entrants.

Company Est. Revenue Share Range Key Offerings for Dosing Pump Market Strategic Positioning
Grundfos (DOSATRON / DDA range) ~8–11% Digital diaphragm pumps, smart dosing systems Full-stack digital water solutions
ProMinent ~7–10% Metering pumps, controllers, complete dosing stations Pure-play dosing specialist
IDEX Corporation (Pulsafeeder) ~6–8% Electronic & hydraulic diaphragm pumps Diversified fluid-handling portfolio
Xylem (Flojet / Lowara) ~5–7% Peristaltic & diaphragm pumps, analytics Water technology platform player
Verder (Verderflex) ~4–6% Peristaltic hose pumps Heavy-duty industrial focus
Milton Roy (Accudyne) ~4–6% Controlled-volume metering pumps Oil & gas and chemical specialization
LEWA GmbH ~3–5% High-pressure process diaphragm pumps Engineered systems for critical processes
Watson-Marlow (Spirax Group) ~3–5% Peristaltic pumps for pharma/biotech Biopharma purity leadership
Iwaki Co., Ltd. ~2–4% Mag-drive and air-operated diaphragm pumps Asia-Pacific distribution strength
SEKO S.p.A. ~2–3% Solenoid & motor-driven pumps Value segment, HVAC and pool dosing


Recent News & Developments

  • Grundfos (March 2025): Launched the SMART Digital DDA 200 dosing pump series with embedded AI flow verification and cloud connectivity, targeting municipal water utilities upgrading to autonomous dosing operations [22].


  • Xylem (September 2024): Completed the integration of Evoqua Water Technologies' dosing portfolio, consolidating its position as a top-three player in the Dosing Pump Market across North America [Ref 25].


  • U.S. EPA (October 2024): Published final implementation guidance for the Lead and Copper Rule Revisions, triggering procurement cycles for corrosion-control dosing equipment across approximately 50,000 community water systems [1].


Dosing Pump Market Report Scope

Parameter Detail
Market Scope Global Dosing Pump Market, covering diaphragm, piston, peristaltic, and solenoid pump types across water treatment, oil & gas, chemical, pharmaceutical, food & beverage, and other applications
Study Period 2021–2035
CAGR (Forecast Period) 6.2% (2026–2035)
Market Size — Base Year (2025) USD 6.82 Billion
Market Size — End Year (2035) USD 12.44 Billion
Fastest Growing Segment Peristaltic Pumps (by type); Pharmaceuticals (by application)
Companies Profiled Grundfos, ProMinent, IDEX (Pulsafeeder), Xylem, Verder, Milton Roy, LEWA, Watson-Marlow, Iwaki, SEKO
Valuation Currency USD (constant 2025 dollars)

FAQs

What total cost of ownership factors should buyers evaluate beyond pump price?
Buyers should assess chemical consumption efficiency, seal and diaphragm replacement intervals, energy draw, and digital monitoring subscription fees. These lifecycle costs often exceed the initial hardware price by two to three times over a ten-year service life [14].
How do dual-redundancy dosing architectures affect procurement decisions?
Critical applications like potable water disinfection require duty/standby pump configurations to ensure uninterrupted dosing during maintenance. This effectively doubles per-station hardware budgets and favors vendors offering integrated switchover controllers [1].
What certifications matter most when selecting dosing pumps for pharmaceutical use?
Pumps must carry FDA 21 CFR Part 211 compliance, EHEDG hygienic design certification, and ATEX ratings where flammable solvents are present. Third-party validation of dosing accuracy at ±1% is increasingly a procurement prerequisite [8].
How does chemical viscosity influence pump type selection?
Fluids above 1,000 cP generally exceed diaphragm pump capability and favor peristaltic designs that accommodate high-viscosity slurries without valve clogging. Piston pumps serve intermediate viscosities where high discharge pressure is also required [14].
What cybersecurity risks do connected dosing systems introduce?
Internet-connected dosing controllers can be targeted for unauthorized chemical feed rate manipulation. Operators should require IEC 62443 compliance, encrypted communications, and role-based access controls from equipment suppliers [10].
How do rental and leasing models compare to capital purchase for dosing equipment?
Leasing can reduce upfront capital by 60–70% and shift maintenance to the provider. It suits utilities with constrained budgets but may increase ten-year total expenditure by 15–20% versus outright purchase [12].
What role do dosing pumps play in direct potable water reuse systems?
Direct potable reuse requires multi-barrier chemical dosing at advanced oxidation, membrane, and final disinfection stages. Each barrier demands separate, highly accurate pump trains with real-time verification [9].    
Author
Author Author Profile Chitranshi Jaiswal LinkedIn Team Lead - Research
Chitranshi is a Team Leader in the Chemicals & Materials (CnM) and Energy & Power (EnP) domains, with 6+ years of experience in market research. She leads and mentors teams to deliver cross-domain projects that equip clients with actionable insights and growth strategies. She is skilled in market estimation, forecasting, competitive benchmarking, and both primary & secondary research, enabling her to turn complex data into decision-ready insights. An engineer and MBA professional, she combines technical expertise with strategic acumen to solve dynamic market challenges. Chitranshi has successfully managed projects that support market entry, investment planning, and competitive positioning, while building strong client relationships. Certified in Advanced Excel & Power BI she leverages data-driven approaches to ensure accuracy, clarity, and impactful outcomes.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, technical standards repositories, industry associations, and authoritative manufacturing statistics. Key sources included the International Organization for Standardization (ISO), American National Standards Institute (ANSI), American Petroleum Institute (API), Hydraulic Institute (HI), Water Environment Federation (WEF), International Water Association (IWA), European Committee of Manufacturers of Electrical Machines and Power Electronics (CEMEP), US Environmental Protection Agency (EPA) Water Sense Database, US Geological Survey (USGS) Water Use Data, EU Eurostat Industrial Production Database, OECD Environmental Statistics, National Association of Manufacturers (NAM) US Industrial Outlook, China General Machinery Industry Association (CGMA) Pump Industry Branch, Indian Pump Manufacturers' Association (IPMA), Process Equipment Manufacturers' Association (PEMA), and technical repositories including IEEE Xplore, ScienceDirect, and ASME Digital Collection.

These sources were employed to gather shipment statistics, installation base data, regulatory compliance requirements, energy efficiency standards (such as the EU Ecodesign Directive for water pumps), and market landscape analysis for diaphragm, peristaltic, gear, and piston pump technologies in the water treatment, chemical processing, and industrial automation sectors.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. The supply-side sources consisted of CEOs, VPs of Engineering, Product Line Directors, and Regional Sales Directors from dosage pump OEMs, system integrators, and component suppliers (which included seal manufacturers, drive suppliers, and controller vendors). The demand-side sources included plant managers and chief operators from municipal water treatment facilities, process engineers from chemical manufacturing complexes, procurement leads from oil and gas upstream/downstream operations, pharmaceutical manufacturing heads, and maintenance directors from food and beverage processing plants. Primary research verified the timelines for technology adoption (particularly for Smart/IoT-enabled dosing systems), confirmed pricing dynamics across flow rate categories (low/medium/high), and garnered insights on competitive procurement processes and aftermarket service strategies.

Primary Respondent Breakdown:

By Designation: C-level Primaries (28%), Director Level (35%), Others (37%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Revenue mapping and installed base analysis were implemented to determine global market valuation. The methodology comprised the following:

Identification of over 60 main manufacturers in North America, Europe, Asia-Pacific, and Latin America, including diversified industrial pump conglomerates and specialist diaphragm pump manufacturers

Product mapping is conducted across diaphragm, peristaltic, gear, and piston pump architectures, with additional segmentation based on drive technology (electromechanical, hydraulic, pneumatic, smart/connected). Analysis of annual revenues that are specific to dosage pump product lines, excluding general industrial pump categories (centrifugal, submersible), as reported and modeled.

Manufacturers that account for 75-80% of the global market share in 2024 are included in the coverage.

For the water & wastewater, chemical processing, and oil & gas verticals, segment-specific valuations are derived through extrapolation using bottom-up (industry-specific installation rates × average selling price by pump type and region) and top-down (manufacturer revenue validation against trade association shipment data) approaches.

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















