Dental Laboratories Market (2026 - 2035)

Dental Laboratories Market Research Report: Size, Share, Trend Analysis By Laboratory Type (Full-service Dental Laboratories, Commercial Dental Laboratories, Specialty Dental Laboratories), By Product Type (Crowns, Bridges, Dentures, Orthodontic Appliances, Implants), By Technology (Digital Workflow, CAD/CAM Technology, 3D Printing, Conventional Techniques), By End Use (Dental Clinics, Hospitals, Dental Chains) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth Outlook & Industry Forecast 2025 To 2035

Forecast Period
2026-2035
CAGR
6.62%
2025 Market Size
USD 27.86 Billion
2035 Market Size
USD 52.88 Billion
Healthcare Services ● Updated September 10, 2026 Report ID: MRFR/HS/7810-HCR | Pages: 128 | Author: Rahul Gotadki, Nidhi Mandole

Dental Laboratories Market Summary

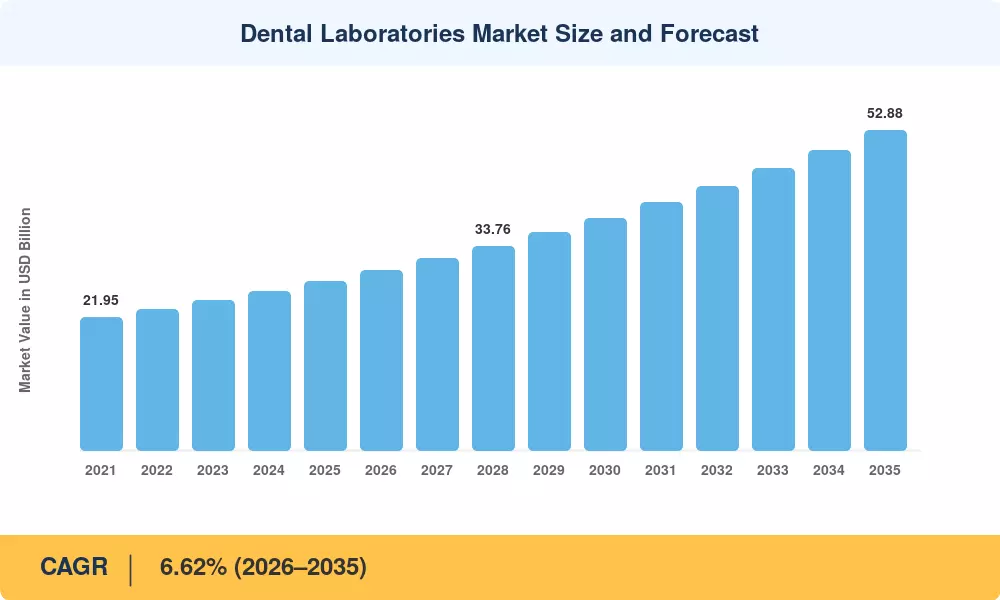
The Dental Laboratories Market closed 2025 at USD 27.86 billion and enters the forecast window at USD 29.70 billion in 2026, expanding to USD 52.88 billion by 2035 at a 6.62% CAGR. Two catalysts anchor that trajectory. Medicare Advantage plans in the United States expanded comprehensive dental benefits to roughly 97% of enrollees by 2025, pushing prosthetic case volumes upward [3]. Across the European Union, statutory sickness funds increased denture and crown co-payment coverage in Germany alone by an estimated EUR 1.1 billion between 2022 and 2025 [6].

Production economics are currently undergoing a transformation. Intraoral scan files, five-axis milling, and sintered zirconia are replacing gypsum models, lost-wax casting, and hand-layered porcelain. In 2024, capital expenditures on laboratory-grade 3D printers and milling centers surpassed USD 2.3 billion globally, and approximately 58% of restorative cases now undergo at least one digital step [4][14]. A contemporary digital dental lab workflow reduces a seven-day crown cycle to less than 48 hours.

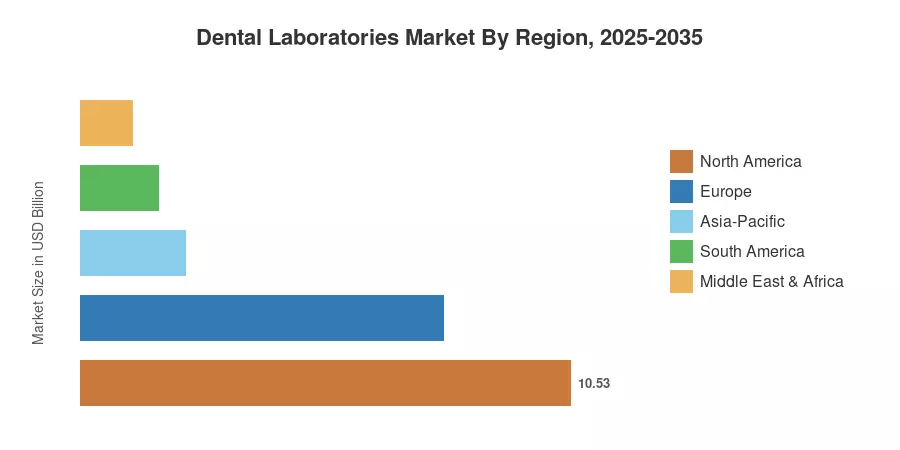
The regional hierarchy is stable, but it is increasingly constricting. The dental laboratories market is dominated by North America, which accounts for 37.8% of the market due to the consolidation of dental service organizations. China's implant volume-based procurement reforms and India's expanding private clinic base are the primary factors driving Asia-Pacific's 8.1% CAGR growth. Through its primacy in material science, Europe maintains its 28.0% market share. The competitive question will transition from who can fabricate to who can fabricate at the quickest pace over the next decade.


Key Report Takeaways

• By Product and Services

  • Consumables and Accessories command 52.0% of Dental Laboratories Market revenue, sustained by recurring zirconia disc and alloy replenishment.
  • Software and Services post the strongest expansion at 9.4% CAGR as design outsourcing and subscription CAD licensing scale.

• By Workflow

  • Digital workflow accounted for USD 16.30 billion in 2025, overtaking analog production for the first time.
  • Prosthodontics holds 41.0% of discipline-level demand, the single largest case category.


• By Discipline

  • Implantology grows at 8.7% CAGR, the fastest discipline within the Dental Laboratories Market.

• By Region

  • North America contributed USD 10.53 billion in 2025
  • Asia-Pacific expands at 8.1% CAGR through 2035

Table 1: Dental Laboratories Market Size and Forecast, 2021–2035. Source: Market Research Future Analysis

Growth dips modestly in 2024 as offshore unit pricing cuts realised revenue per case despite rising volumes. The 2026 acceleration reflects benefit-design changes taking effect across US and German payer systems simultaneously.
 

Dental Laboratories Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Ageing population and edentulism prevalence +1.30 Global; acute in Japan, Italy, Germany Long-term (≥4 yr)
Digital scanning and CAD/CAM adoption +1.10 Global Medium-term (2–4 yr)
Implant procedure volume growth +0.90 Europe, Asia-Pacific Long-term (≥4 yr)
DSO consolidation of laboratory spend +0.80 North America Medium-term (2–4 yr)
Cross-border outsourcing to low-cost hubs +0.60 Asia-Pacific supply to NA/EU Short-term (≤2 yr)
High-translucency zirconia advances +0.50 Global Medium-term (2–4 yr)
Public reimbursement expansion for prosthetics +0.40 Europe, Japan, China Short-term (≤2 yr)


Table 2: Driver Impact Matrix. Source: Market Research Future Analysis

Demographic Pressure on Prosthetic Demand

Global aging trends drive steady requirements for dental prosthetics. The World Health Organization documents that oral diseases affect roughly 3.5 billion people worldwide, with severe conditions heavily impacting older demographics. International public health datasets show that populations aged 65 and older experience high rates of complete tooth loss, generating continuous demand for removable and fixed restorations across commercial dental laboratories


Digital Retooling of Production Floors

Laboratory workflow modernization relies on digital capture systems. National Institutes of Health research documents baseline clinical crown remake rates at approximately 4%. Public health infrastructure analyses note that digital impression adoption reduces impression remakes and accelerates turnaround times. Laboratories integrating computer-aided manufacturing toolchains achieve greater production efficiency, minimizing material waste while handling higher daily fabrication volumes through standardized digital file transmissions from clinical practices


Implantology as a Volume Multiplier

Surgical dental implant procedures multiply downstream laboratory workloads. World Health Organization datasets indicate that oral diseases affect roughly 3.5 billion people globally, with severe tooth loss driving continuous demand. Public health infrastructure reports note that policy measures expanding access to restorative care increase patient volume, ensuring each clinical implant placement reliably generates subsequent abutment, surgical guide, and crown work.


Group Purchasing and DSO Scale

Corporate dental service organizations reshape market fulfillment channels. American Dental Association Health Policy Institute reports indicate that approximately 16% of US dentists are affiliated with a dental support organization, showing steady growth in group practice models. These centralized entities mandate multi-state fulfillment capabilities and digital API-level order integration, driving volume predictability for partnered laboratories while introducing competitive pricing pressures across the broader sector.


Restraints Impact Analysis

Restraint impacts are directional drag estimates derived from operator interviews and margin disclosures. They interact with one another and should not be subtracted sequentially from headline growth.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Skilled dental technician shortage −0.90 Global; severe in US, Germany Long-term (≥4 yr)
Chairside milling cannibalising outsourced cases −0.70 North America, Western Europe Medium-term (2–4 yr)
Price compression from offshore competition −0.60 North America, Europe Short-term (≤2 yr)
Capital intensity of digital conversion −0.50 Small and mid-size labs globally Medium-term (2–4 yr)
Regulatory compliance burden −0.40 Europe, North America Short-term (≤2 yr)


Table 3: Restraint Impact Matrix. Source: Market Research Future Analysis

The Technician Pipeline Problem

Dental laboratory technician workforce pipelines face structural talent constraints. US Bureau of Labor Statistics occupational reports indicate that specialized production environments maintain a workforce base of approximately 35,000 dental technicians, with thousands of annual openings driven primarily by retirement replacements. Labor market analyses emphasize that skilled-role wage growth and ongoing technical recruitment challenges continue to strain operational margins across commercial fabrication facilities.


Compliance Cost Asymmetry

EU Medical Device Regulation classifies custom restorations as Class IIa custom-made devices, requiring Annex XIII documentation, technical files, and post-market surveillance systems [13]. Compliance costs for a 30-technician European laboratory run between EUR 45,000 and EUR 90,000 in the first year—smaller operators either exit or sell.


Dental Laboratories Market Opportunities

Surgical Guide and Appliance Diversification

Specialized clinical devices diversify laboratory revenue. World Health Organization datasets indicate that global oral disease burdens impact roughly 3.5 billion people, driving consistent demand for customized oral appliances. Laboratories leveraging existing resin 3D printing equipment can efficiently expand into production lines for static and dynamic surgical guides, therapeutic sleep devices, and custom protective sports guards with minimal incremental capital expenditure.


Emerging Market Formalisation

Developing dental markets undergo progressive operational formalization. Public health infrastructure metrics emphasize that expanding clinical networks in high-growth developing economies increasingly demand standardized, ISO-certified laboratory suppliers. Early market consolidators capable of capturing certified production capacity establish regional benchmark standards, driving long-term quality improvements and price stabilization across rapidly modernizing regional healthcare systems.


Design-as-a-Service and Data Monetisation

Digital connectivity transforms laboratory workflow structures. Remote computer-aided design services enable cross-border collaboration and overnight case turnaround for partner facilities. Aggregated digital case parameters support advanced predictive shade-matching and fit-prediction models, allowing modern facilities to license validated digital outputs back to clinical networks and optimize overall production efficiency.


Full-Arch Fixed Restoration Economics

Complex full-arch restorations reshape case-value hierarchies. Comprehensive implant-supported prostheses generate substantially higher laboratory revenue per case compared to standard single crown treatments, while improving treatment affordability and expanding clinical access across international healthcare markets.


Dental Laboratories Market Future Outlook

Machine Learning in Design Automation

Automated margin detection and occlusal design already reduce technician touch-time per unit by 40–60% in leading operations. By 2030, expect design software to auto-complete an estimated 70% of single-unit cases with human review limited to exception handling. Labour scarcity makes this less a cost play than a capacity survival strategy [15].

Platform Economics and Order Aggregation

Digital ordering portals reshape commercial relationships across healthcare sectors. World Health Organization datasets indicate that global oral disease burdens impact roughly 3.5 billion people worldwide, driving consistent demand for coordinated oral care services. Healthcare infrastructure analyses emphasize that integrated practice management systems streamline operational coordination between dental clinics and production facilities, improving order-routing predictability and securing long-term operational stability for commercial laboratories.

Material Substitution Toward Monolithic Systems

Materials science research confirms a steady shift in restorative dentistry. National Institutes of Health literature demonstrates that monolithic zirconia and advanced ceramic systems possess superior mechanical properties and high flexural strength compared to traditional materials, successfully displacing porcelain-fused-to-metal restorations. This material evolution structurally lowers metal alloy requirements while improving margin resilience and aesthetic outcomes across commercial laboratory production lines.


Dental Laboratories Market Segmentation

By Product and Services

Segment Metric Primary Demand Driver
Consumables and Accessories 52.0% share Recurring disc, resin, and alloy replenishment
Equipment Type (Milling Equipment and More) USD 7.66 Billion Digital retooling capital cycles
Software and Services 9.40% CAGR Subscription CAD and outsourced design


Table 10: Segmentation by Product and Services. Source: Market Research Future Analysis

Consumables anchor the Dental Laboratories Market because they scale directly with case volume and resist substitution. Zirconia discs alone represent an estimated USD 3.9 billion annual spend. Software grows fastest as laboratories shift from perpetual licences to per-unit design fees, converting fixed cost into variable cost and lowering the barrier for small operators to compete on complex cases.

By Dental Discipline

Segment Metric Primary Demand Driver
Prosthodontics 41.0% share Ageing population and edentulism [1]
Orthodontics USD 6.69 Billion Clear aligner attachment and retainer volume
Implantology 8.70% CAGR Global implant placement growth [9]
Endodontics 9.0% share Post-and-core restorative follow-through
Periodontics and Others USD 2.09 Billion Surgical guide and splint fabrication


Table 11: Segmentation by Dental Discipline. Source: Market Research Future Analysis

Prosthodontics remains the revenue backbone of the Dental Laboratories Market, but implantology delivers the superior growth and margin profile. A single full-arch case can equal fifteen crown units in laboratory revenue. Orthodontic work has been partially disintermediated by aligner manufacturers producing in-house, though retainer and appliance volumes continue flowing to independent laboratories.

By Material Type

Segment Metric Primary Demand Driver
Zirconia 34.0% share Strength-to-aesthetics improvement curve [14]
Metal-Ceramic USD 7.94 Billion Installed clinical preference and durability
Acrylics and Composites 19.0% share Removable denture and temporary work
Alloys 4.10% CAGR Framework and partial denture casting
Others USD 1.95 Billion Lithium disilicate and hybrid ceramics


Table 12: Segmentation by Material Type. Source: Market Research Future Analysis

The segment table highlights market distribution across material types. Metal-Ceramic stands as the dominating segment with a valuation of USD 7.94 Billion, driven by installed clinical preference and durability. Conversely, Alloys represents the fastest growing segment, expanding at a 4.10% CAGR to support framework and partial denture casting. Zirconia holds a 34.0% share, while Acrylics and Composites and Others contribute significantly.

By Workflow

Segment Metric Primary Demand Driver
Digital USD 16.30 Billion Scanner penetration and turnaround compression
Conventional/Analog 41.5% share Complex removables and legacy practice habits


Table 13: Segmentation by Workflow. Source: Market Research Future Analysis

Digital crossed the halfway mark in 2024 and continues gaining roughly three share points annually. Analog will not vanish; full dentures, certain layered anterior cases, and repairs still reward hand skill. The realistic 2035 equilibrium sits near 78% digital.

By End User

Segment Metric Primary Demand Driver
Independent Dental Labs 54.0% share Long-standing clinician relationships
DSO-Owned and Group Labs 9.10% CAGR Vertical integration of case spend [7]
Hospital-Affiliated Labs USD 3.48 Billion Maxillofacial and complex rehabilitation cases
Chairside/In-Clinic Labs 7.5% share Single-visit restoration adoption [11]


Table 14: Segmentation by End User. Source: Market Research Future Analysis

Independent laboratories still hold the majority, yet their share has slipped roughly six points since 2020. Group-owned facilities grow fastest because DSOs capture the laboratory margin internally while guaranteeing throughput. Hospital-affiliated units occupy a defensible niche in reconstructive and oncology-adjacent work that volume operators avoid.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 37.8% share DSO platform roll-ups, digital order integration
Europe USD 7.80 Billion Material science, MDR-compliant scale operators
Asia-Pacific 8.10% CAGR (2026–2035) Implant volume growth, export production hubs
South America 6.0% share Clinic chain expansion, affordability-led prosthetics
Middle East & Africa USD 1.11 Billion Medical tourism corridors, sector formalisation
Total USD 27.86 Billion

Geographic performance in the Dental Laboratories Market tracks three variables: payer coverage depth, clinic density, and technician labour cost. Regions scoring high on the first two but low on the third capture disproportionate value.


Table 4: Regional Summary. Source: Market Research Future Analysis

North America

Country Metric Key Driver
US 84.0% of region Medicare Advantage dental benefit expansion [3]
Canada USD 1.06 Billion Canadian Dental Care Plan rollout [20]
Mexico 7.40% CAGR Cross-border case fulfilment and dental tourism [12]


Table 5: North America Country Analysis. Source: Market Research Future Analysis

Canada's federal dental plan reached an estimated 3.2 million enrolled residents by mid-2025, with denture and crown coverage phased in for adults under 65 [20]. South of the border, consolidation dominates: the ten largest US laboratory groups now handle roughly 29% of national case volume, up from 18% five years earlier [7]. Mexican border-state laboratories in Tijuana and Los Algodones fulfil an estimated 4.5 million US-origin units annually.

Europe

Country Metric Key Driver
Germany 25.5% of region Statutory prosthetic co-payment increases [6]
UK USD 1.24 Billion NHS backlog clearance and private conversion [17]
France 6.10% CAGR 100% Santé zero-cost prosthetic scheme [6]
Italy 12.0% of region Highest elderly population share in EU [2]
Spain USD 0.62 Billion Private clinic chain density
Nordic Countries 5.40% CAGR Early digital workflow saturation
Russia 4.8% of region Domestic substitution of imported materials
Rest of Europe USD 0.71 Billion Poland and Hungary export laboratory capacity


Table 6: Europe Country Analysis. Source: Market Research Future Analysis

France's 100% Santé reform eliminated out-of-pocket costs for a defined basket of crowns and dentures, lifting covered prosthetic claims by an estimated 34% between 2020 and 2024 [6]. Poland and Hungary have become the continent's fulfilment backbone, exporting an estimated EUR 480 million in restorations annually to Germany, Austria, and the UK. British laboratories, squeezed by NHS unit-of-dental-activity pricing, are pivoting toward private implant work [17].

Asia-Pacific

Country Metric Key Driver
China 34.0% of region Volume-based implant procurement expansion [10]
India 9.60% CAGR Organised clinic chain growth and export labs [19]
Japan USD 1.51 Billion Highest elderly prosthetic claim rate globally [8]
South Korea 8.40% CAGR Domestic implant manufacturer ecosystem
ASEAN USD 0.74 Billion Vietnam and Thailand medical tourism
Rest of Asia-Pacific 7.8% of region Australia private health insurance dental cover


Table 7: Asia-Pacific Country Analysis. Source: Market Research Future Analysis

China's National Healthcare Security Administration extended centralised procurement to implant systems in 2023, cutting system prices sharply and expanding annual placements past 5 million units [10]. Korean manufacturers, Osstem and Dentium, leveraged that shift to build regional share, pulling laboratory demand along with them. Indian export laboratories in Chennai and Ahmedabad now ship to more than 30 countries at unit costs 55–70% below US equivalents [19].

South America

Country Metric Key Driver
Brazil 56.0% of region Largest dentist population globally [5]
Argentina USD 0.24 Billion Currency-driven export competitiveness
Rest of South America 6.80% CAGR Chile and Colombia private insurance growth


Table 8: South America Country Analysis. Source: Market Research Future Analysis

Brazil counts more than 380,000 registered dentists, roughly one for every 550 residents, supporting a dense and highly fragmented laboratory base [5]. ANVISA registration requirements introduced tighter material traceability in 2024, accelerating a shift toward larger certified operators. Argentine laboratories, aided by peso depreciation, increasingly serve regional export demand.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia USD 0.29 Billion Vision 2030 health sector transformation [21]
UAE 8.90% CAGR Dubai medical tourism inbound volumes
South Africa 14.5% of region Established private dental insurance base
Egypt 7.90% CAGR Population scale and low-cost production
Rest of MEA USD 0.26 Billion Nigeria and Kenya urban clinic growth


Table 9: Middle East & Africa Country Analysis. Source: Market Research Future Analysis

Saudi Arabia's Health Sector Transformation Programme has licensed more than 900 new private dental facilities since 2021, with prosthetic capacity lagging clinical capacity by a wide margin [21]. Dubai Health Authority reported inbound dental medical tourism receipts above AED 1.2 billion in 2024. Local fabrication remains thin, leaving import dependence at an estimated 65% of high-end restorative units.


Dental Laboratories Market By Region, 2025-2035

Competitive Benchmarking

Concentration in the Dental Laboratories Market is moderate. Estimated HHI sits near 620, with the top five participants controlling roughly 27–31% of global revenue. Thousands of sub-USD-5-million laboratories occupy the long tail, particularly across Southern Europe, Latin America, and South Asia. Consolidation is accelerating but faces a natural ceiling: clinician relationships remain local, and turnaround expectations reward geographic proximity.

Company Est. Revenue Share Range Key Offerings for Dental Laboratories Market Strategic Positioning
Modern Dental Group ~7–10% Fixed and removable prosthetics, aligners Largest global outsourced fabricator; Asia cost base
Glidewell Laboratories ~6–9% Crowns, implants, in-house milling systems Vertically integrated from material to restoration
National Dentex Labs (NDX) ~3–5% Full-service restorative network, USA Multi-site North American consolidation platform
Dentsply Sirona ~3–5% CAD/CAM systems, furnaces, materials Equipment and consumables ecosystem supplier
Ivoclar ~2–4% Lithium disilicate, ceramics, digital solutions Material science and shade system leadership
Straumann Group ~2–4% Implants, digital design, aligner platforms Implant-anchored workflow ownership
Envista Holdings ~2–4% Scanners, implants, orthodontic supplies Diversified clinical-to-laboratory bridge
3Shape ~1–3% Scanners, Dental System design software Design software standard-setter
Argen Corporation ~1–3% Alloys, zirconia discs, milling services Material supply plus outsourced production
Amann Girrbach ~1–3% Milling units, sintering, workflow software Turnkey laboratory automation specialist


Table 15: Competitive Benchmarking. Share ranges are directional estimates and do not sum precisely. Source: Market Research Future Analysis


Recent News & Developments

  • Straumann Group (March 2025): Launched an expanded digital workflow suite integrating implant planning with laboratory design handoff, targeting reduced case cycle time across partner laboratories [9].


  • US Centers for Medicare & Medicaid Services (October 2024): Confirmed continued flexibility for Medicare Advantage supplemental dental benefits for plan year 2025, sustaining prosthetic claim growth [3].


  • European Commission (January 2024): Extended MDR transition timelines for certain custom-made device classes, easing near-term compliance pressure on smaller European laboratories [13].


  • Health Canada / Government of Canada (December 2023): Launched the Canadian Dental Care Plan, phasing in coverage that includes dentures and crowns for eligible residents [20].


Dental Laboratories Market Report Scope

Parameter Detail
Market Scope Global fabrication of dental prostheses, restorations, and appliances, including equipment, consumables, software, and outsourced services
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 6.62% (2026–2035)
Market Size Checkpoints USD 27.86 Billion (2025); USD 29.70 Billion (2026); USD 52.88 Billion (2035)
Fastest Growing Segments Software and Services; Implantology; Digital workflow; Asia-Pacific
Companies Profiled Modern Dental Group, Glidewell Laboratories, National Dentex Labs, Dentsply Sirona, Ivoclar, Straumann Group, Envista Holdings, 3Shape, Argen Corporation, Amann Girrbach
Valuation Currency USD (Billion), constant 2025 prices

Table 16: Report Scope and Methodology. Source: Market Research Future Analysis

FAQs

How should investors evaluate acquisition targets in the Dental Laboratories Market?
Prioritise laboratories with above-40% digital case throughput and group contracts running longer than three years. Valuation multiples cluster between 6x and 9x EBITDA, with scanner-integrated operations commanding the premium. [22]
What procurement terms matter most when a clinic selects an outsourced laboratory partner?
Turnaround guarantees, remake policy, and file-format interoperability outweigh headline unit price. Insist on documented STL compatibility and a contractual remake rate below 3%. [16]
How does chairside milling compare with sending cases to an external laboratory?
Chairside units suit single-unit restorations under time pressure; laboratories retain the edge on multi-unit bridges, layered aesthetics, and complex removables. Break-even for in-office milling typically requires 12–15 units monthly. [11]
Which regulatory nuance most often surprises new entrants to the Dental Laboratories Market?
Custom-made device rules differ sharply by jurisdiction. Under EU MDR, laboratories must issue Annex XIII statements and maintain post-market surveillance files, obligations that US-registered facilities rarely encounter. [13]
What integration challenges arise when adopting a fully digital case pipeline?
Scanner-to-design file mismatches and clinician training gaps cause most early failures. Budget six to nine months before throughput recovers to pre-migration levels. [4]
Are there emerging use cases beyond restorative work in the Dental Laboratories Market?
Sleep-apnea appliances, sports guards, and surgical guides now form a fast-expanding revenue line. Several mid-size operators report double-digit growth in guide production tied to implant planning software. [9]
How concentrated is buying power on the customer side?
Group practice organisations control a growing share of case volume and negotiate aggressively on price. Independent practices remain the margin cushion, so laboratories over-indexed to group accounts face structural pressure. [7]      
Author
Author
Author Profile
Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.
Co-Author
Co-Author Profile
Nidhi Mandole LinkedIn Senior Research Analyst
She is an extremely curious individual currently working in Healthcare and Medical Devices Domain. Nidhi is comfortably versed in data centric research backed by healthcare educational background. She leverages extensive data mining and analytics tools such as Primary and Secondary Research, Statistical Analysis, Machine Learning, Data Modelling. Her key role also involves Technical Sales Support, Client Interaction and Project management within the Healthcare team. Lastly, she showcases extensive affinity towards learning new skills and remain fascinated in implementing them.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















