Data Center Server Market (2026 - 2035)

Data Center Server Market Size, Share and Research Report By Tier Type (Tier 1 and 2, Tier 3, Tier 4), By Data Center Size (Small, Medium, Large, Hyperscale), By Data Center Type (Colocation, Enterprise (On-Premises), Hyperscaler / Cloud Operator), By Form Factor (Half-Height Blades, Full-Height Blades, Quarter-Height / Micro-Blades), By Application / Workload (AI and Machine Learning, Virtualization and Private Cloud, High-Performance Computing, General Enterprise and Web Hosting) and By Regional (North America, Europe, South America, South Africa, Asia Pacific, Middle East and Africa) - Industry Forecast to 2035.
ID: MRFR/ICT/27713-HCR 100 Pages Nirmit Biswas, Aarti Dhapte Last Updated: August 24, 2026
Data Center Server Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)14.9%
2025 Market SizeUSD 117.70 Billion
2026 Market SizeUSD 135.10 Billion
2035 Market SizeUSD 471.90 Billion
Key Players
Dell Technologies
Hewlett Packard Enterprise
Lenovo
Inspur
Super Micro Computer
Cisco Systems
Opportunities
  • Edge-AI Server Deployments in Manufacturing and Retail
  • Server-as-a-Service and Consumption-Based Procurement
  • Open-Compute and Disaggregated Hardware Architectures

Data Center Server Market Summary

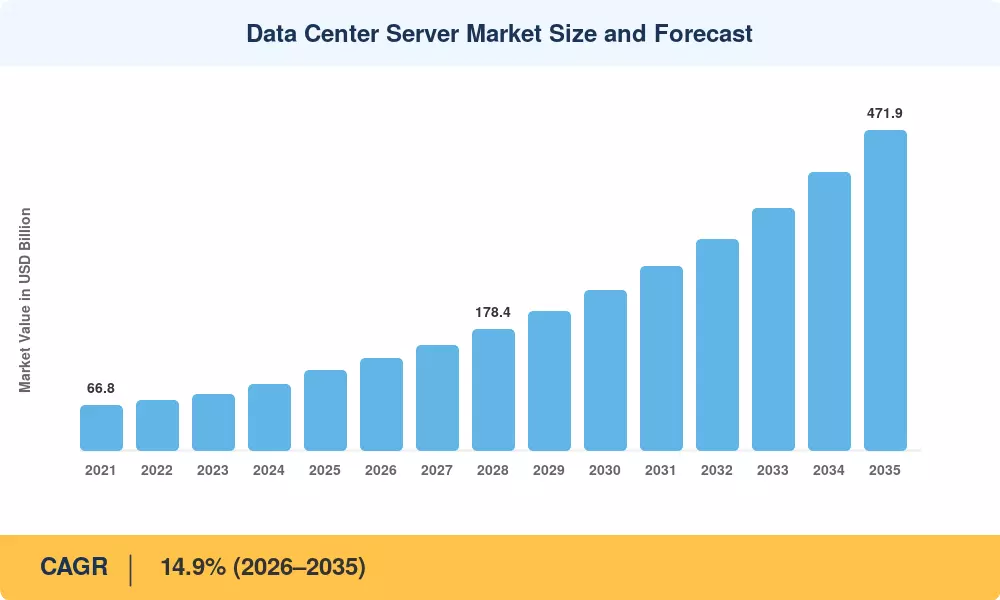
The data center server market reached an estimated USD 117.70 Billion in 2025 and is projected to grow from USD 135.10 Billion in 2026 to USD 471.90 Billion by 2035, registering a compound annual growth rate of 14.9% across the forecast period. This expansion draws momentum from two converging forces: the exponential scaling of artificial-intelligence training workloads that demand GPU-dense rack configurations, and sovereign-AI policy mandates—particularly in the European Union and the Gulf Cooperation Council—that are channeling public investment into domestic compute infrastructure [1].

The data center server market is currently experiencing a significant technological transition. Legacy air-cooled 1U and 2U rack servers, which were originally designed for general-purpose virtualization, are gradually being replaced by liquid-cooled, accelerator-optimized chassis that can support 80 kW or more per rack. The U.S. Department of Energy's USD 1.2 billion allocation for national AI research infrastructure through 2028 is a testament to the fact that government spending is expediting this hardware refresh cycle [2]. Hyperscalers are securing multi-year component agreements with DRAM suppliers in response to high-bandwidth memory constraints, and OEMs are redesigning motherboard layouts around direct-to-chip cooling circuits.

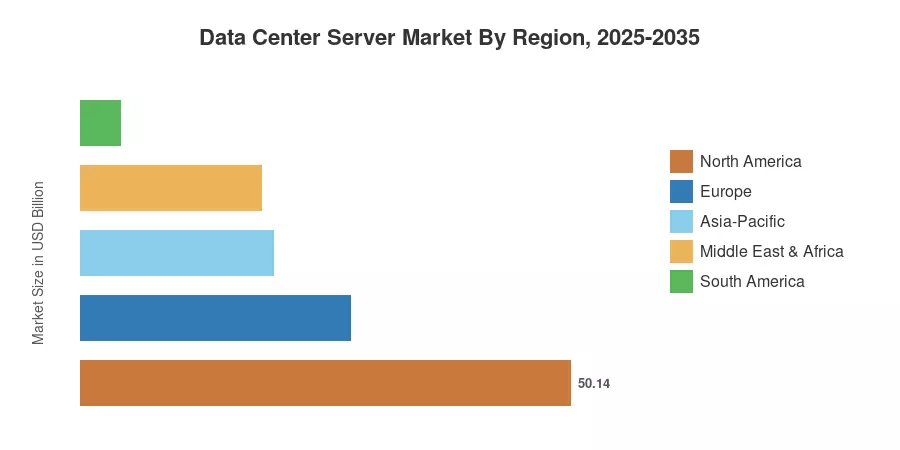
North America has the highest market share of data center servers, accounting for approximately 42.6% of 2025 revenue. Hyperscale campus deployments in Virginia, Texas, and Oregon primarily drive this market. The Asia-Pacific region is the fastest-growing, with a projected CAGR of 16.8% through 2035. The aggressive cloud buildouts in India, Japan, and Southeast Asia are driving this growth. Europe is the second-largest region, contributing approximately 23.5% of global expenditure, thanks to the EU Chips Act and GDPR-driven data-residency requirements. The data center server market is expected to experience sustained double-digit growth through the mid-2030s as AI workloads continue to diversify beyond training into real-time inference.


Key Report Takeaways

• By Tier Type

  • Tier 3 facilities captured approximately 52.8% of the data center server market share in 2025, reflecting their balance of redundancy and cost efficiency.
  • Tier 4 data centers are projected to expand at a 19.0% CAGR through 2035 as mission-critical AI inference workloads demand fault-tolerant uptime guarantees.

• By Form Factor

  • Half-height blade servers accounted for 58.3% of unit shipments in 2025, dominating high-density rack deployments.


• By Application

  • AI and machine-learning workloads represented 40.8% of the data center server market in 2025, outpacing traditional enterprise computing segments.

• By Region

  • North America led global demand with a 42.6% revenue share in 2025, supported by hyperscale campus investments exceeding USD 50 billion annually.
  • Asia-Pacific is forecast to post the highest regional growth at a 16.8% CAGR through 2035 within the data center server market.


Market Size and Forecast (2021–2035)

Market Research Future's sizing model integrates primary interviews with OEM executives, quarterly shipment data from supply-chain intelligence providers, and capital-expenditure disclosures from the ten largest cloud-service operators. Historical figures (2021–2024) reflect actual shipments; 2025 values are estimated from trailing four-quarter run rates; and the 2026–2035 forecast applies a calibrated CAGR of 14.9%, validated against component roadmaps and announced facility pipelines.
Data Center Server Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Generative-AI training infrastructure scaling +3.8% Global Short-term (≤2 yr)
Hyperscale campus expansion (100 kW+ racks) +2.9% North America, APAC Medium-term (2–4 yr)
Sovereign-AI and data-residency mandates +2.2% Europe, MEA Medium-term (2–4 yr)
Liquid-cooling adoption for high-density servers +1.8% Global Short-term (≤2 yr)
Edge-AI and distributed inference deployments +1.5% APAC, North America Long-term (≥4 yr)
5G core network virtualization on commercial servers +1.1% APAC, Europe Medium-term (2–4 yr)
Open-compute hardware standardization +0.9% North America, Europe Long-term (≥4 yr)


Generative-AI Training Infrastructure Scaling

Training clusters for large-language models have expanded from a few thousand GPUs in 2022 to over 100,000 accelerators in a single fabric by 2025. The capital intensity that is reshaping the data center server market is exemplified by Microsoft's disclosed USD 80 billion AI-infrastructure budget for fiscal 2025 [4]. The compute requirement of each next-generation foundation model is approximately triple that of its antecedent, resulting in a compounding hardware procurement cycle that reduces server refresh intervals from five years to under three.


Hyperscale Campus Expansion

Between 2024 and 2026, Amazon Web Services, Google Cloud, and Meta collectively allocated over USD 150 billion in cumulative data-center capital expenditure. Campus designs are becoming increasingly centered on GPU-dense racks that exceed 80 kW per cabinet [6]. As a result of this change, OEMs are compelled to rethink power distribution and thermal management at the chassis level, which results in premium-priced server configurations that increase the average selling prices of data center servers.


Sovereign-AI and Data-Residency Mandates

The European Union's AI Act, combined with France's EUR 2.5 billion national AI strategy and Saudi Arabia's Vision 2030 technology pillar, requires that sensitive training workloads remain within national borders [1]. These regulations are fragmenting server demand away from centralized public-cloud regions and generating new procurement channels for on-premises GPU clusters. The data center server market benefits from duplicated infrastructure buildouts that would not occur under a purely cloud-native deployment model.

Liquid-Cooling Adoption

Rack power densities have outpaced the thermal capacity of traditional raised-floor air-cooling systems. By 2025, an estimated 18% of new server deployments incorporated some form of direct-to-chip or rear-door liquid cooling, up from under 5% in 2022 [7]. The shift adds USD 800–1,200 per server in cooling-integration costs, which flows through to OEM revenue within the data center server market.


Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
High-bandwidth memory supply constraints –1.9% Global Short-term (≤2 yr)
Semiconductor export controls and trade tensions –1.4% APAC, North America Medium-term (2–4 yr)
Power grid capacity limitations for new campuses –1.1% Europe, North America Long-term (≥4 yr)
Skilled workforce shortages in data center operations –0.8% Global Medium-term (2–4 yr)
Rising rare-earth material costs for server magnetics –0.5% Global Long-term (≥4 yr)


High-Bandwidth Memory Supply Constraints

HBM3E production remains concentrated among two manufacturers—SK Hynix and Samsung—creating a structural bottleneck that constrains GPU server assembly volumes. Lead times for HBM-equipped accelerator modules stretched to 40–50 weeks through 2025, forcing smaller cloud operators to delay deployment schedules and limiting the addressable shipment volume within the data center server market [5].

Semiconductor Export Controls

U.S. Commerce Department restrictions on advanced AI chip exports to China—tightened in October 2023 and again in late 2024—reduced the addressable market for NVIDIA and AMD data-center GPUs in the world's second-largest server market. While Chinese OEMs are accelerating domestic accelerator development, near-term gaps in performance and software ecosystems restrain overall spending growth in the data center server market in the Asia-Pacific region [16].

Power Grid Capacity Limitations

Utility interconnection queues in Northern Virginia, Dublin, and Singapore now exceed 36 months, delaying campus energization timelines. The International Energy Agency estimates that global data-center electricity consumption could reach 945 TWh by 2030, straining grid infrastructure and introducing permitting risk that slows facility—and by extension, server—deployment in the data center server market [11].


Data Center Server Market Opportunities

Edge-AI Server Deployments in Manufacturing and Retail

Industrial IoT applications and real-time computer-vision workloads are generating demand for ruggedized, compact servers deployed at the network edge. This segment of the data center server market could unlock USD 18–22 billion in incremental revenue by 2032 as factories, warehouses, and retail chains deploy inference hardware closer to data sources.

Server-as-a-Service and Consumption-Based Procurement

Consumption-based financing models allow mid-tier enterprises to access GPU compute without large capital outlays. This business-model shift expands the addressable buyer base for the data center server market beyond traditional hyperscalers and colocation operators, bringing financial-services firms and healthcare providers into the direct-procurement channel.


Open-Compute and Disaggregated Hardware Architectures

Open Compute Project and Open19 standards reduce vendor lock-in and lower total cost of ownership by 15–20%. As these specifications mature, they create opportunities for second-tier OEMs and contract manufacturers to gain share in the data center server market against incumbent proprietary vendors.

AI-Inference Monetization Platforms

Cloud providers are layering inference-as-a-service pricing atop server infrastructure, transforming capital assets into recurring revenue streams. This model drives continuous fleet refreshes, as providers must deploy the latest silicon to maintain competitive latency benchmarks—generating sustained hardware demand across the data center server market through 2035.


Data Center Server Market Future Outlook

Autonomous Data Center Operations

By the early 2030s, AI-driven orchestration platforms will manage workload placement, thermal regulation, and predictive hardware maintenance with minimal human intervention. Operators investing in digital-twin simulations of their server fleets today will capture 10–15% efficiency gains in the data center server market through reduced unplanned downtime and optimized power utilization [14].

Silicon Diversification and Chiplet Architectures

The CPU and GPU duopoly is fragmenting. Custom silicon from cloud hyperscalers—AWS Graviton, Google TPU, Microsoft Maia—alongside RISC-V-based designs from startups, will reshape the competitive structure of the data center server market by 2030. Chiplet-based packaging allows operators to mix compute, memory, and networking dies, lowering per-socket costs by an estimated 20–25% relative to monolithic designs [13].

Sustainability and Carbon-Neutral Server Deployments

The Science Based Targets initiative has committed more than 100 data-center operators to net-zero Scope 2 emissions by 2035. Achieving these targets requires not only renewable energy procurement but also AI-optimized servers for machine learning workloads that maximize compute output per watt. Server OEMs embedding lifecycle carbon tracking into firmware will gain preference in procurement evaluations across the data center server market [11].

Photonic Interconnects and Composable Infrastructure

Co-packaged optics and silicon-photonic links promise to eliminate copper bottlenecks within server clusters by the 2032–2034 timeframe. The data center server market stands to benefit from composable architectures that disaggregate CPU, GPU, and memory pools across photonic fabrics, allowing operators to allocate resources dynamically without physical re-cabling [15].


Regional Market Share Analysis

Region Key Metric Primary Investment Themes
North America 42.6% share (2025) Hyperscale AI campuses, sovereign cloud contracts
Europe USD 27.66 Billion (2025) GDPR compliance, EU Chips Act, sustainability
Asia-Pacific 16.8% CAGR (2026–2035) Cloud-first national strategies, 5G core build-out
South America USD 4.12 Billion (2025) Nearshore data centers, fintech infrastructure
Middle East & Africa 15.7% CAGR (2026–2035) Vision 2030, sovereign-AI clusters, subsea cable landings
Total USD 117.70 Billion (2025)

The data center server market displays pronounced regional variation. North America dominates on absolute spending, Asia-Pacific leads on growth velocity, and Europe is carving out a distinct demand profile shaped by regulatory requirements. Emerging regions in South America and the Middle East & Africa remain smaller but are accelerating from low bases.


North America

Country Key Metric Key Driver
United States 78.4% of regional share Hyperscale AI campus expansion in Virginia, Texas, Oregon
Canada USD 4.85 Billion (2025) Government cloud modernization and AI research hubs
Mexico 13.6% CAGR (2026–2035) Nearshore colocation for North American enterprises


The United States continues to anchor the data center server market, with Northern Virginia's "Data Center Alley" alone absorbing more than 3 GW of committed IT load. Canada's federal government allocated CAD 2.4 billion for shared-services cloud migration through 2027, while Mexico's Querétaro and Monterrey corridors attract cross-border colocation tenants seeking lower power costs [6].

Europe

Country Key Metric Key Driver
Germany 22.1% of regional share Industrial cloud for automotive and manufacturing
United Kingdom USD 5.18 Billion (2025) Financial-services private cloud and AI labs
France 15.8% CAGR (2026–2035) EUR 2.5 billion national AI strategy
Italy USD 1.95 Billion (2025) Digital transformation in public administration
Spain 14.2% CAGR (2026–2035) Submarine cable hub growth in Barcelona and Bilbao
Nordic Countries 18.3% of regional share Renewable-powered hyperscale campuses
Russia USD 1.40 Billion (2025) Import substitution and domestic server manufacturing
Rest of Europe 12.5% CAGR (2026–2035) CEE cloud adoption acceleration


European demand for the data center server market is tightly linked to the EU AI Act's requirement that high-risk AI systems maintain auditable compute provenance within EU jurisdiction. The Nordic cluster—led by Sweden and Finland—continues to attract hyperscale facilities that leverage sub-arctic cooling and low-cost hydroelectric power, keeping energy costs 30–40% below continental averages [1].

Asia-Pacific

Country Key Metric Key Driver
China 38.7% of regional share Domestic AI accelerator development and cloud expansion
India 19.2% CAGR (2026–2035) Digital India program and MeitY cloud-first directives
Japan USD 6.40 Billion (2025) Enterprise AI adoption and semiconductor reshoring
South Korea 16.5% CAGR (2026–2035) K-Cloud initiative and AI semiconductor strategy
ASEAN USD 4.10 Billion (2025) Indonesia's National Data Center; Singapore capacity caps
Rest of Asia-Pacific 15.9% CAGR (2026–2035) Australia, New Zealand digital infrastructure upgrades


Asia-Pacific represents the fastest-growing frontier for the data center server market. India's Ministry of Electronics and IT has set a target of 20 GW of data-center capacity by 2030, more than tripling its 2024 installed base. Japanese enterprises are investing heavily in on-premises AI compute as part of broader digital-transformation roadmaps anchored by the Society 5.0 initiative [10].

South America

Country Key Metric Key Driver
Brazil 64.3% of regional share São Paulo and Rio de Janeiro colocation corridors
Argentina 12.8% CAGR (2026–2035) Fintech growth and government digitization
Rest of South America USD 0.72 Billion (2025) Chile's renewable-powered data center projects


Brazil dominates the South American data center server market, with São Paulo hosting Latin America's densest interconnection ecosystem. Cloud-service providers are establishing local availability zones to serve financial-services workloads subject to Banco Central do Brasil data-residency rules [17].

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 29.8% of regional share NEOM smart-city compute and Vision 2030
UAE USD 1.52 Billion (2025) Dubai and Abu Dhabi AI hub ambitions
South Africa 13.9% CAGR (2026–2035) Cape Town and Johannesburg subsea cable landings
Egypt USD 0.44 Billion (2025) Government cloud migration and smart-village programs
Rest of MEA 14.7% CAGR (2026–2035) East African connectivity and data sovereignty laws


Middle East & Africa is an emerging growth pocket for the data center server market. Saudi Arabia's Public Investment Fund committed USD 40 billion to AI-related infrastructure, including sovereign GPU clusters. The UAE's Abu Dhabi-based Technology Innovation Institute operates one of the region's largest AI training facilities, sourcing high-density server configurations from global OEMs [1].


Data Center Server Market By Region, 2025-2035

Data Center Server Market Segmentation

By Tier Type

Segment Key Metric Primary Demand Driver
Tier 1 and 2 USD 18.20 Billion (2025) SME virtualization and branch-office hosting
Tier 3 52.8% share (2025) Balanced redundancy for enterprise workloads
Tier 4 19.0% CAGR (2026–2035) Mission-critical AI inference requiring 99.995% uptime


Tier 3 facilities dominate the data center server market because they offer concurrent maintainability—allowing hardware swaps without service interruption—at a lower build cost than Tier 4. The Tier 4 segment is growing fastest as financial institutions and government agencies deploying real-time AI inference demand fault-tolerant environments with fully redundant power and cooling paths.

By Data Center Size

Segment Key Metric Primary Demand Driver
Small 8.4% share (2025) On-premises enterprise and edge sites
Medium USD 15.50 Billion (2025) Regional colocation providers
Large 13.7% CAGR (2026–2035) National cloud regions and HPC clusters
Hyperscale 54.2% share (2025) AI training campuses and public-cloud regions


Hyperscale campuses account for the majority of server procurement value within the data center server market. These facilities, typically exceeding 50 MW of IT load, benefit from volume purchasing power that reduces per-unit server costs by 25–35% relative to enterprise buyers.

By Data Center Type

Segment Key Metric Primary Demand Driver
Colocation 50.5% share (2025) Multi-tenant hosting and interconnection services
Enterprise (On-Premises) USD 22.80 Billion (2025) Regulated industries with strict data-sovereignty rules
Hyperscaler / Cloud Operator 19.0% CAGR (2026–2035) Public-cloud capacity expansion and AI-as-a-service


Colocation providers hold the largest share of the data center server market by operator type, serving as the physical host for enterprises that prefer capital-light IT strategies. Hyperscaler and cloud-service operators are the fastest-growing buyer segment, with announced capital-expenditure pipelines exceeding USD 200 billion through 2027.

By Form Factor

Segment Key Metric Primary Demand Driver
Half-Height Blades 58.3% share (2025) High-density enterprise and cloud deployments
Full-Height Blades USD 24.70 Billion (2025) GPU-accelerated AI training racks
Quarter-Height / Micro-Blades 16.4% CAGR (2026–2035) Modular edge and micro-data-center installations


Half-height blades remain the workhorse of the data center server market, offering the best balance of compute density and serviceability. Quarter-height and micro-blade designs are gaining traction in distributed edge environments where physical space constraints demand ultra-compact form factors.

By Application / Workload

Segment Key Metric Primary Demand Driver
AI and Machine Learning 40.8% share (2025) LLM training, inference-at-scale, generative AI
Virtualization and Private Cloud 16.2% CAGR (2026–2035) Legacy modernization and hybrid-cloud strategies
High-Performance Computing USD 14.90 Billion (2025) Scientific simulation, weather modeling, genomics
General Enterprise and Web Hosting 11.5% share (2025) Traditional IT workloads and SaaS backends


AI and machine-learning workloads have become the single largest application segment in the data center server market, surpassing virtualization for the first time in 2024. The training of frontier models with trillions of parameters requires clusters of thousands of interconnected GPU servers, creating procurement cycles that dwarf traditional enterprise refresh volumes.


Competitive Benchmarking

The data center server market exhibits medium concentration, with the top five vendors accounting for an estimated 52–58% of global revenue. The Herfindahl-Hirschman Index sits in the 900–1,100 range, indicating a moderately competitive structure where scale advantages in supply-chain management and thermal engineering differentiate leaders from second-tier assemblers.

Company Est. Revenue Share Range Key Offerings Strategic Positioning
Dell Technologies ~12–15% PowerEdge rack and blade platforms Broadest enterprise portfolio with integrated liquid-cooling options
Hewlett Packard Enterprise ~10–13% ProLiant and Cray EX supercomputer nodes Hybrid-cloud convergence via GreenLake consumption model
Lenovo ~8–11% ThinkSystem and Neptune liquid-cooling servers Price-competitive HPC and AI server configurations
Inspur ~7–10% NF-series AI servers and cloud-optimized racks Dominant China-market position and aggressive APAC expansion
Super Micro Computer ~6–9% GPU SuperServers and liquid-cooled AI platforms Fastest time-to-market for new accelerator integration
Cisco Systems ~4–6% UCS blade and rack servers Unified computing with embedded networking fabric
IBM ~3–5% Power10 and LinuxONE enterprise servers Mainframe-grade security for regulated workloads
Huawei Technologies ~3–5% FusionServer and Atlas AI platforms Vertically integrated chipsets for non-U.S. markets
Fujitsu ~2–4% PRIMERGY and Fugaku-derived HPC servers Strong Japan and European public-sector positioning
NVIDIA ~2–4% DGX and HGX reference server platforms AI-training reference architecture defining OEM designs


Recent News & Developments


  • NVIDIA (January 2025): Announced the Blackwell Ultra B300 GPU platform at CES, delivering a 2.5× inference throughput improvement over previous-generation Hopper architecture [8].


  • Super Micro Computer (September 2024): Opened a 600,000-square-foot manufacturing facility in Malaysia dedicated to liquid-cooled AI server assembly for Asia-Pacific customers [20].
  • European Commission (July 2024): Published the European Data Center Energy Efficiency Code of Conduct, setting mandatory PUE thresholds for new facilities that influence server thermal-design specifications across the data center server market [11].
  • Inspur (May 2024): Released the NF5688G7 AI server optimized for China's domestic AI accelerators, positioning for sovereign-compute demand in restricted-export markets [16].
  • Lenovo (February 2024): Expanded its Neptune liquid-cooling portfolio to cover 90% of its ThinkSystem rack server lineup, responding to growing customer demand for high-density deployments [7].
  • AWS (December 2023): Introduced the Graviton4 custom ARM processor, delivering 30% higher compute performance per watt and reshaping custom-silicon procurement strategies in the data center server market [13].


Data Center Server Market Report Scope

Parameter Detail
Market Scope Global data center server market covering hardware revenue by tier type, data center size, data center type, form factor, application, and geography
Study Period 2021–2035
CAGR 14.9% (2026–2035)
Base Year Market Size USD 117.70 Billion (2025)
Forecast Start Market Size USD 135.10 Billion (2026)
Forecast End Market Size USD 471.90 Billion (2035)
Fastest Growing Region Asia-Pacific (16.8% CAGR)
Fastest Growing Segment Tier 4 facilities (19.0% CAGR)
Companies Profiled Dell Technologies, HPE, Lenovo, Inspur, Supermicro, Cisco, IBM, Huawei, Fujitsu, NVIDIA
Valuation Currency USD Billion

FAQs

What cooling technologies are reshaping server procurement decisions in the data center server market?
Direct-to-chip liquid cooling now handles rack densities above 80 kW, displacing traditional raised-floor air systems. Procurement teams increasingly require rear-door heat exchangers or immersion-ready chassis as baseline specifications.
How do sovereign-AI mandates affect server sourcing strategies?
EU and Gulf-state governments require AI training on domestic infrastructure, pushing operators toward on-premises GPU clusters. This fragments supply chains and creates premium pricing for locally assembled server configurations within the data center server market.
What role does high-bandwidth memory availability play in server refresh cycles?
HBM3E scarcity forces hyperscalers into multiyear component contracts, shortening planning horizons. Facilities securing early allocations gain 12–18 months of deployment advantage over competitors relying on spot procurement.
How should mid-tier enterprises approach GPU server investments in the data center server market?
Leasing GPU capacity through cloud or colocation partners reduces upfront capital risk. Enterprises processing fewer than 500 daily inference jobs rarely justify owning dedicated accelerator hardware.
What supply-chain risks should buyers monitor through 2030?
Advanced packaging capacity at TSMC and Samsung remains the primary bottleneck for AI accelerators. Geopolitical restrictions on semiconductor exports add further delivery uncertainty across the data center server market.
How are open-compute designs changing vendor selection criteria?
OCP and Open19 standards let operators source interchangeable components from multiple vendors, eroding OEM lock-in. Buyers benefit from 15–20% lower total cost of ownership versus proprietary rack architectures.
What financing models are emerging for large-scale server deployments?
Server-as-a-service and consumption-based contracts now cover 20–25% of hyperscale procurements. These models shift expenditure from capital to operational budgets, improving balance-sheet flexibility during rapid expansion.    
Author
Author Author Profile Nirmit Biswas LinkedIn Senior Research Analyst
With 5+ years of expertise in Market Intelligence and Strategic Research, Nirmit Biswas specializes in ICT, Semiconductors, and BFSI. Backed by an MBA in Financial Services and a Computer Science foundation, Nirmit blends technical depth with business acumen. He has successfully led 100+ projects for global enterprises and startups, including Amazon, Cisco, L&T and Huawei, delivering market estimations, competitive benchmarking, and GTM strategies. His focus lies in transforming complex data into clear, actionable insights that drive growth, innovation, and investment decisions. Recognized for bridging engineering innovation with executive strategy, Nirmit helps businesses navigate dynamic markets with confidence.
Co-Author Co-Author Profile Aarti Dhapte LinkedIn AVP - Research
A consulting professional focused on helping businesses navigate complex markets through structured research and strategic insights. I partner with clients to solve high-impact business problems across market entry strategy, competitive intelligence, and opportunity assessment. Over the course of my experience, I have led and contributed to 100+ market research and consulting engagements, delivering insights across multiple industries and geographies, and supporting strategic decisions linked to $500M+ market opportunities. My core expertise lies in building robust market sizing, forecasting, and commercial models (top-down and bottom-up), alongside deep-dive competitive and industry analysis. I have played a key role in shaping go-to-market strategies, investment cases, and growth roadmaps, enabling clients to make confident, data-backed decisions in dynamic markets.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.