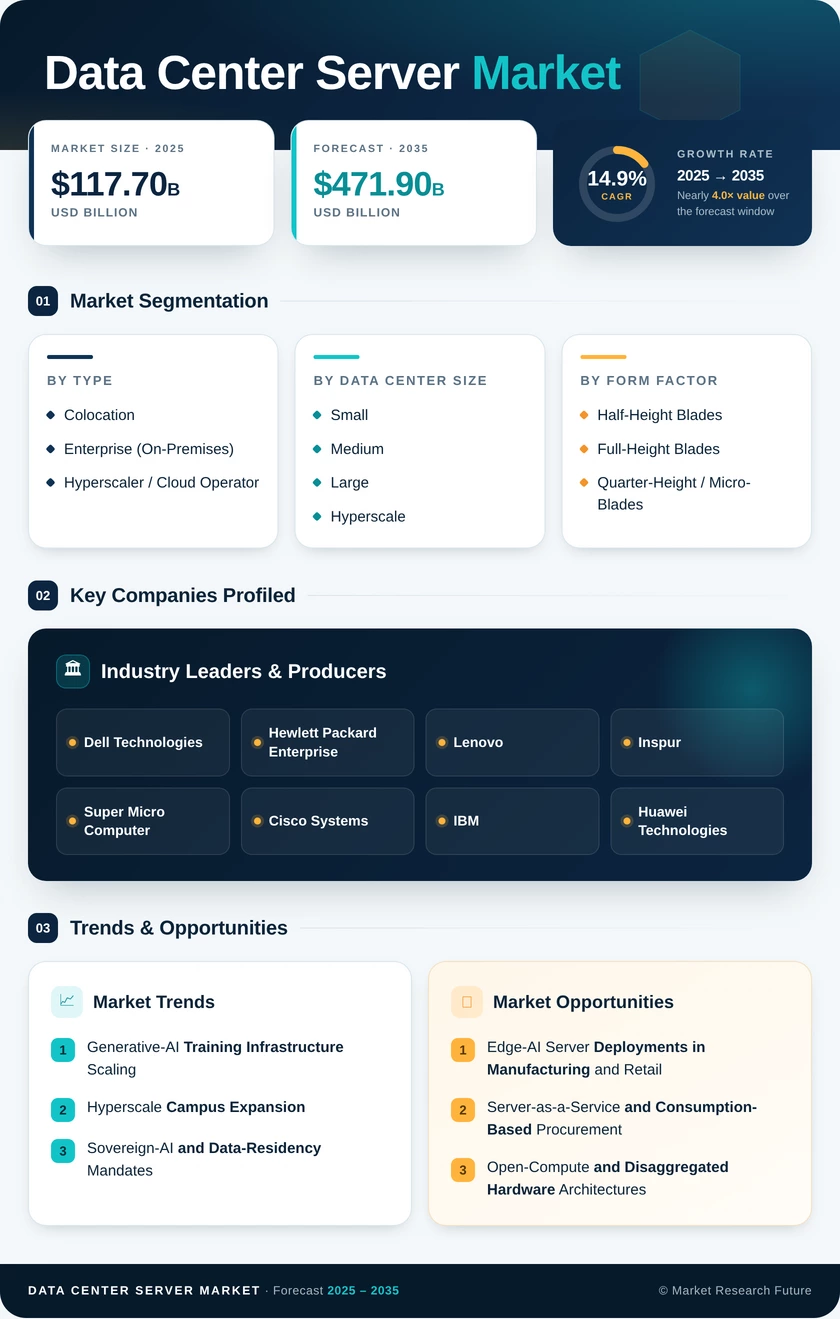
Data Center Server Market (2026 - 2035)

ID: MRFR/ICT/27713-HCR 100 Pages Nirmit Biswas Last Updated: September 17, 2026
Data Center Server Market Size, Share and Research Report By Tier Type (Tier 1 and 2, Tier 3, Tier 4), By Data Center Size (Small, Medium, Large, Hyperscale), By Data Center Type (Colocation, Enterprise (On-Premises), Hyperscaler / Cloud Operator), By Form Factor (Half-Height Blades, Full-Height Blades, Quarter-Height / Micro-Blades), By Application / Workload (AI and Machine Learning, Virtualization and Private Cloud, High-Performance Computing, General Enterprise and Web Hosting) and By Regional (North America, Europe, South America, South Africa, Asia Pacific, Middle East and Africa) - Industry Forecast to 2035.
Data Center Server Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)14.9%
2025 Market SizeUSD 117.70 Billion
2026 Market SizeUSD 135.10 Billion
2035 Market SizeUSD 471.90 Billion
Key Players
Dell Technologies
Hewlett Packard Enterprise
Lenovo
Inspur
Super Micro Computer
Cisco Systems
Opportunities
  • Edge-AI Server Deployments in Manufacturing and Retail
  • Server-as-a-Service and Consumption-Based Procurement
  • Open-Compute and Disaggregated Hardware Architectures
  1. 1 Market Overview |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Market Summary & Key Takeaways
  3. 3 Market Dynamics |
    1. 3.1 Market Drivers Analysis | |
      1. 3.1.1 Generative-AI Training Infrastructure Scaling | |
      2. 3.1.2 Hyperscale Campus Expansion (100 kW+ Racks) | |
      3. 3.1.3 Sovereign-AI and Data-Residency Mandates | |
      4. 3.1.4 Liquid-Cooling Adoption for High-Density Servers | |
      5. 3.1.5 Edge-AI and Distributed Inference Deployments | |
      6. 3.1.6 5G Core Network Virtualization on Commercial Servers | |
      7. 3.1.7 Open-Compute Hardware Standardization |
    2. 3.2 Market Restraints Analysis | |
      1. 3.2.1 High-Bandwidth Memory Supply Constraints | |
      2. 3.2.2 Semiconductor Export Controls and Trade Tensions | |
      3. 3.2.3 Power Grid Capacity Limitations for New Campuses | |
      4. 3.2.4 Skilled Workforce Shortages in Data Center Operations | |
      5. 3.2.5 Rising Rare-Earth Material Costs for Server Magnetics |
    3. 3.3 Market Opportunity Analysis | |
      1. 3.3.1 Edge-AI Server Deployments in Manufacturing and Retail | |
      2. 3.3.2 Server-as-a-Service and Consumption-Based Procurement | |
      3. 3.3.3 Emerging-Market Data Center Build-Outs | |
      4. 3.3.4 Open-Compute and Disaggregated Hardware Architectures | |
      5. 3.3.5 AI-Inference Monetization Platforms |
    4. 3.4 Industry Value Chain Analysis |
    5. 3.5 Porter's Five Forces Analysis
  4. 4 Global Data Center Server Market Size & Forecast (2021–2035) |
    1. 4.1 Historical Market Size (2021–2025) |
    2. 4.2 Current & Forecast Market Size (2026–2035) |
    3. 4.3 Market Size by Revenue (USD Billion) |
    4. 4.4 Year-over-Year Growth Analysis
  5. 5 Segmentation Analysis |
    1. 5.1 By Tier Type | |
      1. 5.1.1 Tier 1 and 2 | |
      2. 5.1.2 Tier 3 | |
      3. 5.1.3 Tier 4 |
    2. 5.2 By Data Center Size | |
      1. 5.2.1 Small | |
      2. 5.2.2 Medium | |
      3. 5.2.3 Large | |
      4. 5.2.4 Hyperscale |
    3. 5.3 By Data Center Type | |
      1. 5.3.1 Colocation | |
      2. 5.3.2 Enterprise (On-Premises) | |
      3. 5.3.3 Hyperscaler / Cloud Operator |
    4. 5.4 By Form Factor | |
      1. 5.4.1 Half-Height Blades | |
      2. 5.4.2 Full-Height Blades | |
      3. 5.4.3 Quarter-Height / Micro-Blades |
    5. 5.5 By Application / Workload | |
      1. 5.5.1 AI and Machine Learning | |
      2. 5.5.2 Virtualization and Private Cloud | |
      3. 5.5.3 High-Performance Computing | |
      4. 5.5.4 General Enterprise and Web Hosting
  6. 6 Regional Analysis |
    1. 6.1 North America | |
      1. 6.1.1 United States | |
      2. 6.1.2 Canada | |
      3. 6.1.3 Mexico |
    2. 6.2 Europe | |
      1. 6.2.1 Germany | |
      2. 6.2.2 United Kingdom | |
      3. 6.2.3 France | |
      4. 6.2.4 Italy | |
      5. 6.2.5 Spain | |
      6. 6.2.6 Nordic Countries | |
      7. 6.2.7 Russia | |
      8. 6.2.8 Rest of Europe |
    3. 6.3 Asia-Pacific | |
      1. 6.3.1 China | |
      2. 6.3.2 India | |
      3. 6.3.3 Japan | |
      4. 6.3.4 South Korea | |
      5. 6.3.5 ASEAN | |
      6. 6.3.6 Rest of Asia-Pacific |
    4. 6.4 South America | |
      1. 6.4.1 Brazil | |
      2. 6.4.2 Argentina | |
      3. 6.4.3 Rest of South America |
    5. 6.5 Middle East & Africa | |
      1. 6.5.1 Saudi Arabia | |
      2. 6.5.2 UAE | |
      3. 6.5.3 South Africa | |
      4. 6.5.4 Egypt | |
      5. 6.5.5 Rest of MEA
  7. 7 Competitive Landscape |
    1. 7.1 Market Share Analysis (2025) |
    2. 7.2 Competitive Benchmarking Matrix |
    3. 7.3 Company Profiles | |
      1. 7.3.1 Dell Technologies | |
      2. 7.3.2 Hewlett Packard Enterprise | |
      3. 7.3.3 Lenovo | |
      4. 7.3.4 Inspur | |
      5. 7.3.5 Super Micro Computer | |
      6. 7.3.6 Cisco Systems | |
      7. 7.3.7 IBM | |
      8. 7.3.8 Huawei Technologies | |
      9. 7.3.9 Fujitsu | |
      10. 7.3.10 NVIDIA
  8. 8 Future Outlook & Strategic Recommendations (2026–2035) |
    1. 8.1 Autonomous Data Center Operations |
    2. 8.2 Silicon Diversification and Chiplet Architectures |
    3. 8.3 Sustainability and Carbon-Neutral Server Deployments |
    4. 8.4 Photonic Interconnects and Composable Infrastructure
  9. 9 Recent Developments & News
  10. 10 Frequently Asked Questions (FAQs)
  11. 11 Report Scope & Methodology |
    1. 11.1 Study Period & Base Year |
    2. 11.2 Data Sources & Citations |
    3. 11.3 Abbreviations
  12. 1 LIST OF TABLES |
  13. TABLE 1 Global Data Center Server Market Size & Forecast, by Revenue (USD Billion), 2021–2035 |
  14. TABLE 2 Global Data Center Server Market — Year-over-Year Growth Analysis, 2021–2035 |
  15. TABLE 3 Market Driver Impact Analysis, 2026–2035 |
  16. TABLE 4 Market Restraint Impact Analysis, 2026–2035 |
  17. TABLE 5 Global Data Center Server Market Size, by Tier Type, 2021–2035 (USD Billion) |
  18. TABLE 6 Global Data Center Server Market Size, by Data Center Size, 2021–2035 (USD Billion) |
  19. TABLE 7 Global Data Center Server Market Size, by Data Center Type, 2021–2035 (USD Billion) |
  20. TABLE 8 Global Data Center Server Market Size, by Form Factor, 2021–2035 (USD Billion) |
  21. TABLE 9 Global Data Center Server Market Size, by Application / Workload, 2021–2035 (USD Billion) |
  22. TABLE 10 Global Data Center Server Market Size, by Region, 2021–2035 (USD Billion) |
  23. TABLE 11 North America Data Center Server Market Size, by Country, 2021–2035 (USD Billion) |
  24. TABLE 12 Europe Data Center Server Market Size, by Country, 2021–2035 (USD Billion) |
  25. TABLE 13 Asia-Pacific Data Center Server Market Size, by Country, 2021–2035 (USD Billion) |
  26. TABLE 14 South America Data Center Server Market Size, by Country, 2021–2035 (USD Billion) |
  27. TABLE 15 Middle East & Africa Data Center Server Market Size, by Country, 2021–2035 (USD Billion) |
  28. TABLE 16 Competitive Benchmarking Matrix — Global Data Center Server Market, 2025 |
  29. TABLE 17 Company Profiles — Key Players, Global Data Center Server Market |
  30. TABLE 18 Recent Developments & Strategic Announcements, 2023–2025 |
  31. TABLE 19 Report Scope and Methodology Summary |
  32. TABLE 20 Detailed Sources and Citations
  33. 2 LIST OF FIGURES |
  34. FIGURE 1 Data Center Server Market Dynamics — Drivers, Restraints, and Opportunities |
  35. FIGURE 2 Industry Value Chain Analysis — Data Center Server Market |
  36. FIGURE 3 Porter's Five Forces Analysis — Data Center Server Market |
  37. FIGURE 4 Global Data Center Server Market Size Trend (USD Billion), 2021–2035 |
  38. FIGURE 5 Data Center Server Market Share, by Tier Type, 2025 |
  39. FIGURE 6 Data Center Server Market Share, by Data Center Size, 2025 |
  40. FIGURE 7 Data Center Server Market Share, by Data Center Type, 2025 |
  41. FIGURE 8 Data Center Server Market Share, by Form Factor, 2025 |
  42. FIGURE 9 Data Center Server Market Share, by Application / Workload, 2025 |
  43. FIGURE 10 Data Center Server Market Share, by Region, 2025 |
  44. FIGURE 11 North America Data Center Server Market Size, by Country, 2021–2035 |
  45. FIGURE 12 Europe Data Center Server Market Size, by Country, 2021–2035 |
  46. FIGURE 13 Asia-Pacific Data Center Server Market Size, by Country, 2021–2035 |
  47. FIGURE 14 South America Data Center Server Market Size, by Country, 2021–2035 |
  48. FIGURE 15 Middle East & Africa Data Center Server Market Size, by Country, 2021–2035 |
  49. FIGURE 16 Competitive Landscape — Market Share Distribution, 2025 |
  50. FIGURE 17 Competitive Positioning Map — Key Players, Data Center Server Market

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
Tier TypeTier 1 and 2, Tier 3, Tier 4Tier 3Tier 4
Data Center SizeSmall, Medium, Large, HyperscaleHyperscaleHyperscale
Data Center TypeColocation, Enterprise (On-Premises), Hyperscaler / Cloud OperatorColocationHyperscaler / Cloud Operator
Form FactorHalf-Height Blades, Full-Height Blades, Quarter-Height / Micro-BladesHalf-Height BladesQuarter-Height / Micro-Blades
Application / WorkloadAI and Machine Learning, Virtualization and Private Cloud, HPC, General Enterprise and Web HostingAI and Machine LearningVirtualization and Private Cloud
GeographyNorth America, Europe, Asia-Pacific, South America, Middle East & AfricaNorth AmericaAsia-Pacific


Market Segmentation Overview

By Tier Type

Sub-SegmentKey Trend
Tier 1 and 2Cost-effective hosting for SMEs and non-critical workloads with basic redundancy
Tier 3Dominant tier for enterprise deployments requiring concurrent maintainability
Tier 4Fastest adoption for AI inference workloads demanding 99.995% uptime SLAs


Tier 3 remains the default choice for most enterprise and colocation deployments because it provides N+1 redundancy without the cost premium of a 2N architecture. Tier 4 is gaining ground rapidly as real-time AI inference applications in finance and healthcare require uninterruptible compute availability.

By Data Center Size

Sub-SegmentKey Trend
SmallOn-premises edge deployments and branch-office micro-data centers
MediumRegional colocation hubs serving mid-market enterprise tenants
LargeNational cloud regions and government HPC installations
HyperscaleAI training campuses exceeding 50 MW with volume-optimized procurement.


Hyperscale campuses continue to absorb the largest share of global server shipments, driven by multi-billion-dollar capital programs at AWS, Microsoft Azure, and Google Cloud. The small-facility segment is experiencing renewed interest as edge-AI use cases require inference hardware on factory floors and retail locations.

By Data Center Type

Sub-SegmentKey Trend
ColocationMulti-tenant environments offering interconnection and hybrid-cloud on-ramps
Enterprise (On-Premises)Regulated industries maintaining direct hardware control for compliance
Hyperscaler / Cloud OperatorFastest-growing buyer category driven by AI-as-a-service revenue models


Colocation operators serve as critical intermediaries in the server market, providing the physical infrastructure that enterprises use to deploy hybrid-cloud strategies without building their own facilities. Hyperscaler and cloud-service operators are the growth engine, with their GPU server procurement volumes exceeding traditional enterprise purchases by a widening margin.

By Form Factor

Sub-SegmentKey Trend
Half-Height BladesIndustry-standard density for general-purpose and cloud workloads
Full-Height BladesGPU-accelerated configurations for AI training requiring maximum PCIe bandwidth
Quarter-Height / Micro-BladesUltra-compact designs for modular and containerized edge deployments


Half-height blade servers remain the backbone of enterprise and cloud data centers because they balance compute density with standardized serviceability. Quarter-height and micro-blade designs are the fastest-growing form factor, propelled by the proliferation of edge-AI installations where physical space is at a premium.

By Application / Workload

Sub-SegmentKey Trend
AI and Machine LearningDominant application driving GPU-dense server procurement at scale
Virtualization and Private CloudLegacy enterprise modernization and hybrid-cloud migration
High-Performance ComputingScientific simulation, genomics, and national research infrastructure
General Enterprise and Web HostingTraditional IT workloads and SaaS application backends


AI and machine-learning workloads have overtaken virtualization as the primary revenue driver in the server market, reflecting the capital-intensive nature of large-language-model training and inference deployment. Virtualization and private-cloud platforms remain the fastest-growing application segment by CAGR as enterprises accelerate legacy-to-cloud migration initiatives.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.