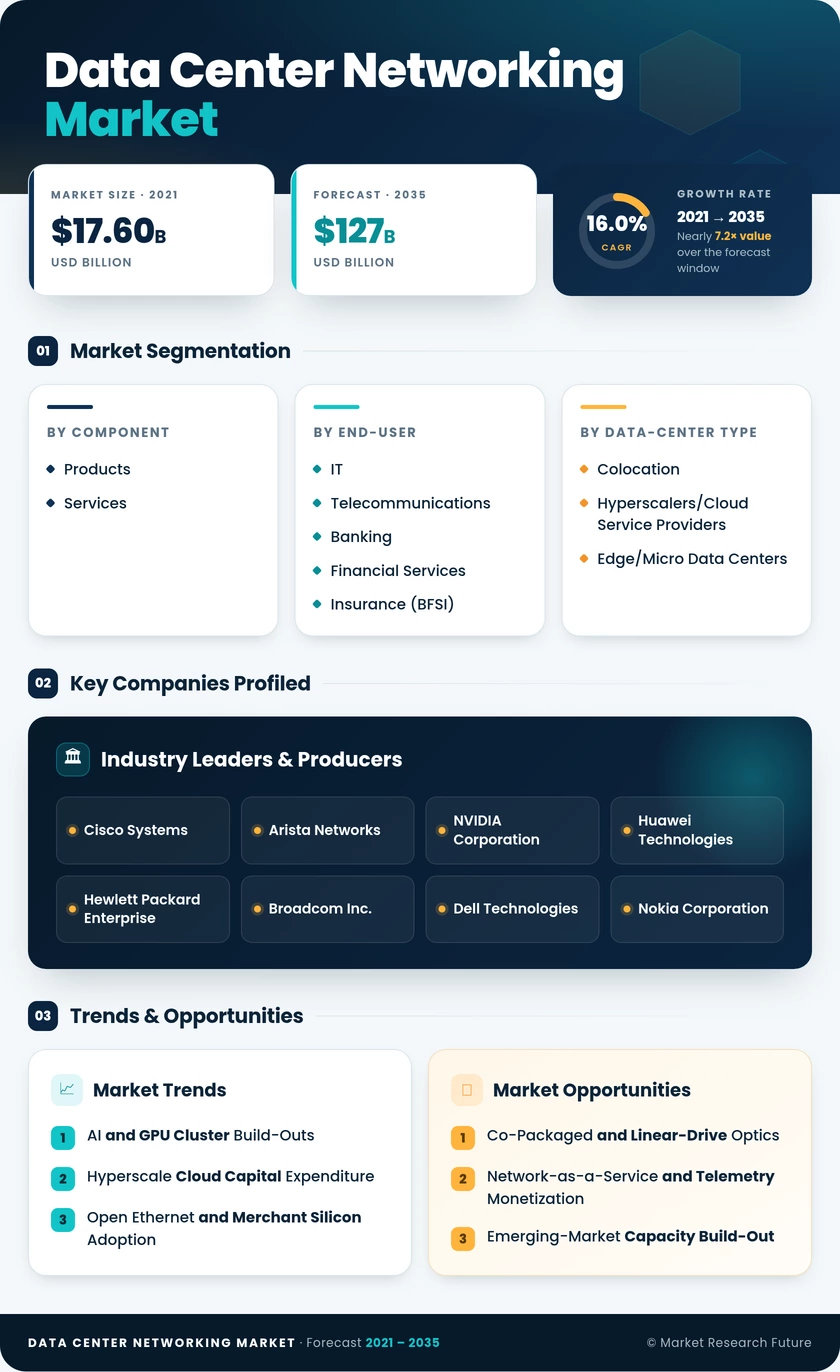
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|
| By Component | Products; Services | Products — 69.9% share | Services — 16.5% CAGR |
| By End-User | IT and Telecommunications; Banking, Financial Services and Insurance (BFSI); Government and Defense; Media and Entertainment; Healthcare and Life Sciences; Manufacturing and Industrial; Other End-Users | IT and Telecommunications — 33.4% share | Manufacturing and Industrial — 16.8% CAGR |
| By Data-Center Type | Colocation; Hyperscalers/Cloud Service Providers; Edge/Micro Data Centers | Colocation — 52.6% share | Hyperscalers/Cloud Service Providers — 17.8% CAGR |
| By Bandwidth | Less than 10 GbE; 25-40 GbE; 50-100 GbE; Greater than 100 GbE | 50-100 GbE — 35.6% share | Greater than 100 GbE — 16.6% CAGR |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East and Africa | North America — 38.5% share | Asia-Pacific — 18.4% CAGR |
Market Segmentation Overview
| Sub-Segment | Key Trend |
|---|
| Products | Ethernet switches and optical interconnects migrating to 400G, 800G, and 1.6T |
| Services | Managed fabric operations and AI cluster integration projects expanding |
Products lead with a 69.9% share because every AI cluster requires a fresh layer of Ethernet switches, optical interconnects, and SDN controllers. Services grow fastest at a 16.5% CAGR as lossless-fabric tuning and day-two operations outstrip in-house skills. Installation and Integration and Managed Network Services capture most of that incremental spend, shifting value toward recurring contracts.
| Sub-Segment | Key Trend |
|---|
| IT and Telecommunications | Cloud, CDN, and telco core fabrics upgraded for AI traffic |
| Banking, Financial Services and Insurance (BFSI) | Low-latency trading and resilient multi-site designs |
| Government and Defense | Sovereign and classified compute with domestic sourcing |
| Media and Entertainment | Streaming and generative content production |
| Healthcare and Life Sciences | Imaging, genomics, and clinical AI workloads |
| Manufacturing and Industrial | Plant-floor micro data centers for edge AI |
| Other End-Users | Retail, education, and energy digitization |
IT and Telecommunications holds a 33.4% share, reflecting the concentration of cloud and carrier spending on high-radix fabrics. Manufacturing and Industrial grows fastest at a 16.8% CAGR because machine vision and predictive maintenance require deterministic, on-site networking. BFSI and Government and Defense remain steady buyers, valuing latency and supply-chain assurance over price.
| Sub-Segment | Key Trend |
|---|
| Colocation | Retrofits for high-density racks and tenant-controlled network domains |
| Hyperscalers/Cloud Service Providers | Non-blocking AI fabrics with factory pre-cabled topologies |
| Edge/Micro Data Centers | Compact, remotely managed switching for latency-sensitive sites |
Colocation dominates with a 52.6% share as enterprises rent capacity but keep control of their switching layers. Hyperscalers/Cloud Service Providers grow fastest at a 17.8% CAGR, since AI training clusters demand leaf-spine-superspine fabrics at unprecedented port counts. Edge/Micro Data Centers add a distinct demand pool centered on zero-touch provisioning and ruggedized hardware.
| Sub-Segment | Key Trend |
|---|
| Less than 10 GbE | Confined to management, out-of-band, and branch networks |
| 25-40 GbE | Persisting in mid-sized enterprise server access |
| 50-100 GbE | Enterprise refresh to cloud-grade leaf-spine designs |
| Greater than 100 GbE | 400G leaf and 800G spine adoption in AI clusters |
50-100 GbE leads with a 35.6% share as enterprises standardize on 100G access and aggregation. Greater than 100 GbE grows fastest at a 16.6% CAGR, driven by 51.2 Tbps and 102.4 Tbps switch silicon that makes 400G and 800G ports economical. Less than 10 GbE continues to shrink as a share of new shipments, limited to management networks.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA