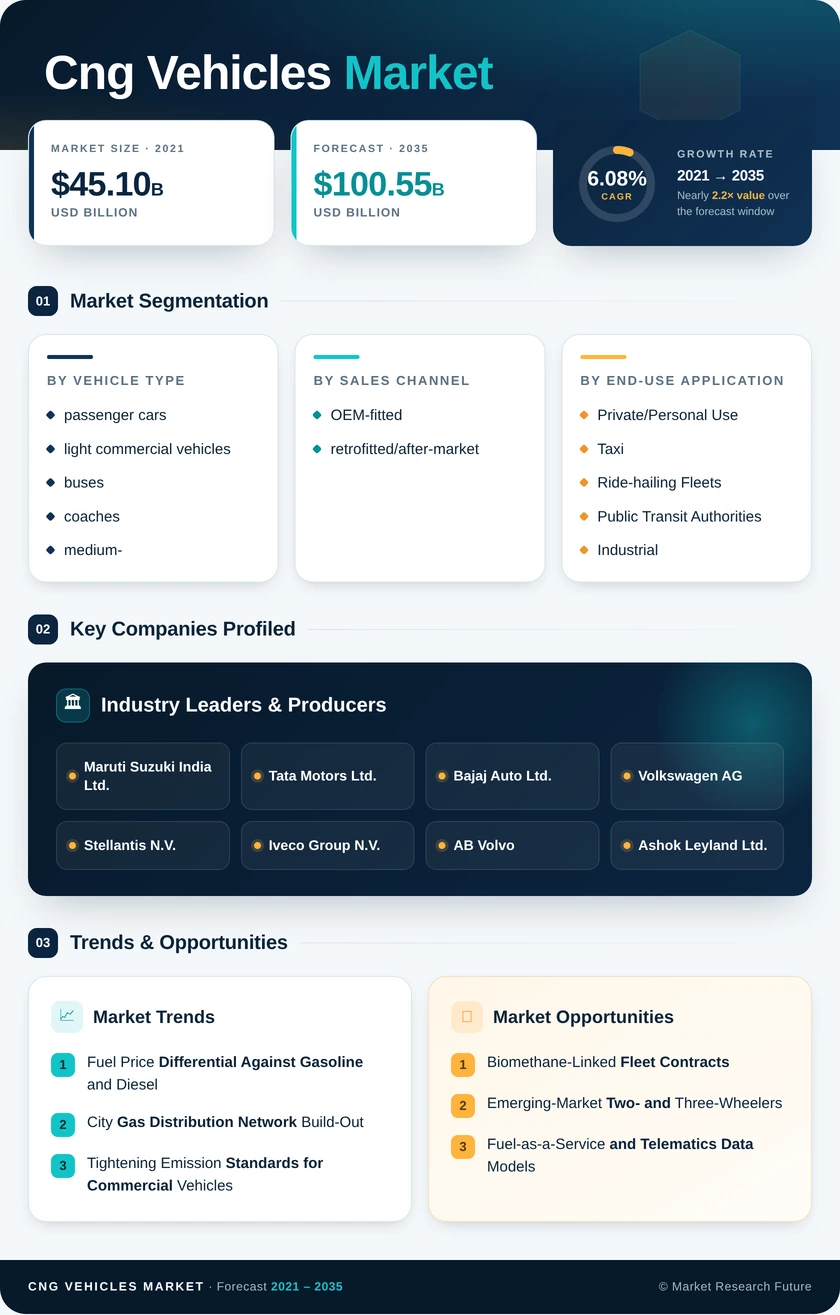
CNG vehicles Market (2026 - 2035)

ID: MRFR/AT/5035-CR 188 Pages Shubham Munde Last Updated: September 29, 2026
CNG Vehicles Market Research Report By Vehicle Type (Passenger Cars, Light Commercial Vehicles, Buses and Coaches, Medium- and Heavy-Duty Trucks, Two- and Three-Wheelers), By Sales Channel (OEM-Fitted, Retrofitted/After-Market), By End-Use Application (Private/Personal Use, Taxi and Ride-Hailing Fleets, Public Transit Authorities, Industrial and Utility Fleets), By Cylinder Type (Type I, Type II, Type III, Type IV) - Forecast to 2035
CNG vehicles Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.08%
2025 Market SizeUSD 55.94 Billion
2035 Market SizeUSD 100.55 Billion
Key Players
Maruti Suzuki India Ltd.
Tata Motors Ltd.
Bajaj Auto Ltd.
Volkswagen AG
Stellantis N.V.
Iveco Group N.V.
Opportunities
  • Biomethane-Linked Fleet Contracts
  • Emerging-Market Two- and Three-Wheelers
  • Fuel-as-a-Service and Telematics Data Models
  1. 1 Market Summary | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Vehicle Type | |
    2. 2.2 By Sales Channel | |
    3. 2.3 By End-use Application | |
    4. 2.4 By Cylinder Type | |
    5. 2.5 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Forecast Market Size (2026–2035) | |
    3. 3.3 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Fuel Price Differential Against Gasoline and Diesel | |
    2. 4.2 City Gas Distribution Network Build-Out | |
    3. 4.3 Tightening Emission Standards for Commercial Vehicles | |
    4. 4.4 Public Transit Procurement Funding | |
    5. 4.5 Renewable Natural Gas and Biomethane Supply | |
    6. 4.6 OEM Factory-Fitted Portfolio Expansion | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Accelerating Battery-Electric Adoption | |
    2. 5.2 Sparse Refuelling Coverage Outside Core Markets | |
    3. 5.3 Natural Gas Price Volatility | |
    4. 5.4 Cylinder Weight, Cost, and Packaging | |
    5. 5.5 Tailpipe-Only CO2 Accounting | |
  6. 6 Opportunities | |
    1. 6.1 Biomethane-Linked Fleet Contracts | |
    2. 6.2 Emerging-Market Two- and Three-Wheelers | |
    3. 6.3 Fuel-as-a-Service and Telematics Data Models | |
    4. 6.4 Certified Retrofit Programmes for Ageing Fleets | |
    5. 6.5 Composite Storage for Heavy-Duty Trucks | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 South America | | |
      1. 7.2.1 Brazil | | |
      2. 7.2.2 Argentina | | |
      3. 7.2.3 Rest of South America | |
    3. 7.3 Europe | | |
      1. 7.3.1 Germany | | |
      2. 7.3.2 UK | | |
      3. 7.3.3 France | | |
      4. 7.3.4 Italy | | |
      5. 7.3.5 Spain | | |
      6. 7.3.6 Nordic Countries | | |
      7. 7.3.7 Russia | | |
      8. 7.3.8 Rest of Europe | |
    4. 7.4 Asia-Pacific | | |
      1. 7.4.1 China | | |
      2. 7.4.2 India | | |
      3. 7.4.3 Japan | | |
      4. 7.4.4 South Korea | | |
      5. 7.4.5 ASEAN | | |
      6. 7.4.6 Rest of Asia-Pacific | |
    5. 7.5 Middle East and Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of MEA | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Biomethane Becomes the Core Value Proposition | |
    2. 8.2 Coexistence with Electrification | |
    3. 8.3 Digital Fleet Operations | |
    4. 8.4 Multi-Fuel and Hydrogen-Ready Platforms | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Vehicle Type | | |
      1. 9.1.1 passenger cars | | |
      2. 9.1.2 light commercial vehicles | | |
      3. 9.1.3 buses and coaches | | |
      4. 9.1.4 medium- and heavy-duty trucks | | |
      5. 9.1.5 two- and three-wheelers | |
    2. 9.2 By Sales Channel | | |
      1. 9.2.1 OEM-fitted | | |
      2. 9.2.2 retrofitted/after-market | |
    3. 9.3 By End-use Application | | |
      1. 9.3.1 Private/Personal Use | | |
      2. 9.3.2 Taxi and Ride-hailing Fleets | | |
      3. 9.3.3 Public Transit Authorities | | |
      4. 9.3.4 Industrial and Utility Fleets | |
    4. 9.4 By Cylinder Type | | |
      1. 9.4.1 Type I | | |
      2. 9.4.2 Type II | | |
      3. 9.4.3 Type III | | |
      4. 9.4.4 Type IV | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Maruti Suzuki India Ltd. | | |
      2. 10.3.2 Tata Motors Ltd. | | |
      3. 10.3.3 Bajaj Auto Ltd. | | |
      4. 10.3.4 Hyundai Motor Company | | |
      5. 10.3.5 Volkswagen AG | | |
      6. 10.3.6 Stellantis N.V. | | |
      7. 10.3.7 Iveco Group N.V. | | |
      8. 10.3.8 AB Volvo | | |
      9. 10.3.9 Ashok Leyland Ltd. | | |
      10. 10.3.10 Toyota Motor Corporation | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global CNG Vehicles Market Size and Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Driver Impact Analysis, 2026–2035 | |
  17. TABLE 3 Restraints Impact Analysis, 2026–2035 | |
  18. TABLE 4 Regional Summary, 2025–2035 | |
  19. TABLE 5 North America CNG Vehicles Market, by Country, 2021–2035 (USD Billion) | |
  20. TABLE 6 South America CNG Vehicles Market, by Country, 2021–2035 (USD Billion) | |
  21. TABLE 7 Europe CNG Vehicles Market, by Country, 2021–2035 (USD Billion) | |
  22. TABLE 8 Asia-Pacific CNG Vehicles Market, by Country, 2021–2035 (USD Billion) | |
  23. TABLE 9 Middle East and Africa CNG Vehicles Market, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 Global CNG Vehicles Market, by Vehicle Type, 2021–2035 (USD Billion) | |
  25. TABLE 11 Global CNG Vehicles Market, by Sales Channel, 2021–2035 (USD Billion) | |
  26. TABLE 12 Global CNG Vehicles Market, by End-use Application, 2021–2035 (USD Billion) | |
  27. TABLE 13 Global CNG Vehicles Market, by Cylinder Type, 2021–2035 (USD Billion) | |
  28. TABLE 14 Competitive Benchmarking Matrix, 2025 | |
  29. TABLE 15 Report Scope and Methodology | |
  30. TABLE 16 Detailed Sources and Citations | | LIST OF FIGURES | |
  31. FIGURE 1 Market Dynamics Overview — Drivers, Restraints, and Opportunities | |
  32. FIGURE 2 Industry Value Chain Analysis | |
  33. FIGURE 3 Porter's Five Forces Analysis | |
  34. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) | |
  35. FIGURE 5 Market Share by Vehicle Type, 2025 | |
  36. FIGURE 6 Market Share by Sales Channel, 2025 | |
  37. FIGURE 7 Market Share by End-use Application, 2025 | |
  38. FIGURE 8 Market Share by Cylinder Type, 2025 | |
  39. FIGURE 9 Regional Market Share, 2025 | |
  40. FIGURE 10 Regional Growth Comparison, 2026–2035 CAGR | |
  41. FIGURE 11 Competitive Landscape — Estimated Revenue Share Ranges, 2025 | |
  42. FIGURE 12 Recent Strategic Developments Timeline, 2024–2025

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Vehicle Typepassenger cars; light commercial vehicles; buses and coaches; medium- and heavy-duty trucks; two- and three-wheelerspassenger cars (59.9% share)buses and coaches (8.5% CAGR)
By Sales ChannelOEM-fitted; retrofitted/after-marketOEM-fitted (70.4% share)retrofitted/after-market (8.8% CAGR)
By End-use ApplicationPrivate/Personal Use; Taxi and Ride-hailing Fleets; Public Transit Authorities; Industrial and Utility FleetsPrivate/Personal Use (43.8% share)Public Transit Authorities (8.7% CAGR)
By Cylinder TypeType I; Type II; Type III; Type IVType I (57.3% share)Type IV (11.2% CAGR)
By RegionNorth America; South America; Europe; Asia-Pacific; Middle East and AfricaAsia-Pacific (58.4% share)Middle East and Africa (8.7% CAGR)


Market Segmentation Overview

By Vehicle Type

Sub-SegmentKey Trend
passenger carsLow-premium bi-fuel compacts from Indian and Italian brands
light commercial vehiclesCNG vans for urban last-mile delivery
buses and coachesTransit agencies buy gas buses with grant funding
medium- and heavy-duty trucks15-litre gas engines open long-haul routes
two- and three-wheelersFirst CNG motorcycles and gas auto-rickshaws in South Asia


Passenger cars lead with a 59.9% share because Indian automakers sell factory-fitted CNG compacts at a small premium over petrol versions. Buses and coaches grow fastest at an 8.5% CAGR, since transit agencies can add depot compressors at far lower cost than high-power charging. Heavy trucks remain a smaller but rising niche as new gas engines match diesel output.

By Sales Channel

Sub-SegmentKey Trend
OEM-fittedWarranty-backed factory integration with dealer servicing
retrofitted/after-marketType-approved kits with multi-year engine warranties


OEM-fitted vehicles hold a 70.4% share as buyers and lenders prefer factory warranties and predictable resale values. Retrofitted/after-market conversions grow faster at an 8.8% CAGR because certified kits and dealer installation now address earlier reliability concerns. Conversion activity clusters where station corridors already exist, letting operators convert during scheduled maintenance.

By End-use Application

Sub-SegmentKey Trend
Private/Personal UseCost-driven commuting in bi-fuel subcompacts
Taxi and Ride-hailing FleetsHigh-mileage operators capture fast payback
Public Transit AuthoritiesBulk procurement and fixed-route depot refuelling
Industrial and Utility FleetsOn-site gas at ports, mines, and logistics parks


Private/Personal Use leads with a 43.8% share, driven by households in India and South America seeking lower fuel bills. Public Transit Authorities grow fastest at an 8.7% CAGR because fixed routes and depot refuelling let agencies spread compressor costs over high annual mileage. Taxi and Ride-hailing Fleets sit between the two, relying on dense urban stations for quick payback.

By Cylinder Type

Sub-SegmentKey Trend
Type IAll-metal steel tanks remain the low-cost default
Type IIMetal hoop-wrapped units trim weight at moderate cost
Type IIIFull composite with metal liner for commercial use
Type IVPolymer-liner composite for maximum payload


Type I all-metal cylinders lead with a 57.3% share because their low cost suits passenger cars and conversion kits. Type IV polymer-liner composite cylinders grow fastest at an 11.2% CAGR as bus and truck operators trade higher tank prices for weight savings and extra payload. Type II and Type III designs fill the middle ground where buyers balance cost against weight.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.