Cinnamon Market (2026 - 2035)

Cinnamon Market Size, Share, Industry Trend & Analysis Research Report By Type (Cassia, Ceylon), By Form (Whole Quills and Sticks, Ground and Powder, Oil and Oleoresin, Standardized Extracts), By Application (Food & Beverage Processing, Retail / Household Culinary, Nutraceuticals & Pharmaceuticals, Cosmetics & Personal Care, Animal Feed & Other), By Nature (Organic, Conventional), By Distribution Channel (B2B / Industrial Direct, Modern Trade & Supermarkets, Traditional Trade, E-commerce / DTC), By Geography (North America, Europe, Asia-Pacific, South America, Middle East & Africa) - Forecast to 2035

ID: MRFR/Agri/39851-HCR 128 Pages Snehal Singh, Harshita Gorde Last Updated: September 17, 2026
Cinnamon Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.31%
2025 Market SizeUSD 1.31 Billion
2035 Market SizeUSD 2.29 Billion
Key Players
Olam Food Ingredients
Synthite Industries
Mane Kancor Ingredients
Döhler Group
Givaudan
Silvermill Group
Opportunities
  • Pharmaceutical-Grade Extract Manufacturing
  • Leaf Oil and Antimicrobial Applications
  • African Origin Development

Cinnamon Market Summary

The Cinnamon Market reached USD 1.31 billion in 2025 and opens the forecast window at USD 1.44 billion in 2026, expanding to USD 2.29 billion by 2035 at a 5.31% CAGR. Two catalysts anchor that trajectory. Sri Lanka's protected geographical indication for Ceylon cinnamon, registered by the European Commission in 2022, converted an origin claim into an enforceable premium [7]. Alongside it, the EU deforestation-free products regulation pushed importers to fund farm-level traceability across smallholder plots that had never been mapped [6]. Both shifted value from undifferentiated bulk trade toward documented, gradeable lots.

The difference is most obvious in the processing. Sun-dried quills graded by sight are being replaced by machine-vision grading, moisture-regulated tunnel drying and water-extracted oleoresin lines that keep volatile oil content within tight bands. Beverage and dairy-alternative formulators are now specifying standardized extracts in place of synthetic vanillin, a switch that reprices the same raw bark two to four times higher. The Spices Board of India has reported ongoing capital deployment for its 2024–25 export cycle for cleaning, steam-sterilization and grinding capacity [9].


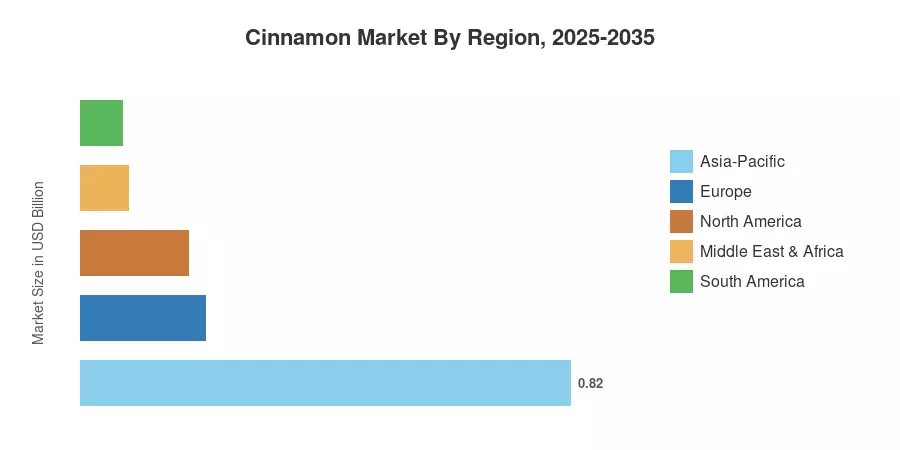
Asia-Pacific (62.5%) is driven by Sri Lankan, Indonesian, Vietnamese and Chinese supply that clears cassia and Ceylon grades [2]. Middle East & Africa quickest on a 6.3% CAGR as Madagascar and Tanzania ramp up certified organic volume [22]. Europe, with 15.8% of the bloc, ranks second, where coumarin ceilings turn the choice of grade into a compliance decision rather than a taste preference [5]. The Cinnamon Market promotes best-documented provenance, not cheapest shipping, out to 2035.


Key Report Takeaways

• By Type

  • Cassia grades command 71.4% of the Cinnamon Market by type, sustained by bakery and industrial flavour volume.


• By Application

  • Food and beverage processing absorbs 54.2% of global consumption
  • Nutraceutical and pharmaceutical use expands at a 7.1% CAGR through 2035
  • Cosmetics and personal care applications contributed USD 0.08 billion in 2025

• By Geography

  • Asia-Pacific anchors the Cinnamon Market with a 62.5% share in 2025
  • Middle East & Africa posts the fastest regional CAGR at 6.3%
  • North America accounted for USD 0.18 billion in 2025


Market Size and Forecast (2021–2035)

Estimates are based on HS 0906 customs flows from ITC Trade Map, national plantation statistics for Sri Lanka, Indonesia, Vietnam and China, and wholesale price series triangulated against World Bank commodities benchmarks [2][3][10][17]. Then, in the volume-to-value conversion, grade-weighted pricing is used rather than blended averages. This is relevant in the Cinnamon Market, as Ceylon quills and Indonesian korintji trade at dramatically different levels.
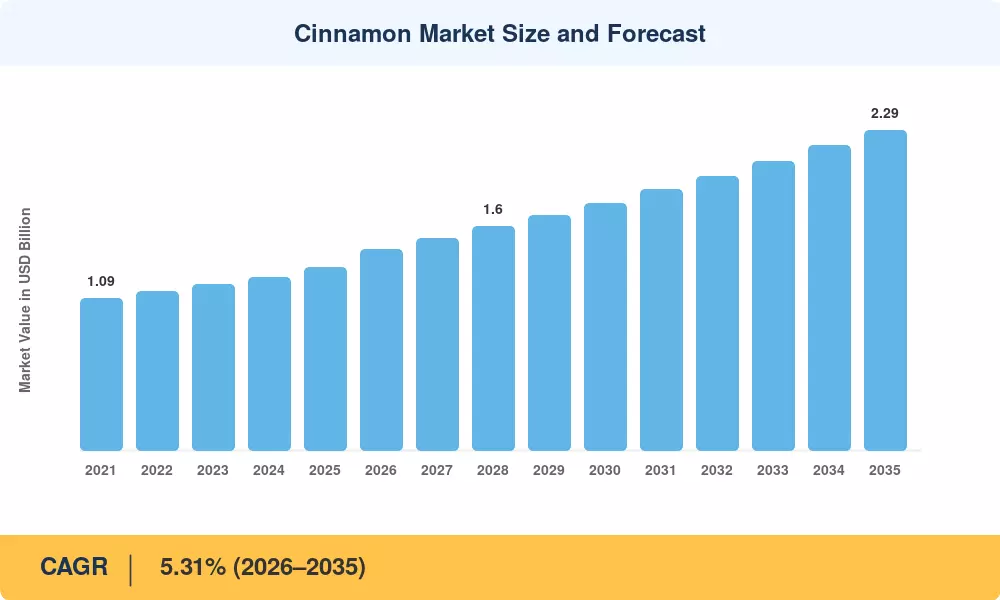
Cinnamon Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Metabolic-health nutraceutical demand +1.1 North America, Europe, GCC Medium-term (2–4 yr)
Clean-label reformulation in processed food +0.9 Europe, North America Short-term (≤2 yr)
Traceability and origin certification premiums +0.7 Global Long-term (≥4 yr)
Functional beverage innovation +0.6 North America, APAC Medium-term (2–4 yr)
E-commerce and direct-to-consumer spice retail +0.5 APAC, North America Short-term (≤2 yr)
Foodservice recovery across Asia and the Gulf +0.4 APAC, MEA Short-term (≤2 yr)
Antimicrobial use in personal care +0.3 Europe, APAC Long-term (≥4 yr)


Metabolic-Health Positioning Reframes a Culinary Spice

Supplement demand rests on polyphenol content rather than aroma. WHO counts more than 800 million adults living with diabetes worldwide, a population that supports sustained interest in adjunct botanicals [25]. The US National Center for Complementary and Integrative Health continues to characterize the clinical evidence as mixed, which keeps marketers on structure-function language rather than disease claims [16]. That regulatory caution has not slowed volume: standardized bark extracts now clear procurement specifications that would have failed a decade ago, and the Cinnamon Market prices them accordingly.

Clean-Label Substitution in Processed Food

Reformulation teams replacing synthetic flavourings need a natural input that survives thermal processing without off-notes. Water-extracted oleoresin delivers both flavour and antioxidative stability in oat and almond dairy lines, and Codex spice standards give buyers a common specification language across jurisdictions [12]. Bakery, cereal, and confectionery accounts drive the bulk of this pull.

Traceability as a Pricing Mechanism

Compliance with EU deforestation-free rules obliges operators to hold geolocation data for every plot supplying a consignment [6]. Rainforest Alliance's 2020 standard adds farm-management and income requirements that cooperatives increasingly bundle into a single audit [19]. Exporters who digitized early now negotiate multi-year contracts at premiums that fragmented sellers cannot access.

Channel Shift Toward Direct Retail

Origin-branded quills sold through marketplace platforms bypass three intermediary layers. UNCTAD documents how digital commodity channels compress margin capture toward producing countries when logistics and payment rails are in place [18]. Sri Lankan and Vietnamese cooperatives have used this route to move small, high-grade lots at retail rather than bulk pricing.


Restraints Impact Analysis

Restraint weightings are directional estimates of drag on realized growth. They quantify friction intensity, not a subtraction that reconciles to the forecast CAGR.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Coumarin regulatory ceilings on cassia grades −0.8 Europe Medium-term (2–4 yr)
Climate volatility and monsoon yield shocks −0.6 APAC Long-term (≥4 yr)
Peeler labour shortage and smallholder fragmentation −0.5 Sri Lanka, Indonesia Long-term (≥4 yr)
Adulteration and quality-assurance cost burden −0.4 Global Short-term (≤2 yr)
Fermentation-derived cinnamaldehyde substitution −0.3 North America, Europe Long-term (≥4 yr)


Coumarin Ceilings Divide the Grade Structure

European flavouring rules set maximum coumarin levels in specified foodstuffs, and cassia carries far more of the compound than Ceylon bark [5]. EFSA's tolerable daily intake assessment underpins those limits and shapes how bakery manufacturers formulate seasonal products [8]. The practical result is a two-tier Cinnamon Market: buyers serving EU retail either pay up for true cinnamon or restrict cassia inclusion rates, and both routes raise landed cost.

Supply Concentration Meets Climate Exposure

Roughly four origins supply the overwhelming majority of traded bark [2]. FAO production series show how a single disrupted harvest season in Sri Lanka or Sumatra propagates into global price within two quarters [1]. Replanting cycles run five to seven years before commercial peeling, so short-term supply elasticity is close to zero.

Labour Scarcity in Bark Peeling

Peeling remains a manual craft skill with limited mechanization. Sri Lanka's export authority has flagged an ageing peeler cohort and weak youth entry as a structural constraint on Ceylon volume growth [3]. Wage inflation feeds directly into quill pricing because no substitute process yields comparable presentation grades.


Cinnamon Market Opportunities

Pharmaceutical-Grade Extract Manufacturing

Standardized extracts with certified coumarin thresholds and defined cinnamaldehyde assay open supplement and topical formulation accounts that bulk spice traders cannot serve. ISO specification frameworks give processors a defensible technical baseline . Margin capture here runs several multiples above quill trading.

Leaf Oil and Antimicrobial Applications

Leaf distillation currently treats a co-product as waste in many origins. Eugenol-rich leaf oil has documented preservative and personal-care uses, and capturing it lifts revenue per hectare without additional planting . Processors adding distillation alongside bark handling convert an agronomic by-product into a second income line.

African Origin Development

Madagascar and Tanzania offer certified organic acreage with lower incumbency and favourable investment terms; Madagascar's investment authority has actively courted agribusiness capital into spice value chains [22]. Buyers seeking supply diversification away from concentrated Asian origins will fund this expansion, which is why Middle East & Africa carries the fastest regional CAGR in the Cinnamon Market.

Traceability Data as a Product

Farm-level datasets assembled for deforestation compliance have resale value to insurers, certifiers, and brand-side ESG reporting teams. Cooperatives that own the data layer rather than surrendering it to importers can license it repeatedly [6][19]. This is the clearest new business model in an otherwise commodity structure.

Private-Label Premiumization in Retail

Grocery chains in Europe and the Gulf are building origin-designated private-label tiers that carry PGI marks and single-estate provenance [7]. Suppliers with lot-level documentation can win those listings at pricing insulated from spot volatility.


Cinnamon Market Future Outlook

Precision Agronomy and Machine Grading

Leading exporters already deploy GPS harvest mapping and machine-vision sorting that classify quills faster and more consistently than trained graders. IFOAM's global organic survey documents how digital record-keeping has become a prerequisite for certification renewal rather than a differentiator [20]. Cost per audited hectare falls as these systems scale, which gradually brings mid-tier cooperatives into premium channels.

Fermentation-Derived Cinnamaldehyde

Synthetic biology firms are producing cinnamaldehyde at laboratory scale, and commercial economics could turn viable after 2028. Flavour houses would adopt it for cost-sensitive industrial applications where botanical provenance carries no marketing value. Bark demand for whole-spice and clean-label positions stays insulated, but the Cinnamon Market should expect margin compression in the commodity flavour tier.

Deforestation-Free and Carbon-Linked Sourcing

Compliance obligations under EU rules extend beyond a one-time audit into continuous due diligence [6]. Buyers increasingly pair those requirements with soil-carbon and agroforestry claims, since cinnamon grows well in mixed-canopy systems. Estates that document both compliance and sequestration will access contract terms unavailable to conventional suppliers.

Health-Claim Substantiation Tightens

Regulators on both sides of the Atlantic are narrowing the gap between marketing language and clinical evidence. NCCIH's public position reflects genuine uncertainty in the underlying trial data, which means supplement brands face rising substantiation costs [16]. Companies that fund credible trials will consolidate the premium tier of the Cinnamon Market while unsubstantiated claimants exit.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America USD 0.18 billion Supplement formulation, DTC retail, clean-label bakery
Europe 15.8% share Coumarin compliance, PGI sourcing, deforestation traceability
Asia-Pacific 62.5% share Origin processing, grading automation, export consolidation
South America 5.5% CAGR (2026–2035) Bakery reformulation, import substitution
Middle East & Africa 6.3% CAGR (2026–2035) Certified organic acreage, re-export hubs
Total USD 1.31 billion —

Regional performance in the Cinnamon Market splits between origin economies capturing processing value and consuming economies paying for compliance-grade documentation.


North America

Country Share of Region (%) Key Driver
US 78.5 Supplement and functional beverage formulation [16]
Canada 11.2 Clean-label bakery reformulation [12]
Mexico 10.3 Traditional beverage and confectionery use [4]


American demand splits cleanly between culinary volume and health-positioned extract. FDA's food-additive inventory treats cinnamon as generally recognized as safe in conventional use, which keeps formulation risk low for beverage developers [15]. Import statistics tracked through USDA's trade system show steady growth in ground and extract categories relative to whole bark, a signal that value-added processing is moving closer to the consumer [4].

Europe

Country Share of Region (%) Key Driver
Germany 19.8 Bakery and seasonal confectionery compliance [5]
UK 15.4 Retail private-label premium tiers [7]
France 13.1 Organic retail penetration [21]
Italy 10.6 Bakery and dessert manufacturing [12]
Spain 8.2 Foodservice and beverage use [12]
Nordic Countries 9.7 High per-capita seasonal consumption [5]
Russia 8.9 Confectionery and import re-routing [2]
Rest of Europe 14.3 Distribution and re-export flows [2]


European buyers operate under the tightest documentation burden anywhere. Organic production rules under Regulation 2018/848 govern certification equivalence for imported lots, while deforestation-free obligations require geolocation evidence that most smallholder chains lacked as recently as 2023 [6][21]. German and Nordic bakery manufacturers, who consume disproportionate seasonal volume, have responded by contracting directly with certified estates rather than buying through spot markets.

Asia-Pacific

Country Share of Region (%) Key Driver
China 31.6 Cassia production, traditional medicine, food processing [2]
India 24.8 Culinary volume and oleoresin processing capacity [9]
Japan 9.4 Confectionery and functional beverage [2]
South Korea 5.7 Health beverage and supplement formulation [2]
ASEAN 21.3 Indonesian and Vietnamese origin supply [10]
Rest of Asia-Pacific 7.2 Sri Lankan Ceylon export base [3]


The Cinnamon Market in Asia-Pacific is simultaneously the largest consumer and the source of nearly all traded supply. Indonesia's plantation statistics document Cassia vera acreage concentrated in Sumatra, where cooperatives aggregate smallholder output for export [10]. Vietnam's national sector plan targets expanded processing rather than raw bark shipment, aiming to retain value that historically accrued to importers . India's oleoresin extractors, meanwhile, buy imported bark and re-export concentrated product, giving the country a processing role that its production base alone would not support [9].

South America

Country CAGR 2026–2035 (%) Key Driver
Brazil 5.7 Bakery and beverage manufacturing scale [17]
Argentina 5.2 Confectionery and retail spice demand [17]
Rest of South America 5.4 Import distribution growth [2]


Brazilian food manufacturers dominate regional offtake, importing predominantly Indonesian cassia at price points that suit industrial bakery economics. Currency volatility remains the binding constraint on premium grade adoption; when the real weakens, buyers trade down rather than reduce volume. World Bank commodity outlooks flag this substitution pattern across import-dependent food inputs in the region [17].

Middle East & Africa

Country Market Size 2025 (USD B) Key Driver
Saudi Arabia 0.017 Foodservice expansion and beverage culture [17]
UAE 0.014 Re-export hub and premium retail [2]
South Africa 0.010 Retail spice and bakery demand [2]
Egypt 0.009 Traditional culinary and beverage use [2]
Rest of MEA 0.011 Madagascar and Tanzania origin development [22]


Gulf demand is consumption-led while African activity is supply-led, and the combination produces the fastest regional growth rate in the forecast. Dubai's re-export infrastructure lets traders consolidate mixed-origin lots for onward shipment into Europe and South Asia [2]. Madagascar's investment promotion agency has positioned certified organic spice as a priority sector, and the acreage coming into commercial yield after 2028 is the single largest new supply source outside Asia [22].


Cinnamon Market By Region, 2025-2035

Cinnamon Market Segmentation

By Type

Segment Share 2025 (%) Primary Demand Driver
Cassia (C. cassia, C. burmannii, C. loureiroi) 71.4 Industrial bakery and flavour volume
Ceylon (C. verum) 28.6 Coumarin-compliant and premium retail demand


Cassia holds volume leadership because industrial buyers optimize for cost per unit of flavour intensity, and Indonesian and Chinese supply clears reliably at scale [10]. Ceylon's share understates its value contribution — as the Ceylon true cinnamon spice designation gained legal protection in Europe, the price gap between the two types widened rather than converged [7]. Any buyer serving European retail treats type selection as a compliance variable first.

By Form

Segment Market Size 2025 (USD B) Primary Demand Driver
Whole Quills and Sticks 0.55 Retail culinary and foodservice presentation
Ground and Powder 0.48 Bakery, cereal, and beverage manufacturing
Oil and Oleoresin 0.19 Flavour houses and personal care
Standardized Extracts 0.09 Nutraceutical and pharmaceutical formulation


Whole quills retain the largest form share because presentation grade drives consumer price and because origin branding depends on visible quality. Ground product moves faster in volume terms but concentrates adulteration risk, which is why steam-sterilized, origin-sealed powder now commands its own tier [15].

By Application

Segment Share 2025 (%) Primary Demand Driver
Food & Beverage Processing 54.2 Clean-label reformulation across bakery and dairy alternatives
Retail / Household Culinary 21.7 Home baking and origin-branded retail
Nutraceuticals & Pharmaceuticals 14.1 Metabolic-health supplement formulation
Cosmetics & Personal Care 6.3 Antimicrobial and fragrance applications
Animal Feed & Other 3.7 Gut-health additive trials


Industrial processing dominates because a single reformulated product line absorbs more tonnage than thousands of retail packs. Nutraceutical demand grows fastest despite its smaller base, and it pulls a disproportionate share of extract capacity investment [16].

By Nature

Segment CAGR 2026–2035 (%) Primary Demand Driver
Organic 7.4 Certified retail listings and EU import requirements
Conventional 4.9 Industrial cost optimization


By Distribution Channel

Segment Share 2025 (%) Primary Demand Driver
B2B / Industrial Direct 61.8 Contract manufacturing and flavour house procurement
Modern Trade & Supermarkets 18.4 Private-label premium tiers
Traditional Trade 12.9 Emerging-market retail density
E-commerce / DTC 6.9 Origin-branded direct sales


Competitive Benchmarking

Cinnamon Market concentration remains modest. Production is in the hands of hundreds of thousands of smallholders while export and processing consolidate around corporations willing to pay for certification, sterilizing and traceability infrastructure. Estimated top-five revenue share is ~26%, reflecting an HHI much below 500 – structurally fragmented, with pressure to consolidate at the export and extraction stages, not at the farm gate.

Company Est. Revenue Share Range Key Offerings for Cinnamon Market Strategic Positioning
McCormick & Company ~7–10% Branded retail ground and whole spice, foodservice blends Consumer brand equity and North American retail shelf control
Olam Food Ingredients (OFI) ~5–8% Bulk sourcing, sterilized spice, traceable supply programmes Origin-to-shelf integration with farmer sustainability platforms
Synthite Industries ~4–6% Oleoresins, essential oils, natural extracts Largest-scale extraction capacity serving global flavour houses
Mane Kancor Ingredients ~3–5% Standardized extracts, oleoresins, clean-label solutions Technical formulation partnership with F&B manufacturers
Döhler Group ~3–5% Natural flavour systems and beverage compounds Functional beverage and dairy-alternative specialization
Givaudan (Naturex) ~3–4% Botanical extracts and flavour ingredients Premium natural ingredient positioning with R&D depth
Silvermill Group ~2–4% Ceylon quills, cut and sifted grades, value-added packs Sri Lankan vertically integrated export platform
PT Cassia Coop ~2–3% Organic and conventional korintji cassia Indonesian farmer-linked traceable cassia supply
Vinasamex ~2–3% Organic Vietnamese cinnamon, sticks and powder Certified organic export with cooperative sourcing model
Frontier Co-op ~1–3% Organic retail and bulk botanical spice US natural channel and cooperative retail distribution
EOAS Organic (Pvt) Ltd ~1–2% Certified organic Ceylon bark and leaf oil Niche organic Ceylon supply for European buyers


Recent News & Developments

  • European Commission (December 2023): Regulation (EU) 2023/1115 entered into force with due-diligence obligations covering agricultural commodities, prompting importers to map smallholder plots that had never held geolocation records [6].
  • Sri Lanka Export Development Board (March 2024): Launched a peeler training and certification programme aimed at reversing declining entry into the bark-processing workforce, directly addressing a supply constraint on Ceylon volume [3].
  • Spices Board India (August 2024): Published tightened sampling and testing protocols for exported ground spice following international rejections, raising documentation costs but improving buyer confidence in Indian-processed lots [9].
  • Vietnam Ministry of Agriculture and Rural Development (October 2024): Approved a sector development plan prioritizing domestic extraction and packaging capacity over raw bark export, targeting retained value in producing districts .
  • European Commission (December 2024): Agreed a twelve-month application delay for deforestation-free rules, giving smallholder-dependent supply chains additional runway to complete traceability onboarding [6].
  • Madagascar EDBM (February 2025): Opened an agribusiness investment window covering certified organic spice acreage, positioning the island as a diversification origin for European buyers [22].
  • IFOAM Organics International (April 2025): Reported continued expansion in certified organic tropical crop area, with spice categories among the faster-growing segments by certified hectare [20].
  • World Bank (October 2025): Flagged elevated volatility in tropical agricultural commodity pricing, citing weather variability and freight cost swings as compounding factors [17].


Cinnamon Market Report Scope

Parameter Detail
Market Scope Global cinnamon bark, powder, oil, oleoresin, and standardized extract across food, beverage, nutraceutical, cosmetic, and feed applications
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 5.31% (2026–2035)
Market Size Checkpoints USD 1.31 billion (2025); USD 1.44 billion (2026); USD 2.29 billion (2035)
Fastest Growing Segments Standardized extracts (by form); Nutraceuticals & Pharmaceuticals (by application); Organic (by nature)
Companies Profiled 11 leading participants across branded retail, ingredient extraction, and origin export
Valuation Currency USD billion

FAQs

How should procurement teams structure contracts in the Cinnamon Market to hedge coumarin compliance risk?
Specify a maximum coumarin threshold in parts per million as a contractual reject condition, not a target. Pair it with third-party lot testing paid by the seller. This shifts liability upstream where grade selection actually happens [5].
What separates a credible organic supplier from a greenwashed one?
Ask for the certifier's transaction certificate tied to the specific lot, not the operator certificate. Equivalence status under EU organic rules must cover the exporting country. Certificate scope mismatches are the most common audit failure [21].
Which technical specification should buyers cite when comparing Ceylon and cassia lots?
ISO 6539 defines volatile oil content, moisture, and ash limits across grades, giving both parties a neutral reference . Quoting it removes the ambiguity that vague descriptors like "premium" create in dispute resolution.
How much do freight and container economics move landed cost in the Cinnamon Market?
Bark is bulky and light, so containers cube out before hitting weight limits. Freight can represent a meaningful share of landed cost on retail-grade quills. Compressed or cut formats improve container utilization substantially.
What integration challenges arise when adding traceability systems to smallholder supply?
Connectivity gaps and low digital literacy stall onboarding more often than software cost. Successful programmes staff field agents who capture data on behalf of farmers. Budget for two harvest cycles before data quality stabilizes [6].
Where does leaf oil create incremental margin beyond bark?
Distilling leaf material yields eugenol-rich oil sold into personal care and preservative applications. It monetizes biomass already generated during pruning, requiring only distillation capacity rather than new acreage .
What signals should investors track before entering the Cinnamon Market?
Watch replanting acreage in Sri Lanka and Sumatra, since yield responds only after five to seven years. Track certified-hectare growth as a proxy for premium supply. Both lead price by multiple quarters [1][20].    
Author
Author Author Profile Snehal Singh LinkedIn Manager - Research
High acumen in analyzing complex macro & micro markets with more than 6 years of work experience in the field of market research. By implementing her analytical skills in forecasting and estimation into market research reports, she has expertise in Packaging, Construction, and Equipment domains. She handles a team size of 20-25 resources and ensures smooth running of the projects, associated marketing activities, and client servicing.
Co-Author Co-Author Profile Harshita Gorde LinkedIn Research Analyst
Harshita Post graduate MBA in Business Administration from Welingkar Institute, Mumbai and 5 years of experience in the field of product market research. As a Research Analyst, I have cross-domain experience in packaging, and industrial Automation & Equipment. I am currently looking after the research process of packaging, logistics & transportation, and industrial automation & equipment at Market Research Future Reports. My responsibilities at the organization involve handling syndicate and custom reports as well as responding to client inquiries, and organize, co-ordinate with a group of 5 to 6 persons to manage all workflows.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















