Beta Carotene Market (2026 - 2035)

Beta Carotene Market Size, Share, Industry Trend & Analysis Research Report: By Nature (Natural, Synthetic), By Form (Liquid, Powder), By Application (Food & Beverage, Dietary Supplement, Animal Feed, Personal Care & Cosmetics, Pharmaceuticals), By Geography (North America, Europe, Asia-Pacific, South America, Middle East & Africa) - Forecast to 2035.
ID: MRFR/FnB/39827-HCR 100 Pages Sakshi Gupta Last Updated: September 11, 2026
Beta Carotene Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.1%
2025 Market SizeUSD 461.8 Million
2035 Market SizeUSD 835.0 Million
Key Players
dsm-firmenich
BASF SE
Allied Biotech Corporation
Lycored
Kemin Industries
DDW
Opportunities
  • Microencapsulation and Advanced Delivery Technologies
  • Fortification Programs in Sub-Saharan Africa and South Asia
  • Premiumization of Pet Nutrition

Beta Carotene Market Summary

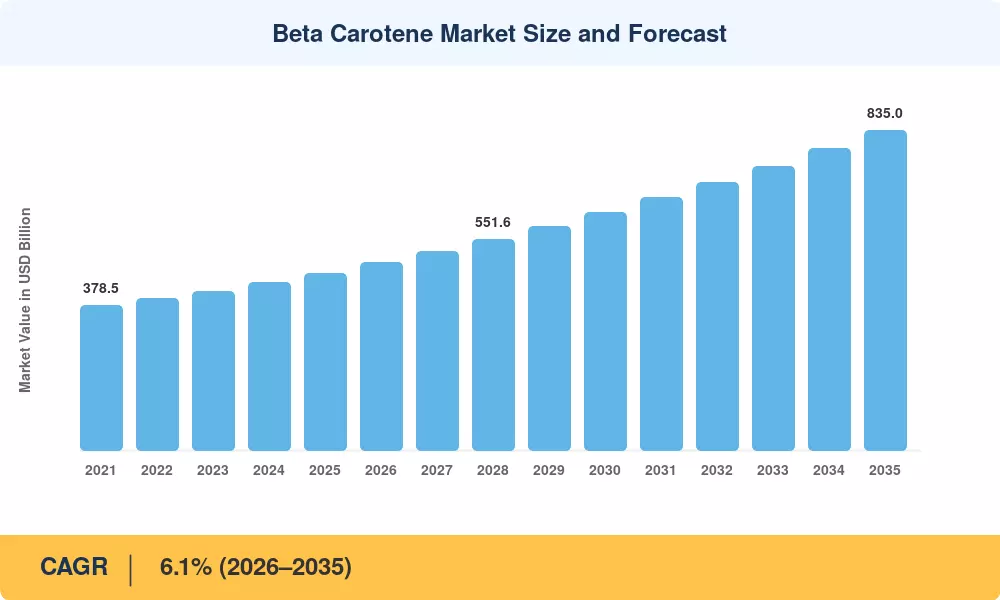
The global beta carotene market reached an estimated USD 461.8 million in 2025 and is projected to grow from USD 490.0 million in 2026 to USD 835.0 million by 2035, registering a CAGR of 6.1% during the forecast period. This expansion is rooted in two converging forces: tightening clean-label regulations across the EU and North America that push food manufacturers toward natural colorants, and the WHO's renewed vitamin A deficiency interventions targeting over 190 million preschool-age children globally [1]. Both catalysts are pulling beta-carotene squarely into mainstream ingredient sourcing strategies.

The ingredient landscape is quietly but decisively shifting. Legacy synthetic colors, many under reformulation pressure from the EU’s updated food additives law (EC No 1333/2008 amendments), are losing shelf space to beta-carotene versions generated from fermentation and algal extracts. Since 2022, investment in Dunaliella salina cultivation and Blakeslea trispora fermentation has reached over USD 320 million, according to industry filings [2]. These bio-production platforms provide improved isomer purity and match the market desire for recognized ingredients.


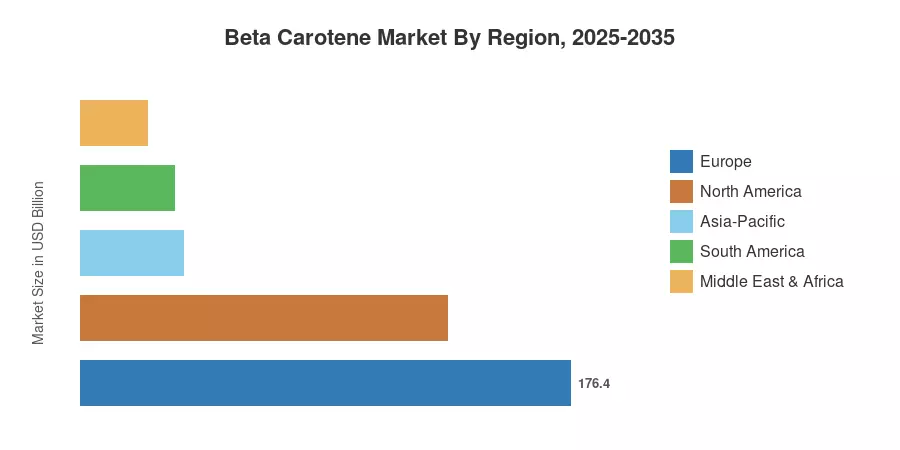
Stringent controls on colorants and a well-established dietary supplement channel have helped Europe achieve a 36% share of global beta carotene income. The fastest-growing region is Asia-Pacific, driven by increasing fortification mandates in India and Southeast Asia and a growing demand for poultry and aquaculture feed in China. North America accounts for roughly 27% of the market, supported by the U.S. supplement and functional food sectors. The tempo at which bio-sourced production ramps up vs cost-competitive synthetic supply will drive the beta carotene industry till 2035.


Key Report Takeaways

• By Nature

  • Natural beta-carotene holds approximately 58% of beta carotene market revenue, reflecting clean-label migration across food, beverage, and supplement categories.
  • Synthetic beta-carotene continues to grow at a CAGR of 4.8% as cost-sensitive animal feed and developing-market food applications sustain demand.

• By Application

  • Food & Beverage represents the dominant application in the beta carotene market, capturing roughly USD 186 million in 2026.
  • Dietary Supplements deliver the highest segment CAGR at 7.3%, driven by preventive-health consumer behavior and provitamin A positioning.

• By Geography

  • Europe leads the beta carotene market with a 36% revenue share, underpinned by EU regulatory frameworks favoring natural colorants.
  • Asia-Pacific is expanding at a CAGR of 7.6%, the fastest of any region, on the back of fortification policies and feed-industry growth.
  • North America accounts for approximately USD 132 million in 2026, with the U.S. representing the bulk of regional demand.


Beta Carotene Market Size and Forecast (2021–2035)

Market sizing includes bottom-up revenue modeling across application verticals and top-down cross-validation against import/export databases, business disclosures and regulatory filings. Historical figures (2021–2024) are based on audited trade data; the calibrated base year is 2025; and projections for 2026–2035 apply the 6.1% CAGR, adjusted for expected regulatory inflection points.
Beta Carotene Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Clean-label regulation and synthetic-dye restrictions +1.4% Europe, North America Short-term (≤2 yr)
Vitamin A fortification mandates in developing regions +1.1% Asia-Pacific, Africa Medium-term (2–4 yr)
Rising consumer demand for functional foods and supplements +0.9% Global Medium-term (2–4 yr)
Expansion of poultry and aquaculture feed programs +0.7% Asia-Pacific, South America Long-term (≥4 yr)
Advances in Dunaliella salina and fermentation-based production +0.6% Global Long-term (≥4 yr)
Growth in natural personal-care and cosmetics formulations +0.5% Europe, North America Medium-term (2–4 yr)
E-commerce supplement channel penetration +0.4% Global Short-term (≤2 yr)


Clean-Label Regulation and Synthetic-Dye Restrictions

The European Commission's ongoing review of Annex II to Regulation (EC) No 1333/2008 has already resulted in lower acceptable daily intakes for several azo dyes, pushing confectionery and beverage manufacturers toward beta-carotene as a replacement colorant. The UK Food Standards Agency reported a 14% increase in natural colorant usage declarations between 2022 and 2024 [5]. This regulatory momentum is the single largest near-term accelerator for the beta carotene market, directly expanding addressable volume for both liquid and powder formats.

Vitamin A Fortification Mandates

India's Food Safety and Standards Authority (FSSAI) mandated the fortification of edible oils with vitamin A (retinol or beta-carotene) under its 2023 revised standards, covering an oil market worth over USD 25 billion annually [6]. Similar programs in Bangladesh, the Philippines, and several East African nations have created a new institutional demand channel. These government-backed procurement cycles provide predictable volume floors for beta-carotene suppliers targeting the beta-carotene market in developing economies.

Functional Foods and Supplement Demand

Global consumer spending on dietary supplements surpassed USD 180 billion in 2024, with antioxidant and immunity-support categories growing at twice the overall supplement rate [7]. Beta-carotene's dual positioning as a provitamin A precursor and a lipid-soluble antioxidant makes it particularly attractive for multi-ingredient capsule and gummy formats. The beta-carotene market benefits directly from this wellness-spending wave, especially in the 25–45 age demographic across the U.S. and Western Europe.

Poultry and Aquaculture Feed Expansion

China's poultry sector consumed an estimated 1,800 metric tons of beta-carotene-based feed additives in 2024, a figure rising at approximately 8% annually as producers seek natural pigmentation agents for egg yolks and broiler skin [8]. Brazil's aquaculture feed segment is on a parallel trajectory. The feed vertical is price-sensitive, which sustains synthetic beta-carotene demand, but natural variants are gaining ground in premium and export-oriented supply chains within the beta carotene market.


Restraints Impact Analysis

Restraint impact percentages are directional estimates indicating how much each factor dampens potential growth. They do not subtract linearly from the CAGR.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Higher production cost of natural vs. synthetic beta-carotene –0.8% Global Long-term (≥4 yr)
Regulatory fragmentation across emerging markets –0.5% Asia-Pacific, MEA Medium-term (2–4 yr)
Stability and shelf-life limitations of natural formulations –0.4% Global Short-term (≤2 yr)
Competition from alternative natural colorants (annatto, paprika) –0.3% Europe, North America Medium-term (2–4 yr)
Supply-chain concentration in Dunaliella salina sourcing –0.3% Asia-Pacific, Oceania Long-term (≥4 yr)


Cost Premium of Natural Production

Natural beta-carotene extracted from Dunaliella salina or produced via Blakeslea trispora fermentation typically costs 3–5 times more per kilogram than petrochemically synthesized alternatives [11]. This gap constrains adoption in price-elastic segments such as animal feed and processed foods in lower-income markets. Until fermentation yields improve or algae-cultivation costs decline through automation, this pricing disparity will cap the natural segment's penetration rate in the beta carotene market.

Regulatory Fragmentation

While the EU and the U.S. have relatively harmonized frameworks for beta-carotene as a food additive (E160a) and GRAS ingredient, regulations across Southeast Asia, the Middle East, and parts of Africa remain inconsistent [12]. Divergent labeling requirements, import registration timelines, and permissible dosage limits create compliance overhead for multinational suppliers. For mid-sized producers targeting growth in the beta carotene market, this patchwork slows market entry by 12–18 months on average.

Competition from Alternative Natural Colorants

Annatto, paprika oleoresin, and turmeric-based colorants compete directly with beta-carotene in the orange-to-yellow color spectrum. Some food formulators prefer annatto for its cost advantage and heat stability in baked goods [14]. This competitive pressure is most visible in the beta-carotene market across European bakery and dairy applications, where annatto holds entrenched positions.


Beta Carotene Market Opportunities

Microencapsulation and Advanced Delivery Technologies

Microencapsulation techniques — including spray-drying, coacervation, and liposomal encapsulation — are resolving beta-carotene's historical limitations around oxidative degradation and poor water dispersibility. Companies investing in nano-emulsion platforms report up to 60% improvement in bioavailability compared to conventional oil suspensions [16]. This technology directly expands the beta carotene market's addressable formulation space into clear beverages, powdered drink mixes, and water-based personal-care products.

Fortification Programs in Sub-Saharan Africa and South Asia

The World Health Organization estimates that vitamin A deficiency affects approximately 250 million preschool children, with the heaviest burden in Sub-Saharan Africa and South Asia [1]. Government-led fortification programs for cooking oils, flour, and sugar represent a largely untapped institutional demand pipeline for the beta carotene market. Suppliers capable of offering cost-optimized, regulatory-compliant beta-carotene for these programs stand to capture multi-year procurement contracts.

Premiumization of Pet Nutrition

The global pet-food market exceeded USD 130 billion in 2024, and the premiumization trend is accelerating demand for natural colorants and functional ingredients in companion-animal diets [17]. Beta-carotene's recognized antioxidant properties and its role as a provitamin A source position it well for this adjacency, particularly in North American and European premium pet-food brands seeking clean-label claims.

Sustainability-Linked Sourcing and Carbon-Neutral Production

Algae-based beta-carotene production inherently captures CO₂ during cultivation, creating a compelling sustainability narrative for ESG-conscious food and cosmetics brands. Several Australian Dunaliella salina operations have achieved carbon-negative production certifications [18]. This sustainability positioning represents a differentiation lever within the beta carotene market, especially as Scope 3 reporting obligations tighten across European supply chains.

Digital Commerce and Direct-to-Consumer Supplement Brands

DTC supplement brands grew at roughly 18% annually between 2021 and 2024, far outpacing traditional retail channels. These digitally native brands favor branded, traceable, single-origin ingredients — a profile that natural beta-carotene suppliers can deliver with blockchain-enabled provenance tracking. The beta carotene market will increasingly flow through these e-commerce channels as younger consumers bypass pharmacy and mass-retail purchasing.


Beta Carotene Market Future Outlook

Precision Fermentation and Synthetic Biology Scale-Up

Advances in metabolic engineering are making microbial fermentation a cost-competitive route to high-purity beta-carotene. Engineered Yarrowia lipolytica and Saccharomyces cerevisiae strains have demonstrated yields exceeding 4 g/L in pilot-scale bioreactors, approaching price parity with petrochemical synthesis [20]. By 2030, fermentation-derived beta-carotene could capture 15–20% of global supply, reshaping the cost structure of the beta-carotene market and narrowing the natural-synthetic price gap.

Regulatory Convergence and Codex Harmonization

The Codex Alimentarius Commission's ongoing work on harmonized maximum levels for carotenoid food colorants is expected to reduce cross-border trade friction by the late 2020s [12]. A unified global standard would particularly benefit mid-sized beta-carotene producers that currently face duplicative registration costs across 30+ national jurisdictions. The beta-carotene market stands to gain approximately 80–120 basis points of additional growth from reduced regulatory compliance overhead once harmonization takes effect.

Sustainability Reporting and Scope 3 Supply-Chain Pressure

The EU Corporate Sustainability Reporting Directive (CSRD), effective from 2024 onward, requires food and ingredient companies to disclose Scope 3 emissions across their supply chains [18]. Algae-derived beta-carotene's favorable carbon profile positions it as a preferred sourcing option for multinational food brands under disclosure pressure. Producers with verified carbon-negative or carbon-neutral operations will command procurement preference and potential pricing premiums in the beta-carotene market through 2035.

Personalized Nutrition and Biomarker-Driven Supplementation

The rise of at-home nutrigenomics testing and blood-biomarker platforms is creating demand for personalized supplement regimens tailored to individual vitamin A status. Companies like InsideTracker and Viome have integrated carotenoid-level monitoring into their platforms, generating targeted beta-carotene supplementation recommendations [21]. This personalization trend could meaningfully expand the addressable consumer base of the beta-carotene market beyond traditional supplement buyers over the next decade.


Regional Market Share Analysis

Region Key Metric Primary Investment Themes
North America USD 132.0 M (2026) Supplement innovation, clean-label food reformulation
Europe 36% revenue share (2026) EU colorant regulations, natural cosmetics growth
Asia-Pacific 7.6% CAGR (2026–2035) Fortification mandates, feed-industry expansion
South America USD 33.8 M (2026) Poultry feed demand, edible-oil fortification
Middle East & Africa 4.9% CAGR (2026–2035) Vitamin A programs, halal-certified ingredients
Total USD 490.0 M (2026)

The beta carotene market displays a clear regional hierarchy, with Europe leading on regulatory-driven demand, Asia-Pacific delivering the strongest growth trajectory, and North America maintaining a robust supplement-oriented consumption base.


North America

Country Key Metric Key Driver
United States 78% of regional share Supplement and functional food demand
Canada USD 16.8 M (2026) Natural health product regulations
Mexico 5.4% CAGR Processed food and beverage sector growth


The U.S. drives the vast majority of North American beta carotene market activity, with dietary supplement and functional-food applications accounting for the largest demand pools. The FDA's continued GRAS affirmation for beta-carotene, combined with growing consumer distrust of synthetic additives, supports steady volume growth. Canada's Natural Health Products Regulations provide a distinct but complementary framework that favors standardized beta-carotene supplement formulations [19].

Europe

Country Key Metric Key Driver
Germany 22% of regional share Industrial food-ingredient manufacturing
United Kingdom USD 22.5 M (2026) Clean-label reformulation programs
France 5.8% CAGR Cosmetics and personal-care sector
Italy USD 14.2 M (2026) Dairy and confectionery colorant demand
Spain 4.7% CAGR Olive-oil fortification and export-oriented processing
Nordic Countries USD 11.3 M (2026) Supplement-forward consumer culture
Russia 4.2% CAGR Processed food modernization
Rest of Europe USD 18.9 M (2026) Diversified food-processing sectors


Europe's dominance in the beta carotene market stems from the EU's proactive regulatory stance on food colorants, where the European Food Safety Authority (EFSA) periodically re-evaluates synthetic additives and has tightened acceptable daily intakes for several azo dyes [5]. Germany functions as the region's manufacturing hub, hosting major ingredient producers with global distribution networks. The UK's post-Brexit regulatory independence has, if anything, accelerated clean-label adoption as British retailers differentiate on ingredient transparency.

Asia-Pacific

Country Key Metric Key Driver
China 34% of regional share Poultry feed and food-processing scale
India 8.4% CAGR Government fortification mandates
Japan USD 18.7 M (2026) Functional food culture and aging population
South Korea 6.9% CAGR K-beauty and nutraceutical demand
ASEAN USD 14.5 M (2026) Aquaculture feed and oil fortification
Rest of Asia-Pacific 5.8% CAGR Diversified food sectors


Asia-Pacific represents the fastest-growing region in the beta carotene market, driven by a convergence of government health policy and agricultural industrialization. China's feed-additive consumption alone accounts for a substantial share of regional volume, while India's FSSAI oil-fortification mandate is generating new institutional demand [6]. Japan's functional food regulatory framework (FOSHU and Foods with Function Claims) creates a premium-price channel that sustains higher per-unit margins for natural beta-carotene suppliers.

South America

Country Key Metric Key Driver
Brazil 62% of regional share Poultry-export industry and food processing
Argentina USD 5.9 M (2026) Edible-oil and dairy sectors
Rest of South America 5.1% CAGR Emerging food-fortification programs


Brazil dominates the South American beta carotene market, where the country's position as the world's largest poultry exporter creates consistent feed-additive demand. The Brazilian poultry sector produced over 14 million metric tons of chicken in 2024, and export-market quality requirements increasingly favor natural pigmentation agents over synthetic alternatives [8]. Argentina's dairy sector provides a secondary demand anchor.

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 28% of regional share Halal food-ingredient certification demand
UAE USD 3.8 M (2026) Premium food-service and cosmetics imports
South Africa 5.6% CAGR Food-processing modernization
Egypt USD 2.9 M (2026) Cooking-oil fortification programs
Rest of MEA 4.5% CAGR NGO-led vitamin A supplementation


The Middle East & Africa region is an emerging frontier for the beta carotene market, with growth split between premium halal-certified ingredient demand in the Gulf states and public-health-driven fortification in North and Sub-Saharan Africa. Saudi Arabia's food-safety modernization under Vision 2030 is expanding ingredient-specification requirements, while Egypt and Nigeria are piloting WHO-supported cooking-oil fortification with beta-carotene [1].


Beta Carotene Market By Region, 2025-2035

Beta Carotene Market Segmentation

By Nature

Segment Key Metric Primary Demand Driver
Natural 58% revenue share (2026) Clean-label consumer preference and regulatory tailwinds
Synthetic 4.8% CAGR (2026–2035) Cost-sensitive feed and developing-market food applications


Natural beta-carotene commands the majority of the beta-carotene market, sourced primarily from Dunaliella salina algae cultivation in Australia and Israel and from Blakeslea trispora fungal fermentation in China and Europe. The segment's premium pricing (typically 3–5× synthetic equivalents) is increasingly justified by consumer willingness to pay for recognizable, non-petrochemical ingredients. Growth is concentrated in dietary supplements, premium food and beverages, and personal-care applications where label claims carry measurable brand value.

Synthetic beta-carotene, produced predominantly through Wittig or Grignard chemical synthesis, retains a stronghold in animal feed and cost-driven food-processing segments. BASF and DSM (now dsm-firmenich) remain the dominant suppliers of synthetic variants. Despite slower growth, the synthetic segment delivers consistent volume to the beta carotene market and serves as the price benchmark against which natural alternatives are evaluated.

By Form

Segment Key Metric Primary Demand Driver
Powder USD 298 M (2026) Ease of handling, dosing precision, and shelf stability
Liquid 6.8% CAGR (2026–2035) Beverage and cosmetics formulation requirements


Powder-form beta-carotene dominates the beta-carotene market by value, favored for its stability during storage and transportation and its compatibility with tablet, capsule, and dry-mix food applications. Spray-dried and microencapsulated powder formats have improved dispersibility, addressing earlier formulation challenges in aqueous systems.

Liquid beta-carotene — typically delivered as oil suspensions or emulsions — is the faster-growing form, driven by beverage fortification, liquid supplement formats, and personal-care product development. The beta carotene market is seeing increasing adoption of nano-emulsion liquid formats that offer superior bioavailability and clear-solution aesthetics for transparent beverages.

By Application

Segment Key Metric Primary Demand Driver
Food & Beverage USD 186 M (2026) Natural colorant replacement and fortification
Dietary Supplement 7.3% CAGR (2026–2035) Preventive health and antioxidant positioning
Animal Feed 18% revenue share (2026) Egg-yolk pigmentation and livestock health
Personal Care & Cosmetics USD 38.2 M (2026) Anti-aging and natural formulation trends
Pharmaceuticals 5.2% CAGR (2026–2035) Vitamin A precursor in therapeutic products


Food & Beverage is the largest application segment in the beta carotene market, with demand anchored in dairy products, confectionery, bakery, and beverages where beta-carotene serves dual roles as a colorant and a nutrient. The EU's ongoing tightening of synthetic colorant regulations has been a primary catalyst for reformulation activity across this segment.

Dietary Supplements represent the fastest-growing application, with beta-carotene positioned as both a standalone antioxidant ingredient and a provitamin A source within multi-nutrient formulations. The segment's growth trajectory within the beta carotene market is reinforced by aging populations in developed markets, rising health literacy in emerging economies, and the proliferation of e-commerce supplement platforms.


Competitive Benchmarking

The beta carotene market is moderately concentrated, with the top five players anticipated to contribute 48-55% of the worldwide revenue. The competitive structure is separated into the natural-synthetic axis: some big chemical corporations dominate synthetic supply, while the natural segment is more fragmented with a number of specialty producers competing. The Herfindahl-Hirschman Index is between 900 and 1,200, indicating a highly competitive environment and significant chances for differentiation for niche firms.

Company Est. Revenue Share Range Key Offerings for Beta Carotene Market Strategic Positioning
dsm-firmenich ~12–16% Synthetic and natural beta-carotene; CaroCare® range Vertically integrated nutrition leader; dual natural-synthetic portfolio
BASF SE ~10–14% Synthetic beta-carotene; Lucantin® feed additives Chemical-synthesis scale; strong feed-sector presence
Allied Biotech Corporation ~6–9% Natural beta-carotene from Dunaliella salina Specialist algae-derived producer; Asia-Pacific distribution
Lycored ~5–8% Natural carotenoid blends; LycoRed® formulations Premium positioning in supplements and personal care
Kemin Industries ~4–7% Natural and nature-identical beta-carotene Feed and food applications; global technical-service network
DDW (Givaudan) ~3–6% Natural colorant solutions including beta-carotene Integrated into Givaudan's taste-and-wellbeing platform
Döhler Group ~3–5% Natural colors and beta-carotene extracts Clean-label food-ingredient solutions provider
Sensient Technologies ~3–5% Beta-carotene-based natural color systems Broad color portfolio; strong North American presence
ExcelVite Sdn Bhd ~2–4% Natural beta-carotene from palm oil; EVTene® Unique palm-derived sourcing; halal-certified
Cyanotech Corporation ~1–3% Natural beta-carotene from Dunaliella salina; BioAstin® brand Hawaiian algae cultivation; premium supplement brand


Recent News & Developments


  • BASF SE (November 2024): Launched a next-generation microencapsulated beta-carotene powder for clear-beverage applications, achieving water-dispersibility without emulsifiers, targeting European and North American beta-carotene market segments [16].
  • FSSAI (India) (August 2024): Issued revised enforcement guidelines for mandatory vitamin A fortification of edible oils, expanding coverage to mustard and coconut oil categories and broadening the addressable beta carotene market in the country [6].


Beta Carotene Market Report Scope

Parameter Detail
Market Scope Global beta carotene market across natural and synthetic sources, liquid and powder forms, five application verticals, and five geographic regions
Study Period 2021–2035
CAGR 6.1% (2026–2035)
Market Size (2025) USD 461.8 Million
Market Size (2035) USD 835.0 Million
Fastest Growing Segment Dietary Supplements (by application); Asia-Pacific (by region)
Companies Profiled 10 major players including DSM-Firmenich, BASF SE, Allied Biotech, Lycored, Kemin Industries, and others
Valuation Currency USD (constant 2025 dollars)

FAQs

How does microencapsulation technology affect beta-carotene pricing in food applications?
Microencapsulation adds roughly 15–20% to raw-material cost but extends shelf life by up to 40% and improves dispersibility. For food manufacturers, the net effect is lower total formulation cost per unit of active beta-carotene delivered [16].
What certification requirements should buyers verify when sourcing halal-grade beta-carotene?
Buyers should confirm third-party halal certification covering both the beta-carotene source organism and all processing aids. Gelatin-based encapsulation and ethanol extraction solvents are common disqualifiers that require substitution with plant-based alternatives [12].
How do all-trans and 9-cis isomer ratios differ between algae-derived and synthetic beta-carotene?
Algae-derived beta-carotene contains a natural mix of all-trans and 9-cis isomers (typically 50:50), while synthetic versions are nearly 100% all-trans. The 9-cis isomer is associated with enhanced antioxidant activity in clinical studies [11].
What minimum order volumes do contract manufacturers typically require for custom beta-carotene blends?
Most contract manufacturers set minimum orders between 500 kg and 2 metric tons for custom blends. Smaller volumes are available but carry 20–30% surcharges due to changeover and quality-testing overhead [15].
Which beta-carotene form performs best in high-temperature food processing above 180°C?
Microencapsulated powder formats with maltodextrin or modified-starch coatings retain 75–85% of beta-carotene content at 180°C for up to 30 minutes. Unprotected oil suspensions lose 40–50% under the same conditions [13].
How are Scope 3 emissions disclosures reshaping procurement criteria for beta-carotene ingredients?
European food brands subject to CSRD now require ingredient-level carbon-footprint data from suppliers. Algae-sourced beta-carotene producers with verified carbon-negative operations are gaining preferred-supplier status over synthetic alternatives [18].
What intellectual property considerations apply when developing novel fermentation-derived beta-carotene strains?
Engineered microbial strains for beta-carotene production are typically protected by utility patents covering specific genetic modifications. Licensees should conduct freedom-to-operate analyses, as overlapping patents from DSM, BASF, and academic institutions cover key metabolic pathways [20].    
Author
Author Author Profile Sakshi Gupta LinkedIn Team Lead - Research
Currently a Team Lead in consumer goods, FMCG, and F&B, she translates rigorous research into decisive strategy. She develops GTM roadmaps, pricing architectures, and competitive benchmarks for companies across Europe, the US, and APAC. She synthesize insights, align cross-functional teams, and drive execution from brief to measurable outcomes. She leads end-to-end engagements with crisp analysis, compelling storytelling, and a strong command of Power BI, Tableau, SQL, and advanced research platforms.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















