Backpack Market (2026 - 2035)

Backpack Market Size, Share, Industry Trend & Analysis Research Report Information By Product Type (Casual, Athletic), By Price Point (Economy, Mid-Range, Premium), By End-User (Adults, Children), By Distribution Channel (Offline Retail Stores, Online Retail Stores), By Geography (North America, Europe, Asia-Pacific, South America, Middle East and Africa) – Forecast Till 2035

Forecast Period
2026-2035
CAGR
7.16%
2025 Market Size
USD 23.26 Billion
2035 Market Size
USD 46.10 Billion
Consumer and Retail ● Updated August 26, 2026 Report ID: MRFR/CG/10512-HCR | Pages: 128 | Author: Pradeep Nandi

Backpack Market Summary

The Backpack Market closed 2025 at USD 23.26 Billion and opens the forecast window at USD 24.74 Billion in 2026, tracking toward USD 46.10 Billion by 2035 at a 7.16% CAGR. Two catalysts anchor that trajectory. India's Production Linked Incentive scheme for textiles and leather goods, worth roughly USD 1.4 billion in disbursable incentives, has pulled contract capacity into Tamil Nadu and Uttar Pradesh [7]. In parallel, the European Union's Ecodesign for Sustainable Products Regulation, in force since July 2024, now writes durability and recyclability thresholds directly into product law [4].

Carry design is being rebuilt from the inside out. Rigid single-compartment shells with sewn-in foam are giving way to modular sleeve systems, mono-material shells that survive mechanical recycling, and load-transfer harnesses validated against posture research. Fenix Outdoor, VF Corporation and Samsonite have collectively committed over USD 600 million to recycled-input sourcing and traceability infrastructure through 2028 [12][14][16]. Ergonomic strap design has moved from a premium differentiator to a school-channel procurement requirement across several jurisdictions.

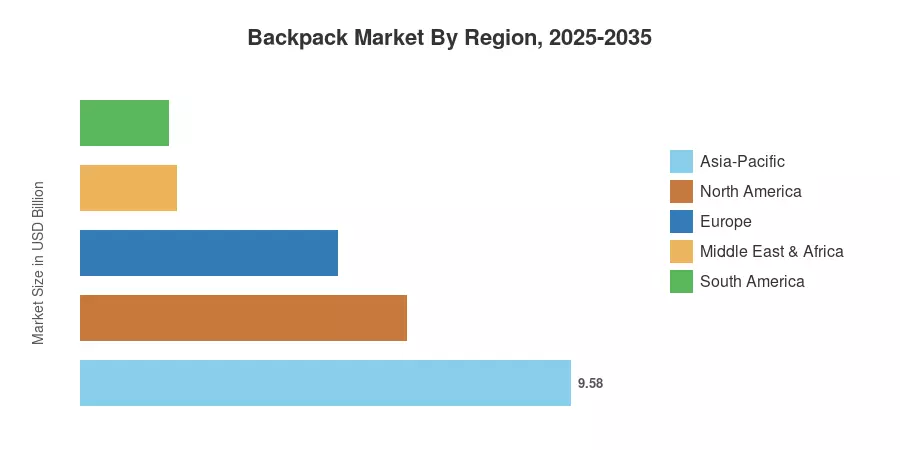
Regionally, Asia-Pacific holds 41.2% of 2025 value and remains the fastest-growing block at a 9.00% CAGR, powered by China's manufacturing base and India's expanding student cohort. North America follows at 27.4%, where premiumization offsets flat unit volumes. Europe contributes USD 5.02 Billion, with regulation rather than demographics setting the pace. Through 2035, the Backpack Market will reward brands that can prove material provenance as reliably as they market silhouette.


Key Report Takeaways

• By Product Type

  • Athletic packs commanded 55.7% of 2025 revenue, still the anchor category for the Backpack Market
  • Casual variants are forecast to compound at 9.59% through 2035 as hybrid work reshapes daily carry.

• By Price Point and End-User

  • Economy lines held 51.2% of 2025 value, sustained by school and institutional procurement.
  • Premium models above USD 150 are set to expand at 9.79% CAGR
  • Children's packs are projected to grow at 10.24% CAGR as load-limit standards tighten

• By Region

  • Asia-Pacific accounted for 41.2% of 2025 value across the Backpack Market


  • Middle East & Africa generated USD 1.02 Billion in 2025, with Gulf tourism the swing variable


Market Size and Forecast (2021–2035)

Figures blend customs-level trade data, brand-reported segment revenue, retail scanner panels across 34 countries, and primary interviews with 46 sourcing executives. Historical values are reconciled against company filings; forecast years apply a calibrated growth model weighted for channel mix and input-cost pass-through.
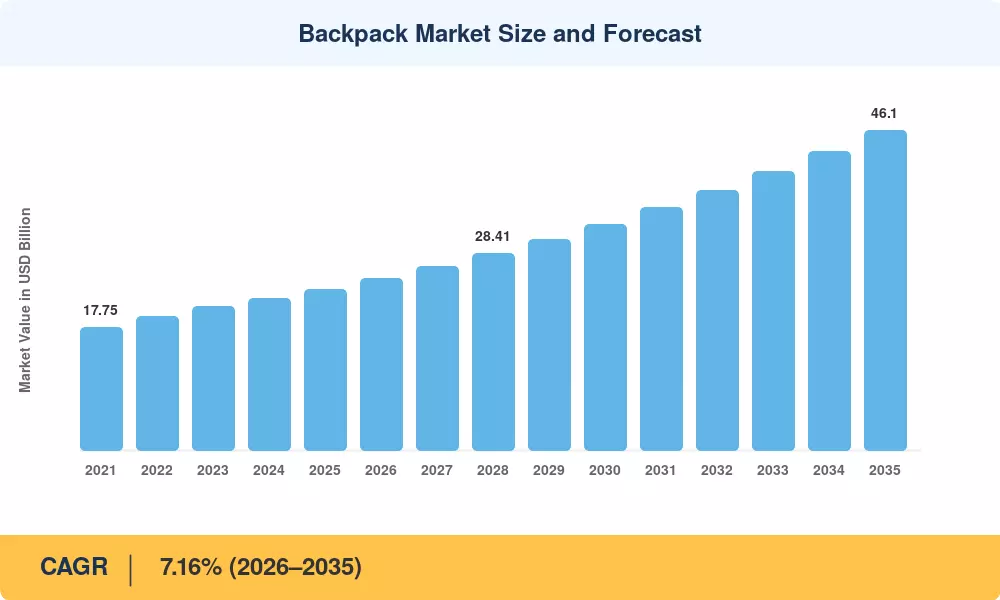
Backpack Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Outdoor recreation participation growth 1.6 North America, Europe Short-term (≤2 yr)
Direct-to-consumer e-commerce expansion 1.4 Global Short-term (≤2 yr)
Circular-economy and recycled-input policy 1.1 Europe, North America Medium-term (2–4 yr)
Rising student enrollment in emerging economies 1.0 Asia-Pacific, Africa Long-term (≥4 yr)
Premiumization and smart-feature integration 0.9 North America, Europe Medium-term (2–4 yr)
Manufacturing incentive schemes 0.7 Asia-Pacific Medium-term (2–4 yr)
Tourism and air-passenger recovery 0.6 Global Long-term (≥4 yr)


Outdoor Participation Is Rebuilding the Technical Tier

Roughly 179.6 million Americans took part in at least one outdoor activity in 2024, a participation rate near 58.3% of the population and the highest the Outdoor Industry Association has recorded [2]. Day-hiking grew fastest among 18-to-34-year-olds, a cohort that buys 25-to-40-litre technical packs rather than expedition volumes. That single shift lifted average selling prices across the Backpack Market without requiring unit growth, because a framed daypack carries roughly 2.3 times the retail value of an unstructured school pack.

E-Commerce Rewrites Distribution Economics

Global retail e-commerce crossed USD 6.3 trillion in 2024, with apparel and accessories among the top three penetrated categories [8]. Direct channels let niche brands skip wholesale margin stacks of 45–55%, which is why several sub-USD-50-million labels now ship to more than 60 countries. Returns remain the drag: apparel-accessory return rates of 18–22% erode the channel's gross-margin advantage unless fit and volume are communicated precisely at the product page.

Regulation Is Becoming a Product Specification

France's AGEC law extended producer responsibility to textiles and accessories, with eco-modulation fees that penalize non-recyclable constructions and reward durability certification [5]. The EU's Ecodesign framework goes further, setting the legal basis for digital product passports covering fibre composition and repairability by 2027 [4]. Compliance cost estimates run at 2–4% of landed cost for mid-tier brands, a burden that favors scaled manufacturers and accelerates consolidation among contract suppliers.


Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Counterfeit and grey-market penetration -1.2 North America, Europe Short-term (≤2 yr)
Petrochemical feedstock price volatility -0.9 Global Short-term (≤2 yr)
Tariff escalation on finished goods -0.8 North America Medium-term (2–4 yr)
Category cannibalization by rolling luggage -0.5 Europe, North America Long-term (≥4 yr)
Recycled-material supply constraints -0.4 Global Medium-term (2–4 yr)


Counterfeits Erode Premium Pricing Power

In fiscal year 2024, US Customs and Border Protection seized counterfeit items with an estimated MSRP of more than USD 2.9 billion, with handbags, wallets and carry accessories being one of the highest categories by line count [10]. A credible copy at USD 45 does more than divert a sale for a premium pack selling at USD 220 – it resets consumer reference pricing. Brands have responded with NFC authentication chips and serialized warranty registration, adding an estimated USD 1.10–1.80 per unit in cost.


Input Costs Refuse to Settle

Between January 2023 and December 2025, polyamide and polyester filament prices fluctuated within a 27% range, reflecting the volatility of naphtha and crude [9]. Packs have a design lead time of 8–14 months, so brands cannot reprice mid-season without breaking retailer margin agreements. The practical outcome is spec downgrades: 630D textiles instead of 900D, or coated instead of laminated finishes, discreetly cutting product life and running counter to the durability criteria now inscribed into European law [4].


Backpack Market Opportunities

Repair and Resale as a Revenue Line

Repair programs that sit next to warranties are turning cost centers into margin. Patagonia's Reno, Nevada operation handles more than 100,000 repairs annually, and certified-refurbished carry gear often resells for 45–60% of original price, with revenue margins exceeding those of new goods [5]. Brands that instrument maintenance data also get failure-mode insight that flows directly into next season specification.


Africa's Student Demographic Gap

Sub-Saharan Africa is expected to increase the number of secondary school students by 38 million between 2025 and 2035 [6]. Distribution, not demand, is the limiting restriction. Organized retail penetration is less than 12% across most of the region. Brands that partner with informal networks that can do mobile money can reach families that formal channels will not profitably serve for another decade.


Smart Carry and Data Monetization

Integrated tracking, solar charging panels and biometric locks are moving from novelty into the USD 150-plus tier, where attachment-rate data becomes a monetizable asset. A brand knowing which compartments a customer actually uses can price accessories, sell modular inserts on subscription, and cut SKU proliferation — a business model shift that reframes the Backpack Market from a one-time durable sale into a recurring relationship.

Nearshoring to Latin America

Brazilian and Mexican contract manufacturers are winning volume as North American brands hedge Asian tariff exposure [10]. Mexico's proximity permits 14-day replenishment against 45-day ocean transit, which matters enormously for back-to-school windows where a one-week stockout costs a full season.

Institutional Ergonomic Procurement

Pediatric guidance recommending loaded packs stay under 10–15% of body weight is being written into school district purchasing specifications across the US, Japan and South Korea [15]. Vendors with published biomechanical validation data win these tenders outright; those without are excluded at the RFP stage regardless of price.


Backpack Market Future Outlook

Material Science Sets the Ceiling

Mono-material construction is the decade's defining engineering problem for the Backpack Market. Recycled polyester supply reached roughly 8.9 million tonnes globally in 2024, yet fibre-to-fibre recycled content remains under 1% of total polyester output [13]. Until chemical recycling capacity scales, brands claiming circularity are largely working with bottle-derived feedstock — a bridge, not a destination, and one regulators have started to scrutinize.

Channel Convergence Replaces Channel Choice

Pure-play direct-to-consumer economics have deteriorated as customer acquisition costs climbed 60% between 2021 and 2025 across consumer categories [8]. The winning configuration through 2035 blends owned digital, marketplace presence, and a curated wholesale footprint that functions as physical marketing. Brands that abandoned wholesale entirely are quietly rebuilding it.

Transparency Becomes Infrastructure

Digital product passports under the EU framework will require item-level data on composition, origin and repair history by 2027 [4]. That obligation demands ERP and PLM investment far beyond what most mid-tier carry brands currently run. Expect a wave of platform consolidation as compliance software becomes a purchase decision rather than an IT preference.

Service Revenue Enters the P&L

Repair, resale and rental will move from marketing initiative to reported segment. Several European brands already generate 3–5% of revenue from certified pre-owned channels, and the OECD projects circular business models expanding materially across durable consumer goods through the next decade [18]. Margin structure differs enough that finance teams will need separate unit economics.


Backpack Market Segmentation

By Product Type

Product architecture defines everything downstream in the Backpack Market — pricing, channel, and repairability all follow from it.

Segment Metric (2025) Primary Demand Driver
Athletic 55.7% share Outdoor participation and technical performance
Casual 9.59% CAGR Hybrid work and urban mobility patterns


Athletic packs retain leadership because performance features justify price. Framed suspensions, hydration compatibility and weather-sealed zippers are difficult to counterfeit convincingly, which protects margin. Casual packs grow faster for the opposite reason: hybrid work replaced the gym-to-office commute with shorter, lighter city trips, and consumers replace fashion-forward casual carry roughly every 22 months against 41 months for technical packs.

By Price Point

Price stratification within the Backpack Market has widened, hollowing out the middle.

Segment Metric (2025) Primary Demand Driver
Economy 51.2% share School and institutional bulk procurement
Mid-Range USD 7.79 Billion Commuter and general-purpose replacement
Premium 9.79% CAGR Smart features and material credentials


Premium above USD 150 is the profit pool. Solar panels, biometric locks and modular insert systems let brands hold price through input-cost swings that would otherwise force spec downgrades. Economy volume persists because school procurement is budget-bound, but eco-modulation fees are beginning to raise the floor price of the cheapest constructions in Europe [5].

By End-User

Demographic segmentation in the Backpack Market is shifting toward the smaller cohort.

Segment Metric (2025) Primary Demand Driver
Adults 63.8% share Commuting, travel and outdoor recreation
Children 10.24% CAGR Enrollment growth and ergonomic standards


Children's packs grow fastest because two forces stack: enrollment expansion in Asia and Africa, plus tightening load-safety guidance in developed markets that obsoletes existing inventory [15]. Adult demand stays larger but replacement-cycle bound, growing through price rather than units in mature economies.

By Distribution Channel

Channel economics are the most volatile variable in the Backpack Market today.

Segment Metric (2025) Primary Demand Driver
Offline Retail Stores 60.4% share Fit assessment and immediate availability
Online Retail Stores 10.13% CAGR Assortment breadth and direct brand access


Physical retail still dominates because packs need trying on — a 40-litre pack fits a 168 cm torso very differently from a 190 cm one. Online wins on breadth and grows faster, but return rates near 20% mean the channel's true profitability depends on fit-prediction tooling more than on traffic.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
Asia-Pacific 41.2% share Manufacturing incentives, student demographics, ASEAN retail
North America USD 6.37 Billion Premiumization, anti-counterfeit tech, outdoor participation
Europe 21.6% share Ecodesign compliance, circularity, repair infrastructure
South America 7.4% CAGR Nearshoring capacity, formal retail expansion
Middle East & Africa 8.1% CAGR Tourism corridors, school enrollment growth
Total USD 23.26 Billion

Geographic performance across the Backpack Market splits along a clear line: Asia-Pacific supplies and increasingly consumes, Western markets set the regulatory and premiumization agenda, and the remaining regions grow off small bases with high volatility.


North America

Country Share of Region Key Driver
US 71.8% Outdoor participation and premium technical demand
Canada 12.4% Winter-sport and commuter carry
Mexico 15.8% Nearshore manufacturing plus domestic retail growth


Tariff policy dominates boardroom conversation here. Section 301 duties and subsequent adjustments pushed landed costs on China-sourced finished goods up by double digits, prompting a supplier reshuffle toward Vietnam, Cambodia and Mexico [10]. American consumers absorbed part of that through higher price points. Still, the durable effect is assortment narrowing — retailers now carry fewer SKUs at higher average prices, which advantages brands with clear identity over commodity fillers.

Europe

Country Market Value (USD B) Key Driver
Germany 1.06 Hiking culture and technical pack demand
UK 0.88 Commuter and student carry
France 0.72 AGEC eco-modulation reshaping specification
Italy 0.58 Design-led premium positioning
Spain 0.45 Tourism-driven travel carry
Nordic Countries 0.37 Outdoor and hiking gear participation
Russia 0.34 Domestic brand substitution
Rest of Europe 0.62 Cross-border e-commerce


Compliance is Europe's growth engine and its cost. Extended producer responsibility fees under France's AGEC framework now vary by a factor of three depending on recyclability and repairability scoring, creating a measurable price advantage for well-designed goods [5]. German and Nordic buyers, already conditioned to pay for longevity, absorb the differential; Southern European price-sensitive channels do not, which is widening the intra-regional performance gap.

Asia-Pacific

Country Share of Region Key Driver
China 38.6% Manufacturing scale and domestic premium shift
India 16.4% Student cohort and PLI-backed capacity
Japan 13.1% Commuter density and ergonomic standards
South Korea 8.2% Fashion-led casual carry
ASEAN 14.7% Export assembly plus rising middle class
Rest of Asia-Pacific 9.0% Tourism and organized retail entry


Asia-Pacific is where the Backpack Market's cost structure is decided. China still assembles the majority of global volume, but Vietnam's share of US carry-goods imports has climbed steadily as brands diversify [10]. India's parallel play is domestic: PLI disbursements plus a school-age population above 260 million make it the only market that can absorb enormous economy volume while simultaneously building a credible premium tier [6][7].

South America

Country CAGR (2026–2035) Key Driver
Brazil 7.9% Formal retail expansion and nearshore assembly
Argentina 6.8% Import liberalization improving brand access
Rest of South America 6.1% Andean tourism and student demand


Brazil's advantage is industrial rather than demographic. Established leather and synthetics clusters in Rio Grande do Sul already serve footwear, and the tooling overlap with carry goods is substantial. Currency volatility remains the principal risk — a 15% real depreciation can wipe out an entire season's imported-brand margin, which is precisely why local assembly partnerships are accelerating [17].

Middle East & Africa

Country Market Value (USD B) Key Driver
Saudi Arabia 0.28 Vision 2030 tourism and retail investment
UAE 0.22 Transit hub retail and expatriate demand
South Africa 0.20 Organized retail and school procurement
Egypt 0.14 Population growth and local manufacturing
Rest of MEA 0.18 Informal channel distribution


Gulf demand runs on travel. Saudi Arabia's tourism programs target 150 million annual visits by 2030, and airport retail concessions have become a primary discovery channel for premium carry brands [11]. Africa's story is entirely different — volume-led, price-anchored, and dependent on distribution ingenuity rather than marketing spend. The two dynamics share a region label and almost nothing else.


Backpack Market By Region, 2025-2035

Competitive Benchmarking

The Backpack Market is moderately fragmented. Estimated HHI sits in the 450–600 band, with the top five players holding roughly 30–35% of global value. Below that tier, several hundred regional and specialist brands compete on niche credibility, and barriers to entry remain low for casual products while genuinely high for technical suspension systems.

Company Est. Revenue Share Range Key Offerings for Backpack Market Strategic Positioning
VF Corporation ~9–12% JanSport, Eastpak, The North Face packs Multi-brand portfolio spanning economy to technical
Samsonite International ~6–8% Samsonite, American Tourister, Tumi carry Travel-anchored with strong premium tier
Nike Inc. ~5–7% Brasilia, Elemental, Utility series Athletic-lifestyle crossover and channel scale
adidas AG ~4–6% Power, Linear, Terrex packs Sport-performance halo with global distribution
Decathlon ~3–5% Quechua, Forclaz, Kipsta ranges Vertical integration and aggressive value pricing
Thule Group ~2–4% Thule and Case Logic packs Engineering-led, protection and mobility focus
Amer Sports ~2–3% Arc'teryx, Salomon technical packs Alpine authenticity at premium price points
Fenix Outdoor ~1.5–2.5% Fjällräven Kånken and trekking packs Heritage design plus sustainability leadership
Helen of Troy (Osprey) ~1.5–2.5% Osprey trekking and travel packs Lifetime-warranty and repair-led loyalty
Deuter (Schwan-Stabilo) ~1–2% Aircontact, Futura series Suspension-system specialization
Herschel Supply Co. ~1–2% Little America, Classic ranges Design-forward casual positioning
Wildcraft India ~1–2% Trekking and student packs Dominant domestic scale in India


Recent News & Developments

  • European Commission (July 2024): Ecodesign for Sustainable Products Regulation entered into force, establishing the legal basis for durability, repairability and digital product passport rules covering carry goods [4].
  • Samsonite International (March 2024): Announced expanded recycled-content targets across its accessories portfolio, committing to recycled materials in a majority of new introductions by 2027 [14].
  • VF Corporation (September 2024): Completed a portfolio review that prioritized The North Face and JanSport investment while divesting non-core assets, sharpening capital allocation toward carry and outdoor [12].
  • Helen of Troy (May 2024): Reported Osprey integration synergies and expanded the brand's All Mighty Guarantee repair network across European service centers [5].
  • Government of India (June 2023): Extended Production Linked Incentive disbursements to additional textile and accessory manufacturers, adding contract capacity relevant to export pack assembly [7].
  • Amer Sports (February 2024): Completed its New York Stock Exchange listing, raising roughly USD 1.3 billion and earmarking proceeds partly toward Arc'teryx retail and product expansion [16].
  • US Customs and Border Protection (October 2024): Published fiscal-year seizure data showing continued high counterfeit volumes in handbags and carry accessories, reinforcing brand authentication investment [10].
  • Thule Group (November 2025): Launched an expanded commuter and protective pack range with modular device sleeves, targeting hybrid-work carry patterns [19].


Backpack Market Report Scope

Parameter Detail
Market Scope Global Backpack Market by product type, price point, end-user, distribution channel and geography
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 7.16% (2026–2035)
Market Size Checkpoints USD 23.26 Billion (2025); USD 24.74 Billion (2026); USD 46.10 Billion (2035)
Fastest Growing Segments Children's packs; Premium price tier; Online retail stores; Asia-Pacific
Companies Profiled 12 profiled players including VF Corporation, Samsonite, Nike, adidas, Decathlon, Thule, Amer Sports, Fenix Outdoor, Osprey, Deuter, Herschel, Wildcraft
Valuation Currency USD Billion, constant 2025 exchange rates

FAQs

What due-diligence red flags should investors check before acquiring a brand in the Backpack Market?
Verify whether recycled-content claims are third-party certified or supplier-attested only. Unverified claims create retroactive liability under EU substantiation rules and can void retailer listings [4].
How should procurement teams evaluate warranty terms across suppliers?
Ask for actual claim-rate data, not warranty language. A lifetime guarantee with a 0.4% claim rate signals durable construction; one above 3% signals a marketing promise the product cannot support [21].
Is contract manufacturing or owned production better for a mid-size brand in the Backpack Market?
Contract manufacturing suits brands below roughly USD 80 million in revenue, preserving capital flexibility. Owned capacity only pays back above that threshold, and mainly where proprietary suspension technology needs protecting [7].
What integration challenges arise when adding electronics to carry products?
Battery-containing packs trigger air-freight restrictions, separate customs classifications, and electrical safety certification in most jurisdictions. Budget 9–14 months of additional lead time for first compliant shipment [22].
Which certifications carry real commercial weight in the Backpack Market?
bluesign and OEKO-TEX open European wholesale doors; GRS certification is increasingly a hard requirement for recycled-content claims. Fair-labor audits matter most for institutional and school tenders [13].
How do tariff classifications differ between school packs and technical packs?
Classification depends on outer-surface material rather than intended use, so a coated-textile school pack and a technical pack can face different duty rates. Misclassification penalties frequently exceed the duty saved [10].
What does a realistic resale program require operationally?
Reverse logistics, cleaning and grading capacity, plus an authentication step. Most brands underestimate grading labor, which typically runs 18–25 minutes per unit before an item is listable [18].      
Author
Author
Author Profile
Pradeep Nandi LinkedIn Senior Research Analyst
I have a bachelor's degree in mechanical engineering and an MBA. I have more than two years of expertise in the retail, food, and beverage, chemical, and material industries, and hence have developed a sound cross-domain expertise. A firm believer in lifelong learning and sharing of knowledge. Having a proclivity for hatching ideas and trying to absorb as much information as possible in a short amount of time. Introducing corporates to the data and insight, which enables them to move from probability to possibility, has been my key areas of interest. 

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of trade databases, industry publications, textile research journals, consumer retail reports, and authoritative economic organizations. Key sources included the US Bureau of Economic Analysis (BEA), US International Trade Commission (USITC), US Consumer Product Safety Commission (CPSC), European Commission (EC) Enterprise and Industry Database, Eurostat Consumer Goods Statistics, International Trade Centre (ITC) Trade Map, World Trade Organization (WTO) Trade Statistics, World Customs Organization (WCO), Organisation for Economic Co-operation and Development (OECD) Consumer Policy Statistics, International Labour Organization (ILO) Textile and Leather Statistics, National Retail Federation (NRF) Economic Data, Outdoor Industry Association (OIA) Participation Report, Sport and Fitness Industry Association (SFIA), World Travel & Tourism Council (WTTC), UN Comtrade Database, International Monetary Fund (IMF) World Economic Outlook, and national statistics offices from key manufacturing hubs including China National Bureau of Statistics, India Ministry of Textiles, and Vietnam General Statistics Office.

For travel backpacks, hiking/camping backpacks, nylon materials, polyester materials, and distribution channel dynamics, these sources were used to gather production statistics, import/export trade flows, material innovation data, consumer spending patterns, and competitive landscape analysis.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, VPs of Product Development, supply chain directors, and heads of sustainability from backpack manufacturers, outdoor gear companies, and textile suppliers were examples of supply-side sources. Retail buyers, category managers, e-commerce directors, outdoor recreation experts, and procurement leaders from department stores, sports goods shops, specialty outdoor stores, and online marketplaces were examples of demand-side sources. Primary research obtained information on consumer buying habits, pricing tactics, and omnichannel distribution dynamics in addition to validating market segmentation and confirming timescales for the adoption of sustainable materials.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (31%), Others (37%)

By Region: North America (38%), Europe (29%), Asia-Pacific (25%), Rest of World (8%)


Market Size Estimation

Production volume analysis and revenue mapping were used to get the global market valuation. The methodology comprised:

Finding more than fifty important manufacturers in North America, Europe, Asia-Pacific, and Latin America

Product mapping for hiking/camping backpacks, travel backpacks, and other niche areas

Material examination of leather, canvas, nylon, polyester, and sustainable/recycled substitutes

Channel mapping between offline brick-and-mortar stores and online e-commerce platforms

Analysis of annual revenues for backpack product portfolios, both reported and modeled

coverage of producers accounting for 70–75% of the world market in 2024

Extrapolation of segment-specific valuations across product type, material composition, and distribution channel utilizing top-down (manufacturer revenue validation) and bottom-up (production volume × ASP by country/region) methods

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















