Backpack Market (2026 - 2035)

ID: MRFR/CG/10512-HCR 128 Pages Pradeep Nandi Last Updated: September 15, 2026
Backpack Market Size, Share, Industry Trend & Analysis Research Report Information By Product Type (Casual, Athletic), By Price Point (Economy, Mid-Range, Premium), By End-User (Adults, Children), By Distribution Channel (Offline Retail Stores, Online Retail Stores), By Geography (North America, Europe, Asia-Pacific, South America, Middle East and Africa) – Forecast Till 2035
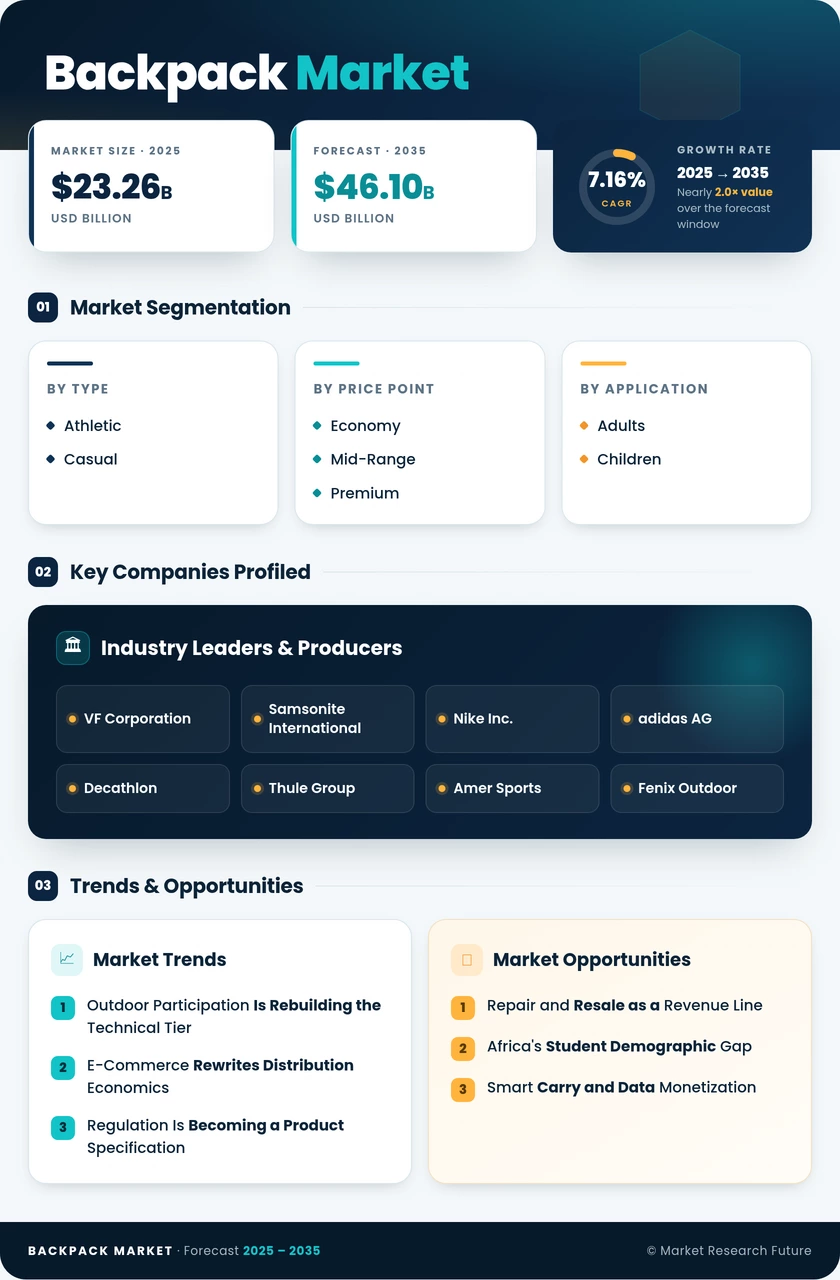
Backpack Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)7.16%
2025 Market SizeUSD 23.26 Billion
2035 Market SizeUSD 46.10 Billion
Key Players
VF Corporation
Samsonite International
Nike Inc.
adidas AG
Decathlon
Thule Group
Opportunities
  • Repair and Resale as a Revenue Line
  • Africa's Student Demographic Gap
  • Smart Carry and Data Monetization
  1. 1 Market Overview |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Market Summary & Key Takeaways |
    1. 2.1 Key Findings by Product Type |
    2. 2.2 Key Findings by Price Point and End-User |
    3. 2.3 Key Findings by Geography
  3. 3 Market Size & Forecast (2021–2035) |
    1. 3.1 Historical Market Size (2021–2024) |
    2. 3.2 Base Year Assessment (2025) |
    3. 3.3 Forecast Market Size (2026–2035) |
    4. 3.4 Year-over-Year Growth Analysis
  4. 4 Market Drivers Analysis |
    1. 4.1 Outdoor Recreation Participation Growth |
    2. 4.2 Direct-to-Consumer E-Commerce Expansion |
    3. 4.3 Circular-Economy and Recycled-Input Policy |
    4. 4.4 Rising Student Enrollment in Emerging Economies |
    5. 4.5 Premiumization and Smart-Feature Integration |
    6. 4.6 Manufacturing Incentive Schemes |
    7. 4.7 Tourism and Air-Passenger Recovery
  5. 5 Market Restraints Analysis |
    1. 5.1 Counterfeit and Grey-Market Penetration |
    2. 5.2 Petrochemical Feedstock Price Volatility |
    3. 5.3 Tariff Escalation on Finished Goods |
    4. 5.4 Category Cannibalization by Rolling Luggage |
    5. 5.5 Recycled-Material Supply Constraints
  6. 6 Market Opportunity Analysis |
    1. 6.1 Repair and Resale as a Revenue Line |
    2. 6.2 Africa's Student Demographic Gap |
    3. 6.3 Smart Carry and Data Monetization |
    4. 6.4 Nearshoring to Latin America |
    5. 6.5 Institutional Ergonomic Procurement |
    6. 6.6 Industry Value Chain Analysis |
    7. 6.7 Porter's Five Forces Analysis
  7. 7 Regional Analysis |
    1. 7.1 North America | |
      1. 7.1.1 US | |
      2. 7.1.2 Canada | |
      3. 7.1.3 Mexico |
    2. 7.2 Europe | |
      1. 7.2.1 Germany | |
      2. 7.2.2 UK | |
      3. 7.2.3 France | |
      4. 7.2.4 Italy | |
      5. 7.2.5 Spain | |
      6. 7.2.6 Nordic Countries | |
      7. 7.2.7 Russia | |
      8. 7.2.8 Rest of Europe |
    3. 7.3 Asia-Pacific | |
      1. 7.3.1 China | |
      2. 7.3.2 India | |
      3. 7.3.3 Japan | |
      4. 7.3.4 South Korea | |
      5. 7.3.5 ASEAN | |
      6. 7.3.6 Rest of Asia-Pacific |
    4. 7.4 South America | |
      1. 7.4.1 Brazil | |
      2. 7.4.2 Argentina | |
      3. 7.4.3 Rest of South America |
    5. 7.5 Middle East & Africa | |
      1. 7.5.1 Saudi Arabia | |
      2. 7.5.2 UAE | |
      3. 7.5.3 South Africa | |
      4. 7.5.4 Egypt | |
      5. 7.5.5 Rest of Middle East & Africa
  8. 8 Future Outlook (2026–2035) |
    1. 8.1 Material Science and Mono-Material Construction |
    2. 8.2 Channel Convergence |
    3. 8.3 Transparency and Digital Product Passports |
    4. 8.4 Service Revenue and Circular Models
  9. 9 Market Segmentation Analysis |
    1. 9.1 By Product Type | |
      1. 9.1.1 Casual | |
      2. 9.1.2 Athletic |
    2. 9.2 By Price Point | |
      1. 9.2.1 Economy | |
      2. 9.2.2 Mid-Range | |
      3. 9.2.3 Premium |
    3. 9.3 By End-User | |
      1. 9.3.1 Adults | |
      2. 9.3.2 Children |
    4. 9.4 By Distribution Channel | |
      1. 9.4.1 Offline Retail Stores | |
      2. 9.4.2 Online Retail Stores |
    5. 9.5 By Geography
  10. 10 Competitive Landscape |
    1. 10.1 Market Concentration Analysis (2026) |
    2. 10.2 Competitive Benchmarking Matrix |
    3. 10.3 Company Profiles | |
      1. 10.3.1 VF Corporation | |
      2. 10.3.2 Samsonite International | |
      3. 10.3.3 Nike Inc. | |
      4. 10.3.4 adidas AG | |
      5. 10.3.5 Decathlon | |
      6. 10.3.6 Thule Group | |
      7. 10.3.7 Amer Sports | |
      8. 10.3.8 Fenix Outdoor | |
      9. 10.3.9 Helen of Troy (Osprey) | |
      10. 10.3.10 Deuter (Schwan-Stabilo) | |
      11. 10.3.11 Herschel Supply Co. | |
      12. 10.3.12 Wildcraft India
  11. 11 Recent News & Developments
  12. 12 Report Scope & Methodology |
    1. 12.1 Study Period & Base Year |
    2. 12.2 Valuation Currency & Assumptions
  13. 13 Detailed Sources & Citations
  14. 14 Frequently Asked Questions
  15. 15 LIST OF TABLES
  16. 16 LIST OF FIGURES

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Product TypeCasual, AthleticAthleticCasual
By Price PointEconomy, Mid-Range, PremiumEconomyPremium
By End-UserAdults, ChildrenAdultsChildren
By Distribution ChannelOffline Retail Stores, Online Retail StoresOffline Retail StoresOnline Retail Stores
By GeographyNorth America, Europe, Asia-Pacific, South America, Middle East and AfricaAsia-PacificAsia-Pacific


Market Segmentation Overview

By Product Type

Sub-SegmentKey Trend
CasualHybrid work shortens commutes, favoring lighter unstructured silhouettes with faster replacement cycles
AthleticTechnical suspensions, hydration compatibility and weather sealing sustain price integrity


Product architecture is the clearest predictor of margin. Athletic construction resists commoditization because suspension engineering is hard to copy convincingly, while casual demand turns on design refresh velocity rather than performance claims.

By Price Point

Sub-SegmentKey Trend
EconomyInstitutional and school procurement anchors volume; eco-modulation fees raising the effective price floor
Mid-RangeSqueezed from both directions as buyers trade up for features or down for value
PremiumSolar charging, biometric locks and modular inserts justify pricing above USD 150


Stratification is widening. Brands positioned squarely in the middle face the hardest strategic choice this decade — invest in genuine differentiation or accept structural margin compression.

By End-User

Sub-SegmentKey Trend
AdultsGrowth driven by price and premiumization rather than unit expansion in mature economies
ChildrenEnrollment growth in Asia and Africa plus tightening load-safety guidance in developed markets


The smaller cohort grows faster. Pediatric load-limit guidance is entering formal school procurement specifications, which effectively obsoletes non-validated inventory and rewards vendors with published biomechanical testing.

By Distribution Channel

Sub-SegmentKey Trend
Offline Retail StoresFit assessment and immediate availability sustain majority share
Online Retail StoresAssortment breadth and direct brand access drive fastest channel growth, constrained by return rates


Channel strategy has converged rather than bifurcated. The brands performing best run owned digital, selective marketplace presence and a curated wholesale footprint that doubles as physical marketing.

By Geography

Sub-SegmentKey Trend
North AmericaTariff-driven sourcing diversification and heavy anti-counterfeit investment
EuropeEcodesign and extended producer responsibility reshaping product specification
Asia-PacificManufacturing scale plus the largest student demographic base globally
South AmericaNearshore assembly capacity and expanding formal retail
Middle East and AfricaGulf tourism corridors alongside volume-led African school demand


Geography now determines not just where products sell but how they must be designed. European regulation, North American tariff policy and Asian manufacturing incentives each pull specification in different directions, and global brands increasingly maintain regionally distinct product architectures rather than one worldwide range.


 

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.