Automotive Parts Magnesium Die Casting Market Summary
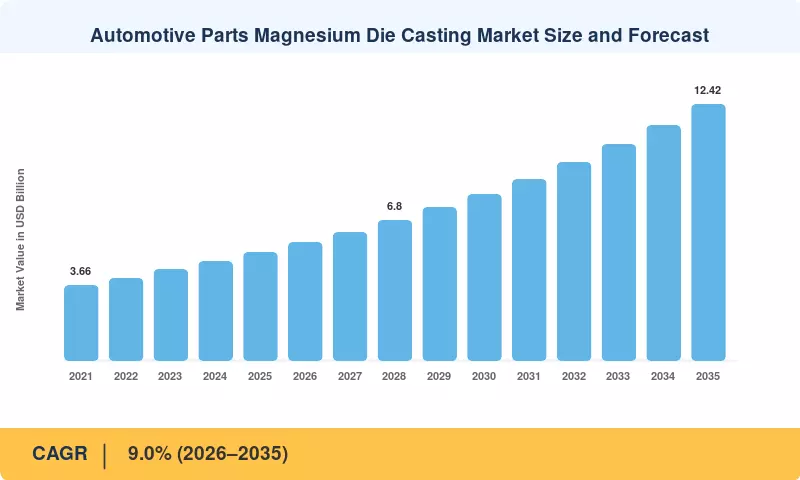
The Automotive Parts Magnesium Die Casting Market was valued at USD 5.25 Billion in 2025 and is projected to reach USD 5.72 Billion in 2026, rising to USD 12.42 Billion by 2035 at a CAGR of 9.0% over 2026–2035. Two regulatory catalysts anchor that trajectory. The U.S. EPA's multi-pollutant rule for model years 2027–2032 targets a roughly 50% cut in light-duty fleet greenhouse gas emissions from 2026 levels [2], and EU Regulation 2023/851 mandates a 55% reduction in new-car CO2 by 2030 and 100% by 2035 [4]. Every kilogram removed from a vehicle now carries compliance value, and magnesium, at about 1.74 g/cm³, is the lightest structural metal that can be die-cast at automotive volumes.
Stamped steel assemblies and multi-piece aluminum brackets are giving way to single-shot magnesium castings. Instrument panel cross-car beams, seat frames, steering wheel armatures, and liftgate inner panels that once required 10 to 20 welded steel pieces are now produced as one thin-wall casting, with magnesium roughly one-third lighter than aluminum and about three-quarters lighter than steel [5][6]. The U.S. Department of Energy estimates that a 10% cut in vehicle mass improves fuel economy by 6–8% [5], and the same physics extends battery electric range. On the shop floor, casting cells are shifting from manually tended cold-chamber machines toward vacuum-assisted, robot-served lines that produce lightweight metal components with inline X-ray inspection.
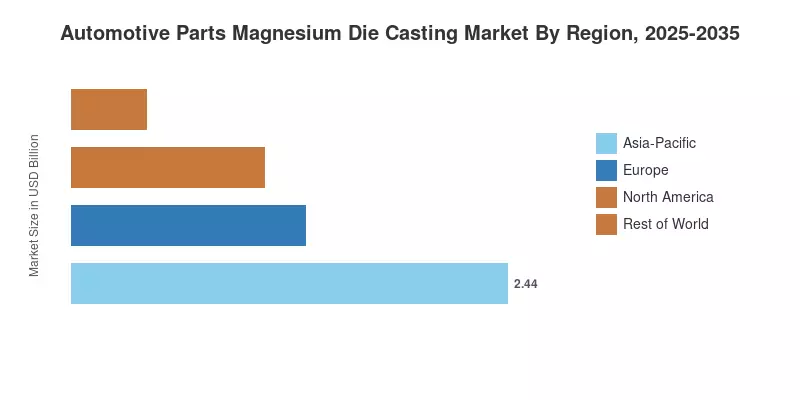
Asia-Pacific leads with a 46.5% share in 2025 and is also the fastest-growing region, expanding at a CAGR of 10.2% through 2035 on the strength of China's vehicle output and India's component localization push. Europe ranks second with a 25.0% share, driven by German premium OEMs and strict fleet CO2 targets. Over the next decade, competitive position in the Automotive Parts Magnesium Die Casting Market will depend as much on access to low-carbon primary magnesium as on installed casting tonnage.
Key Report Takeaways
• By Production Process
- Pressure Die Casting held a 62.0% share of the Automotive Parts Magnesium Die Casting Market in 2025, reflecting its cycle-time advantage for high-volume thin-wall parts.
- Vacuum Die Casting is the fastest-growing process, advancing at an 11.2% CAGR as OEMs specify weldable, low-porosity structural castings.
- Squeeze Die Casting generated USD 0.71 Billion in 2025, serving thick-section chassis and suspension components.
• By Application
- Body Parts accounted for a 41.5% share in 2025, led by instrument panel beams and liftgate inners.
- Other Applications, which include seat frames and EV e-drive housings, are expanding at a 10.8% CAGR, the fastest application growth in the Automotive Parts Magnesium Die Casting Market.
- Engine Parts contributed USD 1.10 Billion in 2025, anchored by cam covers, oil pans, and intake manifolds.
• By Region
- Asia-Pacific commanded a 46.5% share of global revenue in 2025.
- North America is growing at an 8.1% CAGR through 2035, supported by CAFE tightening and nearshored component supply.
- Europe generated USD 1.31 Billion in 2025, concentrated in Germany's premium vehicle supply base.
Market Size and Forecast (2021–2035)
Market Research Future built this series bottom-up from vehicle production data published by OICA and CAAM [9][10], per-vehicle magnesium content estimates from the International Magnesium Association [6], and revenue disclosures from leading die casters, then cross-checked it top-down against primary magnesium consumption reported by the USGS [7]. Historical values cover 2021–2024, 2025 serves as the base year, and 2026–2035 forms the forecast window. The Automotive Parts Magnesium Die Casting Market rebounded sharply in 2021 and accelerated again in 2023 once semiconductor constraints on vehicle assembly eased.



 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


