Automotive Exhaust Aftertreatment System Market Summary
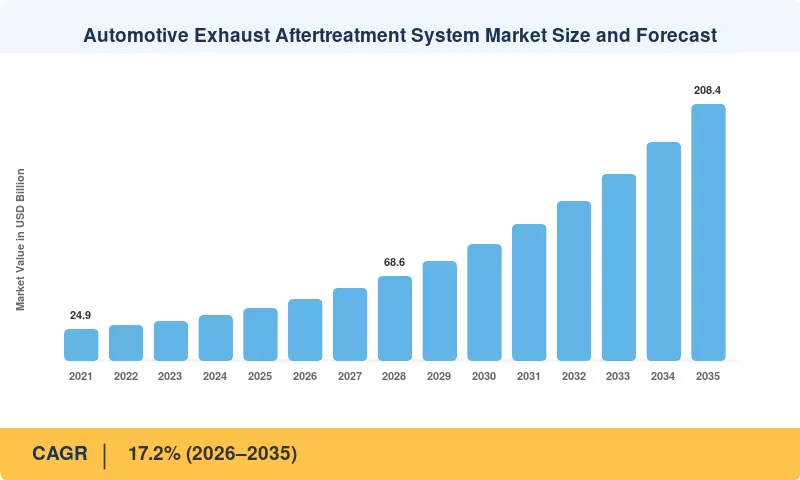
The Automotive Exhaust Aftertreatment System Market reached USD 42.6 billion in 2025 and opens the forecast window at USD 49.9 billion in 2026, climbing to USD 208.4 billion by 2035 at a 17.2% CAGR. Two regulatory catalysts anchor that trajectory. The European Union's Euro 7 regulation, adopted in April 2024, extends particulate number limits to brake and tyre emissions while holding tailpipe compliance obligations through 2035 for light vehicles [1]. In parallel, the US EPA's 2027 heavy-duty NOx standard cuts allowable oxides of nitrogen by roughly 80% against the 2010 baseline and stretches useful-life durability requirements to 800,000 miles for tractor-trailer classes [2]. Together, these rules convert aftertreatment from a cost line into a certification gate.
Hardware content per vehicle is rising faster than vehicle output. Single-brick oxidation catalysts and open-loop urea dosing are giving way to multi-stage architectures — twin-dosing SCR, electrically heated catalysts, and SCR-coated particulate filters — that place substrate, washcoat, sensor, and dosing hardware in series. Suppliers have committed accordingly: BASF Environmental Catalyst and Metal Solutions and Johnson Matthey have together directed more than USD 1.4 billion toward catalyst capacity and platinum group metal recovery lines since 2022 [3][4]. Content per heavy-duty truck now runs USD 2,900–4,600 in regulated markets, roughly double 2015 levels.
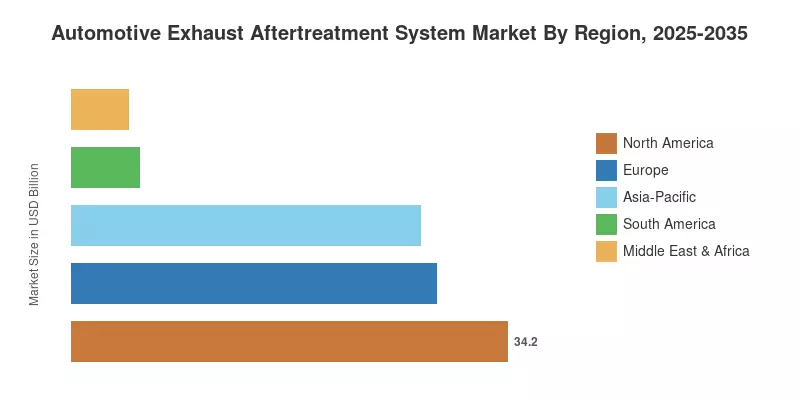
North America leads the Automotive Exhaust Aftertreatment System Market with a 34.2% revenue share in 2025, supported by EPA and CARB heavy-duty enforcement and a large Class 8 replacement parc. Asia-Pacific grows fastest at a 19.4% CAGR as China VI-b and India's BS-VI Stage 2 norms pull compliant hardware into high-volume platforms. Europe holds 28.6% on the strength of Euro 7 phase-in and a dense commercial vehicle retrofit base. Through 2035, the Automotive Exhaust Aftertreatment System Market will be shaped less by vehicle unit growth than by regulatory tightening per unit.
Key Report Takeaways
• By Fuel Type
- Diesel platforms account for 53.2% of 2025 revenue in the Automotive Exhaust Aftertreatment System Market, sustained by commercial vehicle NOx compliance
- Gasoline aftertreatment expands at a 19.1% CAGR through 2035 as particulate filtration becomes standard on direct-injection engines
• By Vehicle Type
- Passenger cars represent 58.4% of installed value, reflecting global unit volumes rather than per-unit content
- Commercial vehicles post a 18.3% CAGR, the fastest of the two, driven by extended useful-life mandates
- Content per commercial vehicle in the Automotive Exhaust Aftertreatment System Market averages USD 3,700 in regulated jurisdictions
• By Region
Market Size and Forecast (2021–2035)
Figures below combine bottom-up modelling of vehicle production by emissions tier with supplier revenue triangulation, catalyst substrate shipment data, and platinum group metal offtake volumes. Historical values are reconciled against published segment disclosures from Tenneco, FORVIA, Eberspächer, Corning, and NGK Insulators, then adjusted for intercompany sales and regional pricing differentials. Forecast years apply regulation-phase modelling: each jurisdiction's compliance deadline drives a step change in content per vehicle, layered onto a base production forecast.





 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



