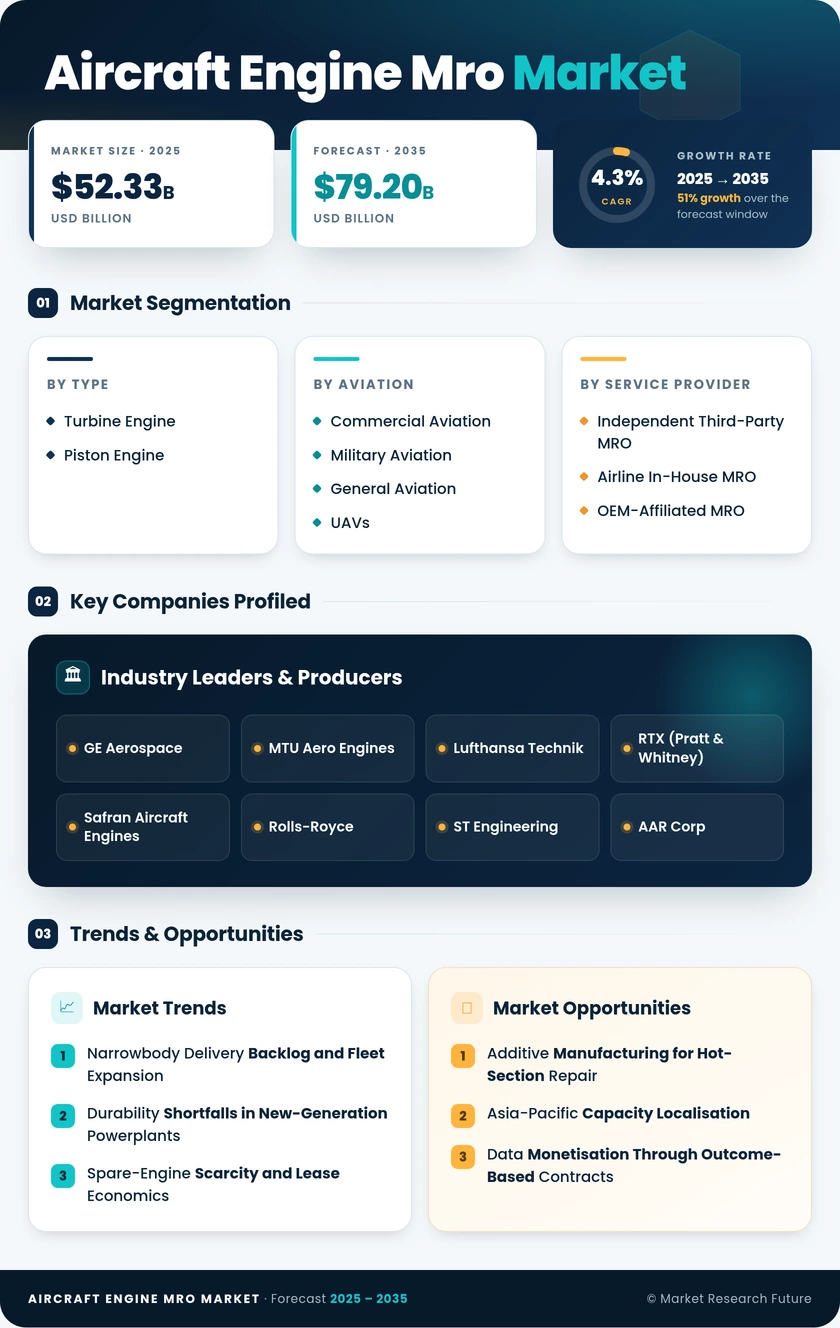
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Engine Type | Turbine Engine; Piston Engine | Turbine Engine | Turbine Engine |
| By Aviation | Commercial Aviation; Military Aviation; General Aviation; UAVs | Commercial Aviation | UAVs |
| By Service Providers | Airline In-House MRO; Independent Third-Party MRO; OEM-Affiliated MRO | Independent Third-Party MRO | OEM-Affiliated MRO |
| By Geography | North America; South America; Europe; Asia-Pacific; Middle East & Africa | North America | Asia-Pacific |
Market Segmentation Overview
By Engine Type
| Sub-Segment | Key Trend |
| Turbine Engine | New-generation turbofans entering first heavy shop visits, lifting workscope value per event |
| Piston Engine | Flight-training fleet renewal sustaining steady low-value, high-frequency overhaul volume |
Turbine architecture absorbs the overwhelming majority of spending because cycle accumulation and part cost both scale with thrust. Piston work remains a stable niche anchored to general aviation training activity rather than commercial traffic.
By Aviation
| Sub-Segment | Key Trend |
| Commercial Aviation | Narrowbody utilisation recovery driving record induction volumes |
| Military Aviation | Depot-level outsourcing expanding as readiness targets tighten |
| General Aviation | Business jet flight-hour growth extending component demand |
| UAVs | Migration from piston to turbine propulsion on endurance platforms |
Commercial demand sets the cycle, but military and unmanned work increasingly provide shops with counter-cyclical ballast. Providers holding dual civil-defence approvals capture the most stable utilisation across the forecast.
By Service Providers
| Sub-Segment | Key Trend |
| Airline In-House MRO | Sub-scale carriers divesting captive shops toward third-party coverage |
| Independent Third-Party MRO | Competing on turnaround guarantees and used serviceable material sourcing |
| OEM-Affiliated MRO | Leveraging technical data control to capture new-generation workscopes |
Provider economics are diverging. Data and tooling access — not hangar capacity — now determines which participants can bid full overhaul on the newest engine families.
By Geography
| Sub-Segment | Key Trend |
| North America | Consolidation of independent shops and deepest used serviceable material pool |
| South America | Currency exposure pushing operators toward green-time management |
| Europe | Sustainability reporting emerging as a tender differentiator |
| Asia-Pacific | Greenfield capacity build-out ending cross-hemisphere engine ferrying |
| Middle East & Africa | Desert-erosion remediation shortening intervals on widebody fleets |
Geographic value is migrating eastward as Asia-Pacific closes its capacity deficit. North America retains scale leadership through 2035, but its share of incremental growth declines steadily across the forecast.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA