中密度繊維板市場 概要
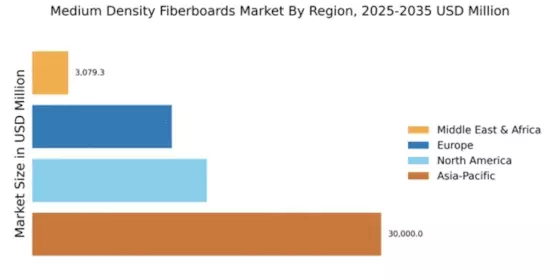
MRFR分析によると、中密度ファイバーボードの市場規模は、at 43.2 USD Billionで2024と推定されました。中密度ファイバーボード業界は、46.7 USD Billionで2025 から 2035 までに 102.7 USD Billion に成長すると予測されており、予測期間中に 8.2% の年間複合成長率 (CAGR) を示します。 2025 - 2035。
主要な市場動向とハイライト
中密度ファイバーボード市場は、持続可能性とカスタマイズの需要によってダイナミックな変化を経験しています。
- 北米は依然として中密度ファイバーボードの最大の市場であり、堅調な家具産業と建設産業が牽引しています。 アジア太平洋地域は、急速な都市化とインフラプロジェクトの増加により、最も急速に成長している地域として認識されています。 家具セグメントが市場を支配し続けている一方、床材セグメントが最も高い成長率を示しています。 主要な市場推進力には、製品の提供と消費者の好みを形成する持続可能性とカスタマイズへの重点が含まれます。
市場規模と予測
| 2024 市場規模 | 43.2 (USD Billion) |
| 2035 市場規模 | 102.7 (USD Billion) |
| CAGR (2025 - 2035) | 8.2% |
| 最大の地域市場シェアで2024 | アジア太平洋地域 |
主要なプレーヤー
Kronospan (AT)、Egger (AT)、Arauco (CL)、Louisiana-Pacific Corporation (US)、MDF Recovery (US)、Sonae Industria (PT)、Masisa (CL)、Finsa (ES)、Greenply Industries (IN)、デュラテックス(BR)



 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



