Linear Alkyl Benzene Market Summary
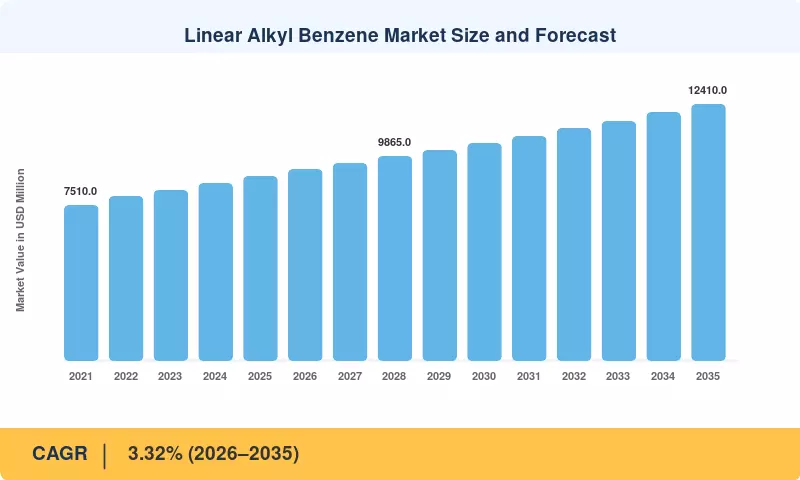
The Linear Alkyl Benzene Market reached USD 8,940.0 Million in 2025 and opens the forecast window at USD 9,240.0 Million in 2026, climbing to USD 12,410.0 Million by 2035 at a 3.32% CAGR. Volume-linked demand tracks detergent consumption in emerging economies, where per-capita cleaning spend continues to rise. Saudi Arabia's Vision 2030 downstream program and Algeria's Sonatrach petrochemical expansion plan together anchor roughly USD 2.1 billion of announced alkylation and n-paraffin capacity, and both leverage advantaged feedstock plus government-backed financing [1][3].
Technology substitution is reshaping unit economics across the Linear Alkyl Benzene Market. Legacy hydrofluoric-acid alkylation trains — long the sector's liability exposure — are giving way to fixed-bed solid-acid Detal and Detal-2 configurations that eliminate HF handling and cut process carbon intensity by roughly 12–15% per tonne. Asia-Pacific refiners have committed above USD 640 million since 2023 to alkylation retrofits, while predictive-maintenance analytics lift operating rates two to three points at existing plants [2][6].
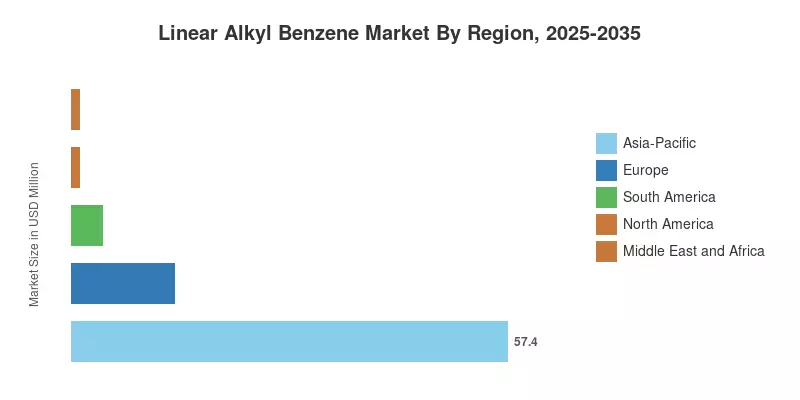
Regional hierarchy remains concentrated. Asia-Pacific holds a 57.4% share of the Linear Alkyl Benzene Market and also grows fastest at 4.53% CAGR, powered by India, Indonesia, and Vietnam detergent volume. Middle East and Africa rank second on the strength of integrated, feedstock-advantaged export plants, while Europe and North America run mature, replacement-driven demand. Through 2035, incremental supply will concentrate where captive benzene and n-paraffin streams already exist.
Key Report Takeaways
• By Application
- Surfactant applications hold 90.4% of Linear Alkyl Benzene Market revenue in 2025, reflecting the material's entrenched position in sulfonated actives
- Other Applications — agrochemical emulsifiers, textile auxiliaries, specialty coatings — advance at 4.87% CAGR through 2035
• By End-User Industry
- Laundry detergents account for 66.9% of Linear Alkyl Benzene Market volume, spanning both powder and liquid formats
- Light-duty dishwashing liquids grow at 4.19% CAGR as rural households in emerging Asia shift away from bar soap
- Industrial cleaners contribute approximately USD 690.0 Million in 2025, sustained by post-pandemic sanitation protocols
• By Region
- Asia-Pacific commands 57.4% of the global Linear Alkyl Benzene Market in 2025
- Middle East and Africa expands at 4.02% CAGR on export-oriented greenfield capacity
- North America generates roughly USD 1,090.0 Million, with demand tied to concentrated liquid formats
Market Size and Forecast (2021–2035)
Market Research Future builds the Linear Alkyl Benzene Market size series from a bottom-up reconciliation of nameplate alkylation capacity, published operating rates, customs trade flows for benzene and n-paraffin, and detergent-formulation active-matter loadings. Historical values are cross-checked against producer annual reports and national petrochemical association statistics; forecast years apply a demand-side model weighted by household formation, urbanisation and per-capita detergent intensity.
Driver Impact Analysis
| Driver |
~% Impact on CAGR |
Geographic Relevance |
Impact Timeline |
Ref |
| Detergent penetration in emerging economies |
+1.05 |
Asia-Pacific, Africa |
Long-term (≥4 yr) |
[4] |
| Detail-2 and solid-acid alkylation conversion |
+0.52 |
Global |
Medium-term (2–4 yr) |
[2] |
| Advantaged-feedstock greenfield capacity |
+0.48 |
Middle East, North Africa |
Long-term (≥4 yr) |
[1][3]
|
| Liquid detergent format migration |
+0.41 |
Asia-Pacific, Europe |
Medium-term (2–4 yr) |
|
| Institutional and hygiene cleaning demand |
+0.34 |
North America, Europe |
Short-term (≤2 yr) |
[9] |
| Cold-water and concentrated formulation shift |
+0.29 |
Europe, Japan |
Medium-term (2–4 yr) |
[10] |
| Predictive-maintenance-driven capacity uplift |
+0.23 |
Global |
Short-term (≤2 yr) |
[6] |
Detergent Penetration in Emerging Economies
India's per-capita detergent consumption sits near 3.2 kg annually against 10–12 kg in mature markets, and the World Bank projects 240 million additional urban residents across South and Southeast Asia by 2035 [4]. Each percentage point of penetration gain translates into roughly 28,000 tonnes of incremental sulfonation feed. Indonesia and Vietnam post detergent volume growth above 6% annually. This structural pull, not price, is the single largest contributor to the forecast.
Detal-2 and Solid-Acid Alkylation Conversion
UOP's Detal-2 platform removes hydrofluoric acid from the alkylation loop entirely, cutting utility consumption around 15% and lowering 2-phenyl variability. Retrofit economics improved sharply after 2023, when insurance premiums on HF-route assets rose an estimated 18–22% following tightened process-safety underwriting [2]. Producers converting units gain both a compliance buffer and a measurable yield advantage, allowing them to hold contract share against low-cost import volumes entering coastal Asia.
Advantaged-Feedstock Greenfield Capacity
Saudi Arabia's downstream localisation program earmarked more than USD 1.4 billion for aromatics-linked derivatives through 2030, with LAB among the targeted chains [1]. Algeria's Sonatrach separately advanced a 100,000-tonne complex leveraging domestic kerosene-derived n-paraffin [3]. Both projects carry sovereign-backed financing and export orientation, adding supply at cash costs roughly 14% below the Asian import-parity benchmark and reshaping regional trade flows through the early 2030s.
Liquid Detergent Format Migration
Liquid formats require LAB grades with higher 2-phenyl content for foam stability, commanding a USD 60–90 per tonne premium over powder-grade material. Liquid share of Asian laundry sales rose from 19% in 2021 to roughly 31% in 2025. Producers with dual-capable sulfonation assets capture the spread. The migration also raises active-matter loading per wash cycle, lifting consumption intensity independent of household count growth.
Institutional and Hygiene Cleaning Demand
US healthcare and food-service cleaning chemical spend held above pre-2020 levels, with the CDC's environmental surface protocols retained by an estimated 78% of surveyed acute-care facilities through 2025 [9]. Logistics hubs and quick-service kitchens sustain elevated degreaser volumes. While smaller than laundry, this pool converts quickly and delivers stable contract offtake, giving producers a short-cycle demand floor when household channels soften on price.
Cold-Water and Concentrated Formulation Shift
The EU Ecodesign framework and Japan's energy-efficiency labelling push formulators toward 20–30 °C wash performance, which requires narrow molecular-weight-distribution grades to avoid haze [10]. Concentrated liquids reduce packaging volume but raise active percentage per unit, so LAB per litre climbs even as bottle counts fall. European formulators reported roughly 11% higher active loading in reformulated concentrates launched since 2023.
Predictive-Maintenance Driven Capacity Uplift
Digital reliability programs at integrated producers lifted alkylation unit availability by two to three percentage points, equivalent to roughly 70,000 tonnes of latent global supply unlocked without capital expansion [6]. Vibration analytics on paraffin dehydrogenation reactors and fouling prediction on HF or solid-acid beds cut unplanned outages by around 24% at reporting sites. The effect is modest on price but materially improves asset utilisation economics.
Restraints Impact Analysis
| Restraint |
~% Impact on CAGR |
Geographic Relevance |
Impact Timeline |
Ref |
| Benzene and n-paraffin price volatility |
−0.61 |
Global |
Short-term (≤2 yr) |
[7] |
| SAF-driven kerosene diversion |
−0.38 |
Europe, North America |
Long-term (≥4 yr) |
[11] |
| HF-route liability and insurance costs |
−0.27 |
Global |
Medium-term (2–4 yr) |
[2] |
| Bio-based surfactant substitution |
−0.24 |
Europe, North America |
Long-term (≥4 yr) |
[12] |
| Overcapacity and import price pressure |
−0.19 |
Asia-Pacific |
Medium-term (2–4 yr) |
[5] |
Benzene and n-Paraffin Price Volatility
Between 2022 and 2024, benzene contract prices fluctuated by more than 40% from peak to trough, and feedstock accounts for about 72% of LAB cash costs [7]. Due to annual price ceilings negotiated by detergent clients, the gap is absorbed by non-integrated producers. Mid-size Asian and European converters have frequently postponed debottlenecking decisions due to margin compression of USD 80–110 per ton during spike quarters.
SAF-Driven Kerosene Diversion
Sustainable aviation fuel mandates under ReFuelEU require 6% blending by 2030, redirecting kerosene fractions that would otherwise yield n-paraffin [11]. European n-paraffin availability could tighten by an estimated 9% by the early 2030s. Producers without captive Molex or equivalent separation units face structurally higher input costs, and some have begun securing multi-year paraffin supply agreements at premium terms.
HF-Route Liability and Insurance Costs
Hydrofluoric acid is still used in around one-third of the world's alkylation capacity. A number of countries strengthened setback and mitigation rules, and post-2023 underwriting assessments increased process-safety premiums on those assets by an estimated 18–22% [2]. In comparison to integrated majors, smaller operators are stranded, and their reinvestment cycle is slowed by the USD 40–70 million conversion capital hurdle per unit.
Bio-Based Surfactant Substitution
Alkyl polyglucosides and methyl ester sulfonates gained share in premium European detergent SKUs, with roughly 7% of new 2024 launches carrying a bio-based primary surfactant claim [12]. Cost remains 1.6–2.1× conventional actives, limiting penetration to mid- and premium tiers. The threat is slow-moving but persistent, concentrated in regulated markets with strong eco-label adoption.
Overcapacity and Import Price Pressure
Asian nameplate capacity exceeds regional demand by an estimated 11%, and export cargoes routinely undercut domestic contract prices by USD 50–75 per tonne [5]. Smaller regional converters respond by running flexible sulfonation assets across powder and liquid grades. Sustained oversupply caps price realisation and pushes producers toward service and formulation support to defend accounts.
Linear Alkyl Benzene Market Opportunities
High-Purity Grades for Concentrated Formats
Concentrated liquid detergents demand narrow molecular-weight-distribution LAB with tightly controlled 2-phenyl content to avoid haze and viscosity drift. These grades sell at USD 70–120 per tonne over commodity material and face limited competition, since only units with modern fractionation and solid-acid alkylation can hold specification consistently. Producers investing in analytical capability and joint formulation labs with brand owners capture disproportionate margin in a chain otherwise defined by commodity spreads.
Agrochemical Emulsifier Diversification
LAB-derived emulsifiers improve tank-mix stability in herbicide and insecticide concentrates, a niche growing faster than the core detergent pool. Brazilian and Indian agrochemical formulators expanded emulsifiable concentrate output through 2025, and qualification cycles create durable supplier lock-in. Volumes remain small relative to laundry, but pricing is negotiated on performance rather than commodity indices, offering a margin buffer when detergent contracts reset downward.
African and South Asian Demand Gaps
Despite detergent volume growth outpacing regional GDP growth, Sub-Saharan Africa imports most of its sulfonated actives. Together, Nigeria, Kenya, and Ethiopia constitute an addressable pool that is not covered by local sulfonation capacity, while Middle Eastern producers are well located in terms of freight distance. In order to avoid Asian import rivalry, regional blending and sulfonation joint ventures are established, converting export tons into higher-value local supply agreements.
Reliability Analytics as a Commercial Service
Integrated producers that built predictive-maintenance stacks for their own alkylation and dehydrogenation units can license the models to toll converters and smaller regional plants. Availability gains of two to three points translate directly into recoverable tonnage, and the offering monetises operating data without capital exposure. Several licensors already bundle analytics with technology packages, signalling that recurring-revenue models are viable in a traditionally licence-and-walk-away business.
Low-Carbon Product Certification
Formulators increasingly request verified cradle-to-gate carbon figures for surfactant inputs, driven by retailer scope-3 reporting. Producers running Detal-2 with renewable-power-sourced utilities can document intensity roughly 12–15% below the HF-route benchmark and convert that into preferred-supplier status. Certification cost is modest relative to the contract volume it protects, particularly in European and Japanese accounts where eco-labelling governs shelf placement.
Linear Alkyl Benzene Market Future Outlook
Process Digitalisation and Autonomous Operations
Alkylation and dehydrogenation units are becoming the proving ground for closed-loop process control in commodity petrochemicals. Advanced process control tied to real-time 2-phenyl analytics allows operators to hold grade specification with less giveaway, and early adopters report yield improvements near 1.5%. The IEA estimates industrial digitalisation could deliver 5–8% energy-intensity reduction across chemical processing by 2035 [13]; for LAB producers running on thin spreads, that translates into a defensible cost position rather than a headline capability.
Feedstock Reconfiguration and Circular Inputs
Kerosene diversion toward sustainable aviation fuel forces a structural rethink of n-paraffin sourcing. IRENA projects SAF production capacity rising sharply through 2035, tightening the paraffin pool available to detergent alkylate [14]. Expect more long-term paraffin offtake agreements, selective investment in dedicated separation units, and pilot work on bio-derived paraffin routes. Producers with integrated refinery positions gain optionality; merchant buyers face a widening cost gap that no amount of operational efficiency fully closes.
Sustainability Disclosure and Product Carbon Accounting
Surfactant providers are directly impacted by retailer scope-3 commitments. In European and Japanese accounts, verified cradle-to-gate carbon intensity is becoming a qualification requirement rather than a marketing asset, and Detal-2 operators are able to report far lower numbers than their HF-route counterparts [2][15]. These claims will be comparable across suppliers thanks to standardized product carbon footprint procedures that are now being developed. This will turn what is currently a differentiation story into a simple pass-fail screen for tender participation.
Supply Geography Rebalancing
Incremental capacity through 2035 concentrates in Saudi Arabia and Algeria, where feedstock advantage and state-backed financing overcome the return hurdles that deter merchant investors elsewhere [1][3]. Those tonnes will target Southern Europe, West Africa and South Asia, compressing the freight-adjusted margin available to Asian exporters. World Bank trade projections point to rising South-South chemical flows through the period [4]. The result is a flatter, more contested global cost curve than the one that prevailed through the 2010s.
Regional Market Share Analysis
| Region |
Metric (2025) |
Primary Investment Themes |
| Asia-Pacific |
57.4% share |
Capacity debottlenecking, liquid-grade flexibility |
| Middle East and Africa |
USD 1,340.0 Million |
Advantaged-feedstock greenfield export plants |
| Europe |
13.6% share |
Detail conversion, cold-water grade development |
| North America |
USD 1,090.0 Million |
Concentrated liquid formats, institutional cleaning |
| South America |
4.1% share |
Agrochemical emulsifiers, import substitution |
| Total |
100.0% / USD 8,940.0 Million |
— |
The Linear Alkyl Benzene Market remains structurally weighted toward Asia-Pacific, where detergent consumption growth, domestic capacity and export flows converge. Middle East and Africa is the swing supplier region, while Europe and North America display replacement-led demand shaped by formulation regulation rather than volume expansion.
Asia-Pacific
| Country |
Share of Region |
Key Driver |
| China |
38.4% |
Large integrated capacity, export cargoes |
| India |
24.1% |
Rising per-capita detergent consumption |
| Japan |
9.2% |
Cold-water concentrated formulations |
| South Korea |
6.8% |
Export-oriented sulfonation and toll processing |
| Rest of Asia-Pacific |
21.5% |
Indonesia and Vietnam volume growth |
Asia-Pacific combines the deepest demand pool with the most aggressive technology upgrade cycle. Chinese producers have converted several alkylation trains to solid-acid configurations, while India's household-goods sector benefits from rural distribution expansion under national retail formalisation efforts. Indonesian and Vietnamese detergent output grew above 6% annually through 2025, and much of that volume converts to liquid formats requiring higher-2-phenyl grades. Regional overcapacity nonetheless caps price realisation, pushing producers toward grade differentiation rather than tonnage competition [5].
Middle East and Africa
| Country |
Share of Region |
Key Driver |
| Saudi Arabia |
47.6% |
Vision 2030 downstream localisation |
| South Africa |
16.3% |
Regional detergent manufacturing hub |
| Rest of Middle East and Africa |
36.1% |
Algerian capacity, Sub-Saharan import demand |
Feedstock advantage defines this region's position. Saudi Arabian producers access captive benzene and kerosene-derived n-paraffin at costs well below import-parity benchmarks, and the kingdom's downstream program directs sovereign-backed financing toward derivative chains including LAB [1]. Algeria's Sonatrach complex adds export tonnage aimed at Southern Europe and West Africa [3]. South African converters serve a mature domestic detergent industry, while Sub-Saharan demand remains largely import-dependent — a gap regional producers are positioned to close.
Europe
| Country |
Share of Region |
Key Driver |
| Germany |
23.7% |
Concentrated liquid detergent manufacturing |
| United Kingdom |
14.2% |
Retailer eco-label requirements |
| France |
13.5% |
Institutional and professional cleaning demand |
| Italy |
11.8% |
Private-label detergent production |
| Russia |
12.4% |
Domestic capacity and regional export |
| Rest of Europe |
24.4% |
Nordic and Iberian formulation activity |
Regulation, not volume, drives European dynamics. Ecodesign and detergent-regulation revisions push formulators toward cold-water efficacy and concentrated formats, both of which favour high-purity grades over commodity material [10]. ReFuelEU aviation mandates simultaneously tighten n-paraffin availability, raising input risk for producers without captive separation capacity [11]. German and Italian converters have responded by locking multi-year paraffin contracts, while UK retailers' eco-label thresholds increasingly determine which surfactant inputs qualify for shelf placement.
North America
| Country |
Share of Region |
Key Driver |
| United States |
78.9% |
Institutional cleaning and concentrated liquids |
| Canada |
12.6% |
Import-supplied detergent manufacturing |
| Mexico |
8.5% |
Growing household cleaning consumption |
North American demand is mature and format-driven. Concentrated liquid detergents dominate retail shelves, sustaining active-matter loadings even as unit volumes flatten. Institutional cleaning provides the region's most reliable growth pocket, with healthcare and food-service surface protocols retained well beyond the pandemic period [9]. Canadian formulators rely substantially on imported LAB, while Mexican household consumption continues to expand with urbanisation, drawing cargoes from both US Gulf Coast and Asian suppliers depending on freight economics.
South America
| Country |
Share of Region |
Key Driver |
| Brazil |
61.2% |
Detergent manufacturing and agrochemical emulsifiers |
| Argentina |
18.7% |
Domestic household cleaning demand |
| Rest of South America |
20.1% |
Andean import-supplied formulation |
Brazil anchors the region on two fronts: a large domestic detergent industry and an agrochemical sector that consumes LAB-derived emulsifiers in emulsifiable concentrate formulations. Currency volatility periodically distorts import economics, prompting formulators to hold larger inventories than global norms. Argentine demand tracks household consumption closely and has been constrained by macroeconomic pressure, while Andean countries depend almost entirely on imported material, creating openings for regional sulfonation investment.
Linear Alkyl Benzene Market Segmentation
By Application
| Segment |
Metric (2025) |
Primary Demand Driver |
| Surfactant |
90.4% share |
Sulfonated actives for household and industrial cleaning |
| Other Applications |
4.87% CAGR |
Agrochemical emulsifiers, textile auxiliaries, coatings |
Surfactant use dominates the Linear Alkyl Benzene Market because sulfonated LAB delivers a cost-to-performance ratio that alcohol ethoxysulfates struggle to match at scale. Household detergents, institutional cleaners, and industrial degreasers all default to it. Other Applications grow faster from a small base as agrochemical formulators adopt LAB-derived emulsifiers for tank-mix stability and coatings producers shift toward water-based emulsions requiring compatible surfactant chemistry.
By End-User Industry
| Segment |
Metric (2025) |
Primary Demand Driver |
| Laundry Detergents |
66.9% share |
Powder and liquid detergent volume in emerging Asia |
| Light-Duty Dishwashing Liquids |
4.19% CAGR |
Rural transition from bar soap, piped water access |
| Industrial Cleaners |
USD 690.0 Million |
Hospital, logistics and food-service sanitation |
| Household Cleaners |
8.3% share |
Multi-surface and hard-surface cleaner formulations |
| Other End-user Industries |
3.44% CAGR |
Textile processing, oilfield and niche formulations |
Laundry detergents anchor the Linear Alkyl Benzene Market and will continue to, but light-duty dishwashing liquids set the growth pace as piped-water access expands across South and Southeast Asia. Industrial cleaners deliver steady contract offtake sustained by retained sanitation protocols. Household cleaners track multi-surface product proliferation, while other end-user industries remain small, specification-driven pools where qualification cycles create supplier stickiness.
Competitive Benchmarking
The Linear Alkyl Benzene Market is moderately fragmented, with an estimated HHI in the 700–850 range and a top-five combined share near 41–46%. Integration is the decisive variable: producers holding captive benzene and n-paraffin streams sustain margin through feedstock cycles, while merchant converters absorb volatility. Regional players with flexible sulfonation assets remain competitive by pivoting between powder and liquid grades, but they face persistent import pressure. Incumbents combining integration, Detal-2 technology, and digital reliability programs are best positioned against low-cost entrants.
| Company |
Est. Revenue Share Range |
Key Offerings for Linear Alkyl Benzene Market |
Strategic Positioning |
| CEPSA Química |
~11–14% |
Full LAB grade range, LABSA, high-purity detergent alkylate |
Integrated European leader with global sales network |
| Sasol |
~8–11% |
LAB, alcohols, blended surfactant intermediates |
Feedstock-integrated, strong African and European base |
| Farabi Petrochemicals |
~7–10% |
LAB, normal paraffins, heavy alkylate |
Advantaged Saudi feedstock, export-oriented |
| Reliance Industries |
~6–9% |
LAB from integrated aromatics complex |
Scale-driven cost leadership in South Asia |
| Indian Oil Corporation |
~5–8% |
Detergent-grade LAB, n-paraffin |
Domestic supply security, refinery-integrated |
| Qatar Petrochemical / QAPCO affiliates |
~4–7% |
LAB and linear alkylate exports |
Gulf export platform with captive feedstock |
| ISU Chemical |
~4–6% |
LAB, LAB-derived intermediates |
Korean toll and export processing specialist |
| Fushun Petrochemical (PetroChina) |
~4–6% |
Detergent alkylate for domestic formulators |
Anchors Chinese domestic supply |
| Deten Química |
~3–5% |
LAB, LABSA for South American formulators |
Regional leader in Brazil and Andean markets |
| Honeywell UOP (technology licensor) |
~3–5% |
Detal and Detal-2 alkylation technology packages |
Sets process standard; licensing and services model |
| Tamimi Group / Saudi affiliates |
~2–4% |
Regional LAB distribution and blending |
Gulf logistics and downstream service position |
Recent News & Developments
- Honeywell UOP (March 2023): Expanded Detal-2 licensing to two Asian refiners, positioning solid-acid alkylation as the default retrofit path away from hydrofluoric acid units [2]
- European Commission (April 2024): Progressed detergent regulation revisions tightening labelling and biodegradability documentation, raising qualification requirements for surfactant inputs [10]
- Farabi Petrochemicals (July 2024): Completed a debottlenecking program at its Yanbu complex, adding export capacity aimed at South Asian and African buyers [1]
- Deten Química (February 2025): Signed multi-year supply agreements with Brazilian agrochemical formulators for emulsifier-grade material, extending beyond its detergent base [12]
- ISU Chemical (June 2025): Announced sulfonation flexibility upgrades enabling faster switching between powder-grade and liquid-grade production runs [5]



 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


