太空军事化市场 摘要
主要市场趋势和亮点
市场规模与预测
| CAGR (2025 - 2035) | 4.31% |
| CAGR (2025 - 2035) | 4.31% |
The Space Militarization Market is currently experiencing a notable evolution, driven by a confluence of geopolitical tensions and technological advancements. Nations are increasingly recognizing the strategic importance of space as a domain for defense and security operations. This recognition has led to heightened investments in satellite systems, space-based surveillance, and missile defense technologies. As countries seek to enhance their capabilities, the market is likely to witness a surge in demand for innovative solutions that can provide a competitive edge in space operations. Furthermore, the collaboration between governmental and private entities appears to be fostering a dynamic environment for research and development, potentially leading to breakthroughs in space technology. In addition to the technological advancements, the regulatory landscape surrounding the Space Militarization Market is evolving. Governments are establishing frameworks to govern the use of space for military purposes, which may influence market dynamics. The increasing focus on space security and the potential for conflict in outer space necessitate a comprehensive approach to policy-making. As nations navigate these complexities, the market may see a shift towards more collaborative efforts in ensuring the peaceful use of space while simultaneously preparing for potential threats. Overall, the Space Militarization Market is poised for growth, driven by a combination of strategic imperatives and technological innovation.
Countries are allocating more resources towards developing advanced space defense systems. This trend reflects a growing recognition of the need to protect national interests in outer space, leading to innovations in satellite technology and missile defense systems.
The collaboration between government agencies and private companies is becoming more prevalent. These partnerships are fostering innovation and accelerating the development of new technologies, which may enhance the capabilities of military operations in space.
As the Space Militarization Market expands, governments are establishing new regulations to manage military activities in outer space. This trend indicates a shift towards more structured governance, aiming to balance national security needs with international cooperation.
The current landscape of international relations appears increasingly fraught with tension, particularly among major powers. This situation has led to a pronounced focus on the Space Militarization Market, as nations seek to bolster their defense capabilities in space. The potential for conflict in space has prompted governments to allocate substantial budgets towards the development of advanced space technologies. For instance, military expenditures related to space operations are projected to reach approximately USD 30 billion by 2026. This trend indicates a growing recognition of space as a critical domain for national security, thereby driving investments in satellite systems, missile defense, and space situational awareness. As countries strive to secure their interests in this new frontier, the Space Militarization Market is likely to experience robust growth.
The Space Militarization Market is characterized by a diverse range of product types. Among these, Satellites hold the largest market share, largely due to their crucial role in reconnaissance, communication, and navigation. Launch Vehicles follow closely, driven by increasing demand to deploy these high-tech satellites into orbit. Ground Stations and defense electronics also contribute to the overall landscape, but their presence is comparatively smaller in this dynamic market.
Satellites (Dominant) vs. defense electronics (Emerging)
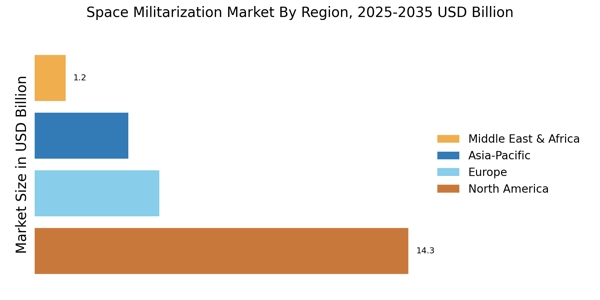
North America is the largest market for space militarization, holding approximately 60% of the global share. The region's growth is driven by increasing defense budgets, technological advancements, and a focus on national security. Regulatory support from agencies like NASA and the Department of Defense further catalyzes market expansion, fostering innovation and collaboration among private and public sectors. The United States leads the market, with key players such as Lockheed Martin, Northrop Grumman, and Raytheon Technologies dominating the landscape. The competitive environment is characterized by significant investments in R&D and partnerships with government entities. Canada also plays a role, focusing on satellite technology and defense capabilities, contributing to the overall growth of the North American market.
Europe is emerging as a significant player in the space militarization market, holding around 20% of the global share. The region's growth is fueled by collaborative defense initiatives among EU member states, increased funding for space programs, and a focus on enhancing security capabilities. Regulatory frameworks established by the European Space Agency (ESA) and the European Union are pivotal in driving innovation and investment in space technologies. Leading countries include France, Germany, and the United Kingdom, with key players like Airbus and Thales Group actively participating in the market. The competitive landscape is marked by partnerships between governments and private firms, aiming to develop advanced satellite systems and defense technologies. The European market is characterized by a strong emphasis on sustainability and dual-use technologies, aligning military and civilian applications.
Asia-Pacific is witnessing rapid growth in the space militarization market, accounting for approximately 15% of the global share. The region's expansion is driven by increasing geopolitical tensions, rising defense budgets, and advancements in space technology. Countries like China and India are investing heavily in their space programs, supported by government initiatives aimed at enhancing national security and technological capabilities. China is the largest market in the region, with significant investments in satellite and missile technologies. India is also emerging as a key player, focusing on indigenous development of defense systems. The competitive landscape is characterized by a mix of state-owned enterprises and private firms, fostering innovation and collaboration in the space sector. The presence of major players like Boeing and Lockheed Martin further enhances the region's capabilities in space militarization.
The Middle East and Africa region is gradually increasing its footprint in the space militarization market, holding about 5% of the global share. The growth is driven by rising defense expenditures, regional conflicts, and a strategic focus on enhancing national security through advanced technologies. Countries like the UAE and South Africa are leading the charge, supported by government initiatives aimed at developing space capabilities and fostering international collaborations. The UAE is particularly notable for its ambitious space program, including the Mars mission and investments in satellite technologies. South Africa is also making strides in developing its defense capabilities. The competitive landscape is characterized by partnerships with global defense firms and a focus on technology transfer, aiming to build local expertise in space militarization.
The Space Militarization Market is currently characterized by a dynamic competitive landscape, driven by technological advancements and geopolitical tensions. Key players such as Lockheed Martin (US), Northrop Grumman (US), and Raytheon Technologies (US) are at the forefront, each adopting distinct strategies to enhance their market positioning. Lockheed Martin (US) emphasizes innovation in satellite technology and missile defense systems, while Northrop Grumman (US) focuses on integrating artificial intelligence into its defense solutions. Raytheon Technologies (US) is actively pursuing partnerships to expand its capabilities in space-based surveillance and reconnaissance, collectively shaping a competitive environment that prioritizes technological superiority and strategic collaborations.In terms of business tactics, companies are increasingly localizing manufacturing and optimizing supply chains to enhance operational efficiency. The market appears moderately fragmented, with a mix of established players and emerging firms vying for market share. The collective influence of these key players is significant, as they leverage their technological expertise and government contracts to maintain a competitive edge.
In August Lockheed Martin (US) announced a partnership with the U.S. Space Force to develop advanced satellite systems aimed at enhancing national security. This strategic move underscores Lockheed's commitment to innovation and its role in bolstering the United States' defense capabilities in space. The collaboration is expected to yield cutting-edge technologies that could redefine space operations.
In September Northrop Grumman (US) unveiled a new AI-driven satellite system designed to improve data processing and threat detection in real-time. This initiative highlights Northrop's focus on integrating advanced technologies into its offerings, positioning the company as a leader in the rapidly evolving space defense sector. The deployment of AI in satellite operations may significantly enhance operational efficiency and responsiveness.
In July Raytheon Technologies (US) secured a contract with NATO to provide advanced surveillance systems for space operations. This contract not only expands Raytheon's footprint in the international defense market but also reflects the growing importance of multinational collaborations in addressing security challenges. The strategic alliance with NATO is likely to enhance Raytheon's capabilities and market reach.
As of October current trends in the Space Militarization Market indicate a strong emphasis on digitalization, sustainability, and AI integration. Strategic alliances are increasingly shaping the competitive landscape, as companies recognize the need for collaboration to address complex security challenges. Looking ahead, competitive differentiation is expected to evolve, with a shift from price-based competition to a focus on innovation, technological advancements, and supply chain reliability. This transition may redefine how companies position themselves in the market, emphasizing the importance of cutting-edge solutions and strategic partnerships.
BAE Systems advances resilient missile-warning satellite program:
In March 2026, BAE Systems completed the Preliminary Design Review for the U.S. Space Force’s Resilient Missile Warning & Tracking Medium Earth Orbit Epoch 2 program. The company is expected to build 10 spacecraft and provide associated ground-system capabilities for missile warning and tracking, including advanced threats such as hypersonic glide vehicles.
Airbus strengthens European secure military communications:
In April 2026, Airbus, Thales Alenia Space, and RADMOR announced an industrial cooperation agreement for a geostationary defense telecommunications satellite for Poland’s Ministry of Defence. The planned system is intended to provide secure, resilient communications for Polish armed forces and strengthen national and European space sovereignty.
太空军事化市场预计将在2024年至2035年间以4.31%的年均增长率增长,推动因素包括卫星技术的进步、国防预算的增加以及地缘政治紧张局势。
新机遇在于:
到2035年,太空军事化市场预计将会强劲,反映出战略投资和技术进步。
| MARKET SIZE 2024 | 23.84(USD Billion) |
| MARKET SIZE 2025 | 24.86(USD Billion) |
| MARKET SIZE 2035 | 37.92(USD Billion) |
| COMPOUND ANNUAL GROWTH RATE (CAGR) | 4.31% (2025 - 2035) |
| REPORT COVERAGE | Revenue Forecast, Competitive Landscape, Growth Factors, and Trends |
| BASE YEAR | 2024 |
| Market Forecast Period | 2025 - 2035 |
| Historical Data | 2019 - 2024 |
| Market Forecast Units | USD Billion |
| Key Companies Profiled | Lockheed Martin (US), Northrop Grumman (US), Raytheon Technologies (US), Boeing (US), Airbus (DE), Thales Group (FR), Leonardo (IT), BAE Systems (GB), General Dynamics (US) |
| Segments Covered | Application, End Use, Technology, Product Type, Regional |
| Key Market Opportunities | Advancements in satellite technology and defense systems drive growth in the Space Militarization Market. |
| Key Market Dynamics | Rising geopolitical tensions drive investment in space defense technologies and military capabilities among leading nations. |
| Countries Covered | North America, Europe, APAC, South America, MEA |
 Triveni Bhoyar

 Sejal Akre
The secondary research process involved comprehensive analysis of defense policy databases, satellite industry publications, government procurement records, and authoritative aerospace organizations. Key sources included:
Government & Defense Agencies:
US Department of Defense (DoD) & Space Force (SpaceForce.mil)
National Aeronautics and Space Administration (NASA) Office of Safety and Mission Assurance
European Space Agency (ESA) Security Programs
UK Space Agency & Ministry of Defence Space Directorate
French Direction Générale de l'Armement (DGA)
German Federal Office of Bundeswehr Equipment (BAAINBw)
Japan Aerospace Exploration Agency (JAXA) Defense Coordination
Indian Space Research Organisation (ISRO) Military Applications
Russian Roscosmos & Ministry of Defense Space Units
China National Space Administration (CNSA) Military-Civil Fusion reports
International Organizations & Regulatory Bodies:
United Nations Office for Outer Space Affairs (UNOOSA) Space Security Index
NATO Cooperative Cyber Defence Centre of Excellence
Organisation for Economic Co-operation and Development (OECD) Space Economy Reports
World Economic Forum (WEF) Global Risks Report – Space Security
Secure World Foundation Space Threat Assessments
Center for Strategic and International Studies (CSIS) Aerospace Security Project
Union of Concerned Scientists (UCS) Satellite Database
Industry & Technical Sources:
Satellite Industry Association (SIA) State of the Satellite Industry Reports
Space Foundation Space Report Quarterly
Eurospace European Space Industry Facts & Figures
Bryce Tech Space Start-up Series
Defense Advanced Research Projects Agency (DARPA) Public Solicitations
Missile Defense Agency (MDA) Budget Documentation
Federation of American Scientists (FAS) Space Policy Database
Financial & Market Intelligence:
US Government Accountability Office (GAO) Defense Acquisitions Reports
Defense News & SpaceNews Market Analysis
Euroconsult Government Space Programs Reports
Northern Sky Research (NSR) Satellite & Space Market Forecasts
SpaceWorks Commercial Space Transportation Study
These sources were used to collect defense budget allocations, satellite launch manifests, anti-satellite (ASAT) testing documentation, space situational awareness (SSA) capabilities, military satellite constellations, and geopolitical threat assessments across surveillance, satellite communication, missile defense, space exploration, and cyber defense applications.
Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. Supply-side sources comprised CEOs, VPs of Government Programs, principal engineers for space systems, and business development directors from prime defense contractors, satellite manufacturers, launch service providers, and space technology subcontractors. The demand-side sources included intelligence community technology directors, procurement leaders from defense ministries, program executive officers for space systems, policy advisors from national security councils, and flag officers from military space commands. Primary research has confirmed the product development timelines for next-generation defense satellites and responsive launch capabilities, validated market segmentation across satellite technology, launch vehicle technology, ground control systems, and space robotics, and gathered insights on classified program budget trends, international technology transfer restrictions, and public-private partnership frameworks.
Primary Respondent Breakdown:
By Designation: C-level Primaries (28%), Director Level (32%), Others (40%)
By Region: North America (32%), Europe (24%), Asia-Pacific (34%), Rest of World (10%)
Global market valuation was derived through defense budget analysis and satellite deployment tracking. The methodology included:
Identification of 50+ key stakeholders across North America, Europe, Asia-Pacific, Middle East, and Latin America, including prime contractors (Lockheed Martin, Boeing, Northrop Grumman), emerging launch providers (SpaceX, Rocket Lab), and national space agencies with military mandates
Product mapping across satellites (reconnaissance, communications, navigation), launch vehicles (expendable and reusable), ground stations (command & control, telemetry), and defense electronics (payloads, encryption systems)
Analysis of reported and modeled annual revenues specific to classified and unclassified space defense portfolios, utilizing Freedom of Information Act (FOIA) releases, parliamentary budget disclosures, and contract award notifications
Coverage of manufacturers and service providers representing 65-70% of global market share in 2024
Extrapolation using bottom-up (unit deployment × program cost by country) and top-down (defense budget
请填写以下表格以获取本报告的免费样本

“This is really good guys. Excellent work on a tight deadline. I will continue to use you going forward and recommend you to others. Nice job”
 Noah Malgeri
Co-Founder

“Thanks for sending the report it gives us a good global view of the Betaïne market.”
 Peter Groot koerkamp
Account and Business Manager

“We found the report very insightful! we found your research firm very helpful. I'm sending this email to secure our future business.”
 Younghwan Choi
Senior Retail Manager

“I am very pleased with how market segments have been defined in a relevant way for my purposes (such as "Portable Freezers & refrigerators" and "last-mile"). In general the report is well structured. Thanks very much for your efforts.”
 Mark Irwin
Management Consultant

“We got the report in time, we really thank you for your support in this process. I also thank to all of your team as they did a great job.”
 Akif Moroglu
Strategy & Business Development Director

“The Automotive 48V ECU Components Procurement Intelligence Study” was a complex project, but the Market Research Future (MRFR) team handled it with quality, agility, and customer-centricity. They delivered all requested data on time and within the agreed scope. The team, including Shubhendra Anand and Rahul Gotadki, was always readily available to clarify questions and swiftly implement necessary adjustments, driving the project to a successful conclusion within a very demanding timeframe.
I would also like to specifically commend Akshay Agarwal for his responsiveness and support at every stage—from our initial inquiry on May 6th through to final delivery on June 18th. His dedication made the entire process seamless.”
 Guilherme Gomes Martins
Product Management Director

“Thanks. It’s been a pleasure working with you, please use me as reference with any other Intel employees.”
 Joseph Aguayo
Sales Operations & Pricing Manager

“Thank you, this will be very helpful for OQS.”
 La Terria Dodd
Program Support Specialist

“I have been reading the first document or the study, ,the Global HVAC and FP market report 2021 till 2026. Must say, good info! I have not gone in depth at all parts, but got a good indication of the data inside!”
 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



