Agriculture Robots Market

农业机器人市场规模、份额及研究报告按类型(单功能农业机器人{除草、播种、喷洒、收获、其他},按其他 - 单功能农业机器人类型{耕作、翻耕、松土、施肥、其他}),多功能农业机器人{播种-除草-施肥、播种-灌溉-施肥-除草-监测、田间分析-土壤平整-土壤湿度分析),按地区(美国、欧洲、澳大利亚、韩国)–行业预测至2035年
ID: MRFR/SEM/8669-CR 200 Pages Apoorva Priyadarshi, Aarti Dhapte Last Updated: September 24, 2026
Agriculture Robots Market
Market Size
Forecast Period2025 - 2035
CAGR (2025 - 2035)15.81%
2024 Market Size$ 3,665.6 Million
2025 Market Size$ 4,245.21 Million
2035 Market Size$ 18,426.18 Million
Key Players
John Deere
AG Leader Technology
Trimble
CNH Industrial
Yamaha Motor Co
Harvest Automation
Opportunities
  • Labor Shortages
  • Rising Food Demand
  • Sustainability Initiatives

Agriculture Robots Market 摘要

根据MRFR的分析,农业机器人市场规模在2024年预计为3665.6百万美元。农业机器人行业预计将从2025年的4245.21百万美元增长到2035年的18426.18百万美元,在2025年至2035年的预测期内,年均增长率(CAGR)为15.81%。

主要市场趋势和亮点

农业机器人市场正经历强劲增长,推动因素包括技术进步和对可持续实践的日益需求。

  • 市场见证了精准农业的广泛采用,特别是在北美,北美仍然是最大的市场。
  • 人工智能的整合正在改变操作,提高作物监测和自主拖拉机的效率。
  • 可持续实践正在获得关注,反映了整个行业对环境管理的更广泛承诺。
  • 不断上升的劳动力成本和政府支持计划是推动收获和无人机细分市场增长的重要驱动力。

市场规模与预测

2024市场规模 3665.6(百万美元)
2035市场规模 18426.18(百万美元)
年均增长率(2025 - 2035) 15.81%

主要参与者

约翰迪尔(美国),AG领导科技(美国),特里姆布尔(美国),CNH工业(英国),雅马哈汽车公司(日本),收获自动化(美国),蓝河科技(美国),Naïo科技(法国),Octinion(比利时)

Agriculture Robots Market Drivers

劳动力短缺

农业部门的劳动力短缺是全球农业机器人行业亟待解决的一个紧迫问题。许多地区的农业工人数量正在减少,这可能会阻碍生产力和作物产量。作为回应,农民们越来越多地转向机器人技术来填补这一空缺。例如,机器人收割机可以高效地收集作物,从而减少对人工劳动的依赖。随着行业预计到2035年将达到184亿美元,这一趋势可能会加速,推动创新解决方案的需求,以应对劳动力短缺并维持农业产出。

食品需求上升

全球农业机器人行业受到全球食品需求上升的显著影响,这一需求是由人口增长和饮食偏好的变化驱动的。预计到2050年,全球人口将达到约97亿,这对农业系统生产更多食品的压力正在加大。机器人技术可以提高生产力和效率,使农民能够满足这些需求。例如,自动化种植和收割系统可以在降低劳动力成本的同时提高作物产量。这种对增加食品生产的日益迫切需求可能会推动市场向前发展,因为利益相关者寻求创新解决方案以确保食品安全。

可持续发展倡议

可持续发展倡议正成为全球农业机器人行业的一个焦点,因为消费者和政府都要求采取更环保的做法。农业机器人可以通过优化资源使用、减少化学投入和最小化土壤扰动来促进可持续农业。例如,精准农业技术允许对肥料和农药进行定向施用,这可以降低对环境的影响。随着可持续性越来越受到重视,预计市场将在2025年至2035年间以15.81%的复合年增长率增长,反映出行业对生态友好农业实践的承诺。

技术进步

全球农业机器人市场正经历快速的技术进步,这些进步提高了效率和生产力。机器人技术、人工智能和机器学习的创新使得开发能够执行多种任务(如种植、收割和监测作物)的复杂农业机器人成为可能。例如,配备GPS技术的自主拖拉机可以在最小的人为干预下运行,优化资源使用。随着这些技术的发展,预计将推动市场的增长,行业预计在2024年将达到36.7亿美元,表明对先进农业解决方案的强烈需求。

政府支持和资金

政府支持和资金在全球农业机器人行业的发展中发挥着至关重要的作用。许多政府正在认识到农业机器人在提高食品生产和可持续性方面的潜力。诸如补助金、补贴和研究资金等倡议正在实施,以鼓励该领域的创新。例如,各国正在投资于旨在开发先进农业技术的研究项目。这种支持可能会促进行业的增长,因为它鼓励在农业实践中采用机器人技术和自动化。

市场细分洞察

获取关于Agriculture Robots Market的更多详细见解

区域洞察

北美:创新与领导中心

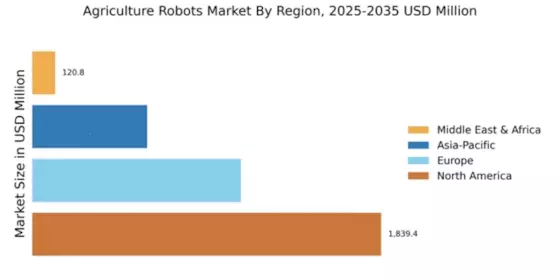
北美在2024年以1839.36百万美元的市场份额领先农业机器人市场,受到技术进步和对农业自动化需求增加的推动。该地区受益于强大的研发投资、良好的政府政策和日益关注可持续实践。对精准农业和环境可持续性的监管支持进一步促进了市场增长,使其成为全球市场的重要参与者。美国作为最大的市场,拥有约翰迪尔、AG领导科技和特里姆布尔等主要参与者。这些公司处于创新的前沿,开发出提升生产力和效率的尖端解决方案。竞争格局的特点是战略合作伙伴关系和合作,旨在扩大产品供应和市场覆盖,确保北美在农业机器人领域的主导地位。

欧洲:新兴技术的采用

欧洲的农业机器人市场价值为1099.68百万美元,反映出由于劳动成本上升和向自动化转变而推动的强劲增长轨迹。该地区正在见证对精准农业技术的需求激增,受到欧盟法规的支持,促进可持续农业实践。旨在减少环境影响和增强粮食安全的举措是市场扩展的关键驱动因素,使欧洲成为全球舞台上的重要参与者。德国、法国和荷兰等领先国家在这一转型中处于前沿,CNH工业和Naïo科技等主要参与者在此拥有强大的市场存在。竞争格局以创新和合作为特征,各公司努力满足农民不断变化的需求。人工智能和物联网技术的整合进一步提高了操作效率,使欧洲成为农业机器人创新的中心。

亚太地区:快速增长与采用

亚太地区的农业机器人市场价值为605.76百万美元,由于对农业生产力的需求增加和劳动力短缺而迅速扩展。日本和澳大利亚等国正在引领这一潮流,受到技术进步和政府旨在现代化农业的倡议的推动。该地区对增强粮食安全和可持续性的关注正在推动农业机器人在农业中的采用,使其成为未来几年增长的关键领域。竞争格局中有雅马哈汽车公司和收获自动化等主要参与者,他们正在创新以应对该地区独特的挑战。技术公司与农业利益相关者之间的合作正在促进农业机器人领域的活跃生态系统。随着市场的成熟,智能技术的整合将在塑造亚太地区未来农业中发挥关键作用,确保效率和可持续性。

中东和非洲:未开发的潜力与增长

中东和非洲的农业机器人市场价值为120.8百万美元,处于初期阶段,但显示出显著的增长潜力。食品需求增加、水资源短缺和高效农业实践的需求等因素正在推动对农业自动化的兴趣。该地区的政府开始认识到技术在农业中的重要性,导致支持性政策和投资,旨在提高生产力和可持续性。南非和阿联酋等国正在成为采用农业机器人技术的领导者,专注于针对当地挑战的创新解决方案。主要参与者的存在逐渐增加,促进了鼓励创新的竞争格局。随着对自动化好处的认识不断提高,中东和非洲有望成为农业机器人领域的重要参与者。

Agriculture Robots Market Regional Image

Agriculture Robots Market市场的主要公司包括

Recent Industry Developments

  • Q3 2026: CNH Industrial (GB): New Holland presented its R4 autonomous robots at Motor Valley Fest 2026, demonstrating app-based agricultural automation using GPS, LiDAR, and vision cameras for vineyards, orchards, and specialty crops.
  • Q3 2026: Yamaha Motor Co (JP): Yamaha Motor opened a dedicated Robotics Business Support Division in Gurugram, India, strengthening sales and service infrastructure for its robotics portfolio and supporting expansion of the company’s robotics business in the growing Indian market.
  • Q2 2024: Agtonomy raises $22.5M Series A to scale autonomous farm equipment Agtonomy, a California-based startup developing autonomous and remote-operated farm machinery, secured $22.5 million in Series A funding to accelerate product development and expand commercial deployments.
  • Q2 2024: John Deere Unveils New Autonomous Sprayer at 2024 World Ag Expo John Deere launched its latest autonomous sprayer, designed to reduce chemical use and labor requirements, at the 2024 World Ag Expo, marking a significant product expansion in its agricultural robotics portfolio.
  • Q2 2024: Naïo Technologies secures €32 million to expand agricultural robot fleet French agri-robotics company Naïo Technologies raised €32 million in a new funding round to scale up production and accelerate international growth of its autonomous weeding and harvesting robots.
  • Q2 2024: CNH Industrial acquires Augmenta to boost precision agriculture automation CNH Industrial announced the acquisition of Augmenta, a provider of real-time precision farming solutions, to enhance its automation and robotics capabilities in the agricultural sector.
  • Q3 2024: Blue River Technology appoints new CEO to drive next phase of ag robotics growth Blue River Technology, a subsidiary of John Deere specializing in AI-powered agricultural robots, named a new CEO to lead the company’s expansion and product innovation strategy.
  • Q3 2024: Ecorobotix raises $48 million in Series C funding for AI-powered weeding robots Swiss agtech firm Ecorobotix closed a $48 million Series C round to accelerate the commercialization of its AI-driven weeding robots, which aim to reduce herbicide use and improve crop yields.
  • Q3 2024: Yanmar launches new strawberry-picking robot for Japanese market Yanmar, a Japanese machinery manufacturer, introduced a new autonomous robot designed specifically for strawberry harvesting, targeting labor shortages in Japan’s fruit farming sector.
  • Q4 2024: FarmWise partners with Driscoll’s to deploy autonomous weeding robots in berry fields FarmWise, a U.S.-based ag robotics company, announced a partnership with Driscoll’s to deploy its autonomous weeding robots across Driscoll’s berry farms, aiming to improve efficiency and sustainability.
  • Q4 2024: AGCO opens new robotics R&D center in Germany AGCO Corporation inaugurated a new research and development center in Germany focused on advancing agricultural robotics and automation technologies for European markets.
  • Q1 2025: John Deere acquires SmartAg for autonomous tractor technology John Deere completed the acquisition of SmartAg, a developer of autonomous tractor solutions, to strengthen its leadership in farm automation and robotics.
  • Q1 2025: Small Robot Company secures £15 million to scale commercial robot farming UK-based Small Robot Company raised £15 million in new funding to expand the deployment of its autonomous robots for precision weeding and crop monitoring on commercial farms.
  • Q2 2025: Kubota and Tevel partner to commercialize fruit-picking drones in Europe Kubota, a leading agricultural machinery manufacturer, announced a partnership with Israeli startup Tevel to bring autonomous fruit-picking drones to European orchards, addressing labor shortages and boosting productivity.

未来展望

Agriculture Robots Market 未来展望

预计农业机器人市场将在2025年至2035年间以15.81%的年均增长率增长,推动因素包括技术进步、劳动力短缺和对可持续农业实践的日益需求。

到2035年,农业机器人市场预计将成为现代农业的基石,提高生产力和可持续性。

市场细分

农业机器人市场类型展望

  • 自主拖拉机
  • 无人机
  • 机器人收割机
  • 除草机器人
  • 种植机器人

农业机器人市场最终用途展望

  • 农业
  • 园艺
  • 水产养殖
  • 林业
  • 温室

农业机器人市场技术展望

  • 人工智能
  • 机器学习
  • 计算机视觉
  • GPS技术
  • 遥感

农业机器人市场应用展望

  • 作物监测
  • 土壤分析
  • 收割
  • 种植
  • 除草

报告范围

2024年市场规模 3665.6(百万美元)
2025年市场规模 4245.21(百万美元)
2035年市场规模 18426.18(百万美元)
复合年增长率(CAGR) 15.81%(2025 - 2035)
报告覆盖范围 收入预测、竞争格局、增长因素和趋势
基准年 2024
市场预测期 2025 - 2035
历史数据 2019 - 2024
市场预测单位 百万美元
主要公司简介 约翰迪尔(美国),AG领导科技(美国),特里姆布尔(美国),CNH工业(英国),雅马哈汽车公司(日本),收获自动化(美国),蓝河科技(美国),Naïo科技(法国),Octinion(比利时)
覆盖的细分市场 应用、类型、技术、最终用途
主要市场机会 人工智能的整合提高了农业机器人市场的效率和精准度。
主要市场动态 技术进步推动竞争力量,提高了农业机器人在多样化农业实践中的效率和采用。
覆盖的国家 北美、欧洲、亚太、南美、中东和非洲

Frequently Asked Questions

2024年农业机器人市场的当前估值是多少?

农业机器人市场在2024年的估值约为3665.6百万美元。

2035年农业机器人市场的预计市场规模是多少?

预计到2035年,市场估值将达到约18426.18百万美元。

在2025年至2035年的预测期内,农业机器人市场的预期年均增长率是多少?

农业机器人市场预计在2025年至2035年期间以15.81%的年均增长率增长。

2024年哪个应用细分市场的估值最高?

在2024年,收割应用细分市场以920.0百万美元的估值领先。

目前主导市场的农业机器人主要类型有哪些?

目前市场主要由如机器人收割机等类型主导,2024年的估值为900.0百万美元。

2024年自主拖拉机的估值与无人机相比如何?
在2024年,自主拖拉机的估值为800.0百万美元,而无人机的估值为600.0百万美元。
2024年农业机器人市场中哪个最终用途细分市场占据最大份额?
农场代表了最大的最终用途细分市场,2024年的估值为1099.68百万美元。
哪家公司被认为是农业机器人市场的关键参与者?
约翰·迪尔被认为是农业机器人市场的关键参与者,对其增长做出了重要贡献。
2024年除草应用细分市场的估值是多少?
除草应用细分市场在2024年的估值为845.6百万美元。
2024年种植机器人市场与除草机器人市场相比如何?
在2024年,种植机器人的估值为765.6百万美元,而除草机器人的估值为600.0百万美元。
作者
Author Author Profile Apoorva Priyadarshi LinkedIn Research Analyst
With 4+ years of experience in Market Intelligence and Strategic Research, Apoorv specializes in ICT, Semiconductor, and BFSI markets. Combining strong analytical capabilities with a deep understanding of technology-driven industries, he focuses on delivering data-driven insights that support strategic decision-making. With a background in technology and business research, Apoorv has contributed to numerous global market studies, competitive landscape analyses, and opportunity assessments across sectors such as semiconductors, digital banking, cybersecurity, and telecommunications.
Co-Author Co-Author Profile Aarti Dhapte LinkedIn AVP - Research
A consulting professional focused on helping businesses navigate complex markets through structured research and strategic insights. I partner with clients to solve high-impact business problems across market entry strategy, competitive intelligence, and opportunity assessment. Over the course of my experience, I have led and contributed to 100+ market research and consulting engagements, delivering insights across multiple industries and geographies, and supporting strategic decisions linked to $500M+ market opportunities. My core expertise lies in building robust market sizing, forecasting, and commercial models (top-down and bottom-up), alongside deep-dive competitive and industry analysis. I have played a key role in shaping go-to-market strategies, investment cases, and growth roadmaps, enabling clients to make confident, data-backed decisions in dynamic markets.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed agricultural engineering journals, robotics publications, and authoritative agricultural organizations. Key sources included the US Department of Agriculture (USDA), European Commission Agriculture and Rural Development (DG AGRI), Food and Agriculture Organization of the United Nations (FAO), International Federation of Robotics (IFR), American Society of Agricultural and Biological Engineers (ASABE), PrecisionAg Institute, USDA National Agricultural Statistics Service (NASS), EUROSTAT Agricultural Statistics, Organisation for Economic Co-operation and Development (OECD) Agricultural Statistics, National Institute of Food and Agriculture (NIFA), Agricultural Robotics and Automation Technical Committee (IEEE Robotics & Automation Society), and national agricultural machinery associations from key markets (Germany's VDMA, Japan's JAMA, China's CAAMM). These sources were used to collect agricultural automation adoption rates, regulatory approval data for autonomous farm equipment, robotics safety standards, demographic trends in farm labor, and market landscape analysis for milking robots, harvesting robots, unmanned aerial vehicles (UAVs/drones), driverless tractors, and material management robots.


Primary Research

To gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research phase. Commercial directors from agricultural robot manufacturers, autonomous tractor OEMs, and precision agriculture technology suppliers were among the supply-side sources, as were CEOs, CTOs of Robotics Engineering, VPs of Agricultural Solutions, and regulatory affairs heads for autonomous machinery certification. Farm operators, agricultural cooperative managers, vineyard managers, dairy farm owners, precision agriculture consultants, and procurement leads from large-scale agribusinesses, family farms, agricultural service providers, and government agricultural extension offices were among the demand-side sources. Primary research confirmed product pipeline timelines for next-generation autonomous systems, validated market segmentation across hardware (UAVs, milking robots, driverless tractors, harvesting robots, material management systems) and software (data analytics, AI/ML platforms, fleet management), and collected information on pricing models (RaaS vs. CapEx), subsidy/reimbursement dynamics, and barriers to technology adoption.

Primary Respondent Breakdown:

Table

Copy

Category Segment Percentage

By Company Tier Tier 1 (>$5B revenue) 38%

Tier 2 ($500M-$5B revenue) 31%

By Designation C-level Primaries 28%

Director Level 32%

Others (Managers, Engineers, Farm Operators) 40%

By Region North America 32%

Europe 29%

Asia-Pacific 31%

Rest of World (Latin America, Middle East & Africa) 8%
 

Market Size Estimation

Global market valuation was derived through revenue mapping and unit shipment analysis. The methodology included:

Identification of 50+ key manufacturers across North America, Europe, Asia-Pacific, and Latin America specializing in agricultural robotics

Product mapping across UAVs/drones, milking robots, driverless tractors, harvesting robots, and material management systems (automated guided vehicles, robotic weeders)

Analysis of reported and modeled annual revenues specific to agricultural robotics portfolios, including precision agriculture software subscriptions

Coverage of manufacturers representing 65-70% of global market share in 2024

Extrapolation using bottom-up (unit shipments × ASP by region/crop type) and top-down (manufacturer revenue validation, venture capital investment tracking) approaches to derive segment-specific valuations

Adjustment for agricultural commodity price cycles and seasonal purchasing patterns affecting robotics adoption

Integration of government subsidy programs (EU CAP subsidies for precision ag, USDA NRCS conservation innovation grants) impacting effective market pricing

Data Triangulation

下载免费样本

请填写以下表格以获取本报告的免费样本

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.