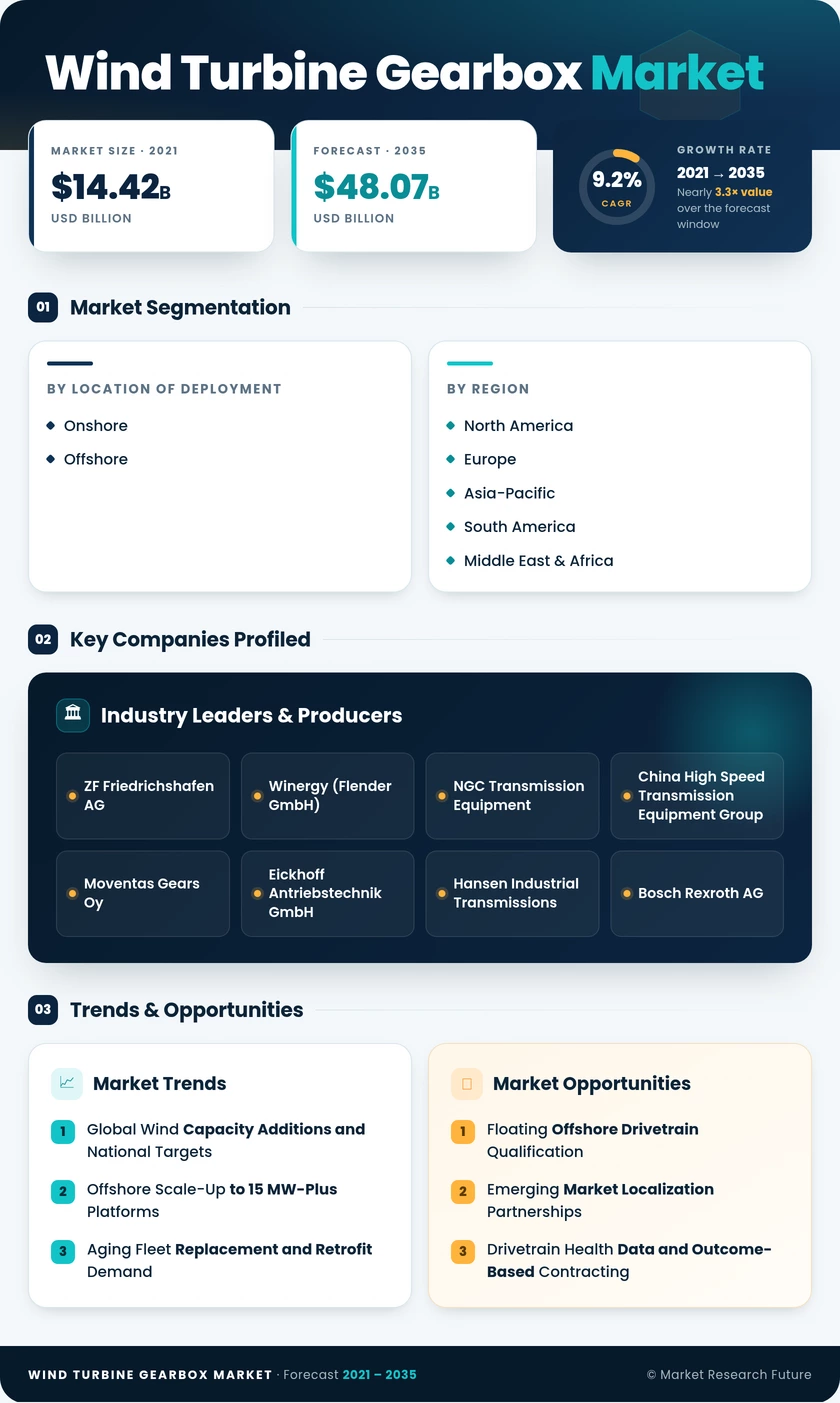
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Location Of Deployment | Onshore, Offshore | Onshore (71.6% share, 2025) | Offshore (12.1% CAGR, 2026–2035) |
| By Region | North America, Europe, Asia-Pacific, South America, Middle East & Africa | Asia-Pacific (46.8% share, 2025) | Asia-Pacific (46.8% share, 2025) |
Market Segmentation Overview
By Location Of Deployment
| Sub-Segment | Key Trend |
| Onshore | Mid-life replacement and partial repowering sustain volume as new-build ratings plateau near 6–8 MW |
| Offshore | Torque density and thermal management requirements rise sharply as platforms move past 15 MW. |
Onshore holds 71.6% of 2025 revenue because the global installed base of geared turbines below 8 MW is enormous and generates predictable exchange demand across China, the United States and Germany. Offshore grows fastest at a 12.1% CAGR, driven by auction pipelines in the North Sea, Taiwan Strait and Japanese coastal zones where 15 MW-plus platforms are now standard tender specifications. The two sub-segments attract different buyer logic: onshore purchasers optimize installed cost and parts availability. In contrast, offshore purchasers pay validation premiums because vessel-dependent repairs can cost more than the component itself. That divergence is why suppliers increasingly maintain separate onshore and offshore product families rather than scaling one design across both.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA