Segmentation Quick Reference
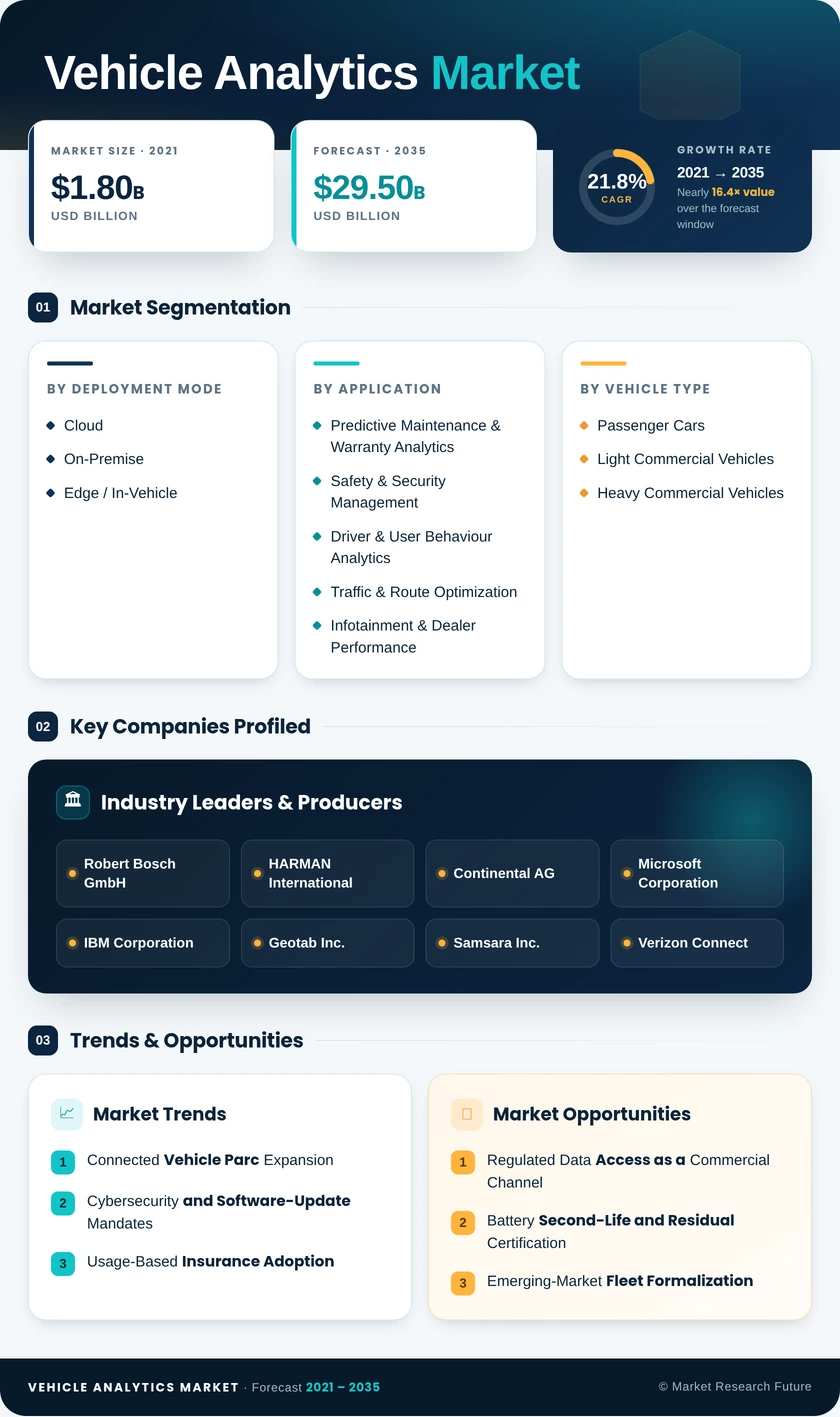
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Deployment Mode | Cloud; On-Premise; Edge / In-Vehicle | Cloud | Edge / In-Vehicle |
| By Application | Predictive Maintenance & Warranty Analytics; Safety & Security Management; Driver & User Behaviour Analytics; Traffic & Route Optimization; Infotainment & Dealer Performance | Predictive Maintenance & Warranty Analytics | Driver & User Behaviour Analytics |
| By Vehicle Type | Passenger Cars; Light Commercial Vehicles; Heavy Commercial Vehicles | Passenger Cars | Light Commercial Vehicles |
| By End User | OEMs; Fleet Owners & Operators; Insurance Providers; Service Providers & Dealers; Regulatory & Municipal Bodies | OEMs | Service Providers & Dealers |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | North America | Asia-Pacific |
Market Segmentation Overview
By Deployment Mode
| Sub-Segment | Key Trend |
| Cloud | Standardization on hyperscaler automotive ingestion services with per-vehicle consumption pricing |
| On-Premise | Retained by OEMs treating powertrain calibration data as protected intellectual property |
| Edge / In-Vehicle | Zonal compute architectures enable local inference, cutting transmission volumes sharply |
Deployment decisions increasingly follow data-residency law rather than cost curves. European and Chinese programs default to in-region or on-premises storage, while North American fleet operators adopt cloud almost universally.
By Application
| Sub-Segment | Key Trend |
| Predictive Maintenance & Warranty Analytics | Warranty reserve reduction delivers single-year payback, securing recurring OEM budget |
| Safety & Security Management | Event data recorder and cybersecurity mandates convert this into non-discretionary spend |
| Driver & User Behaviour Analytics | Insurers shift from dongles to direct OEM feeds for underwriting inputs |
| Traffic & Route Optimization | Municipal congestion and low-emission zone programs create public-sector demand |
| Infotainment & Dealer Performance | Aftersales retention analytics tie service revenue to connected engagement |
Application spending concentrates where a measurable financial line item exists. Warranty and insurance applications dominate precisely because their returns are auditable, while traffic optimization depends on public budgets and moves on slower procurement cycles.
By Vehicle Type
| Sub-Segment | Key Trend |
| Passenger Cars | Embedded connectivity now standard on most new models, expanding the addressable base |
| Light Commercial Vehicles | Last-mile delivery density drives the steepest route and utilization analytics adoption |
| Heavy Commercial Vehicles | Uptime economics and hours-of-service compliance sustain the deepest per-unit spend |
Passenger volume leads on scale, but commercial vehicles generate higher revenue per unit because operators tie analytics directly to margin. That gap narrows as personal-vehicle insurance telematics reaches broader penetration.
By End User
| Sub-Segment | Key Trend |
| OEMs | Largest total spend but heavy in-house build, purchasing selectively at the platform layer |
| Fleet Owners & Operators | Buy complete platforms, switch vendors readily, negotiate aggressively on per-vehicle pricing |
| Insurance Providers | Move from pilots to portfolio-wide risk pricing using consented behavioral inputs |
| Service Providers & Dealers | Fastest-growing buyer group as aftersales retention becomes measurable |
| Regulatory & Municipal Bodies | Compliance monitoring and public mobility programs anchor tender-based procurement |
Buyer sophistication varies widely across this dimension. OEMs conduct multi-year technical evaluations, while fleet operators often decide within a quarter based on pilot results — a difference that shapes vendor go-to-market cost structures materially.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA