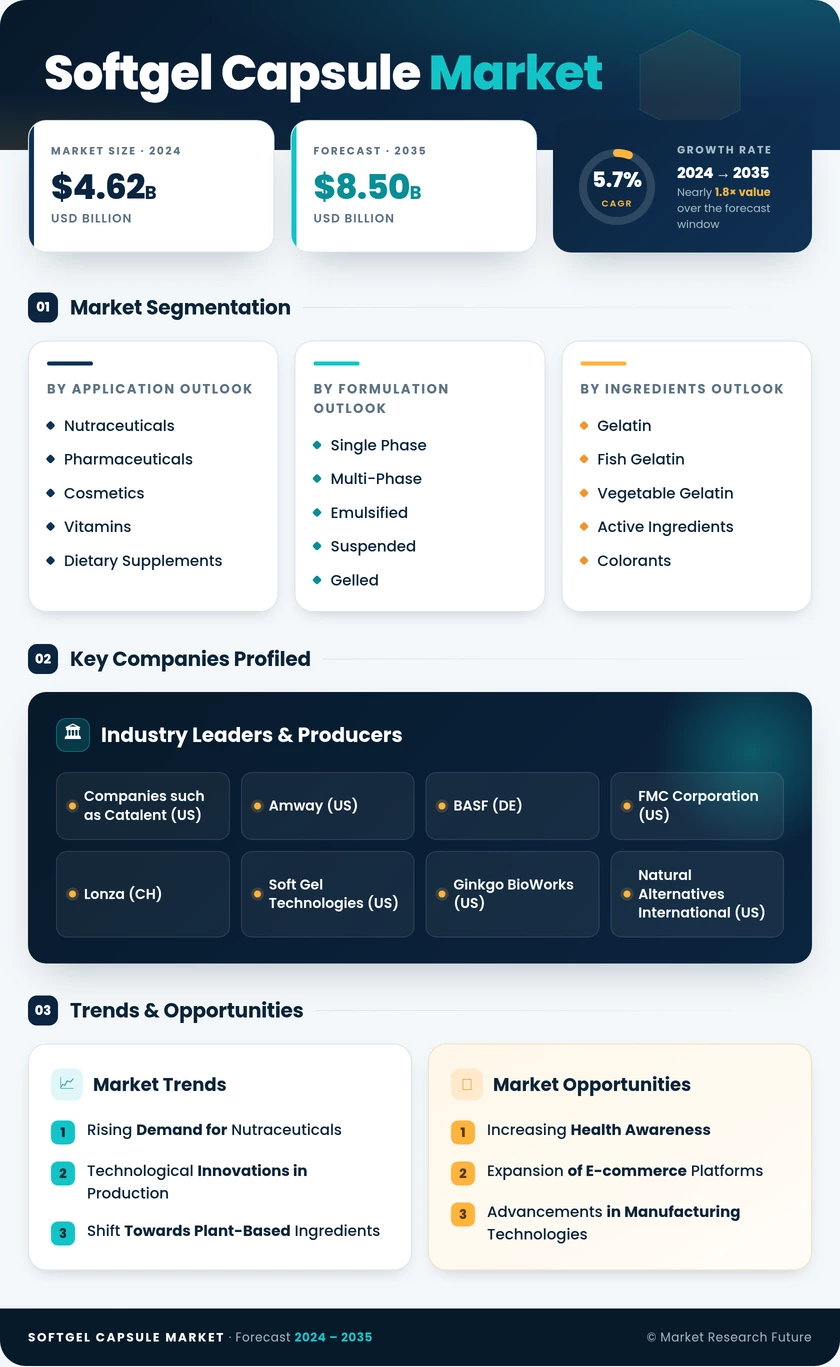
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Shell Source | Gelatin (Animal-Based); Non-Animal-Based | Gelatin (Animal-Based) | Non-Animal-Based |
| By Application | Pharmaceuticals; Nutraceuticals and Dietary Supplements; Cosmetics and Personal Care; Other Applications | Pharmaceuticals | Nutraceuticals and Dietary Supplements |
| By Geography | North America; Europe; Asia-Pacific; Middle East and Africa; South America | North America | Asia-Pacific |
Market Segmentation Overview
By Shell Source
| Sub-Segment | Key Trend |
| Gelatin (Animal-Based) | Retains volume leadership on cost and validation depth, but exposed to hide and bone price cycles |
| Non-Animal-Based | Pullulan, starch, and hypromellose systems scale rapidly on certification and clean-label demand. |
Shell chemistry now determines commercial access as much as technical performance. Encapsulators that run both animal and plant ribbon lines under one quality system capture the widest customer base, while single-chemistry sites face growing tender exclusions in Europe and the Gulf.
By Application
| Sub-Segment | Key Trend |
| Pharmaceuticals | Lipid-based delivery for poorly soluble actives sustains premium pricing and long validation cycles. |
| Nutraceuticals and Dietary Supplements | Direct-to-consumer channels and preventive health spending drive the fastest volume growth. |
| Cosmetics and Personal Care | Single-dose twist-off formats gain traction in premium East Asian skincare. |
| Other Applications | Veterinary and specialty industrial fills provide steady, low-cyclicality baseload volume. |
Application mix drives site economics more than any other variable. Pharmaceutical work carries higher margin and heavier compliance overhead; supplement work delivers throughput but compresses price. The most resilient operators deliberately blend both.
By Region
| Sub-Segment | Key Trend |
| North America | Premiumisation and vegan shell retrofits within an established regulatory base. |
| Europe | Sustainability disclosure and clean-label reformulation reshape procurement criteria. |
| Asia-Pacific | Greenfield capacity and export finishing deliver the steepest growth curve. |
| Middle East and Africa | Halal certification and localisation policy drive import substitution |
| South America | Regulatory clarity in Brazil unlocks registration and retail expansion. |
Regional divergence is widening rather than converging. Mature regions compete on capability and compliance depth; emerging regions compete on cost and proximity. Suppliers positioned in both tiers hold the strongest negotiating leverage through 2035.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA