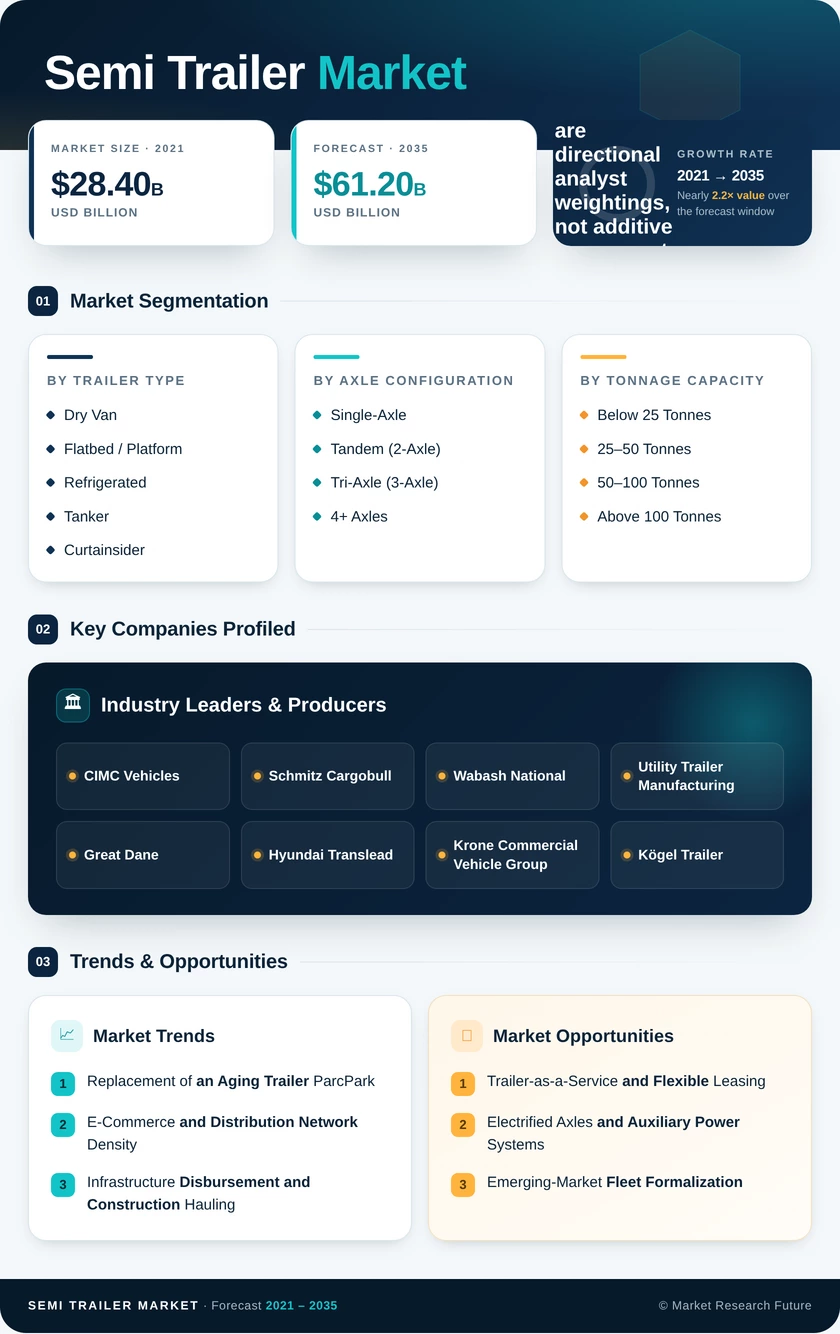
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Trailer Type | Dry Van; Flatbed / Platform; Refrigerated; Tanker; Curtainsider; Skeletal / Container Chassis; Tipper and Other | Dry Van | Refrigerated |
| By Axle Configuration | Single-Axle; Tandem (2-Axle); Tri-Axle (3-Axle); 4+ Axles | Tandem (2-Axle) | Tri-Axle (3-Axle) |
| By Tonnage Capacity | Below 25 Tonnes; 25–50 Tonnes; 50–100 Tonnes; Above 100 Tonnes | 25–50 Tonnes | Above 100 Tonnes |
| By End-Use Industry | Logistics & Transportation; Construction; Food & Beverage; Chemicals & Petroleum; Agriculture; Automotive & Industrial | Logistics & Transportation | Construction |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | North America | Asia-Pacific |
Market Segmentation Overview
By Vehicle Type
| Sub-Segment | Key Trend |
| Dry Van | Composite panel adoption improves interior width and reduces tare weight |
| Flatbed / Platform | Aluminum decking and integrated securement systems raise specification cost |
| Refrigerated | Electric and hybrid refrigeration units displace diesel-only gensets |
| Tanker | Stainless and lined configurations expand with chemical distribution demand |
| Curtainsider | Load-restraint certification tightens under European securement standards |
| Skeletal / Container Chassis | Port intermodal volumes drive gooseneck and slider chassis renewal |
| Tipper and Other | Lightweight bodies extend payload within fixed axle-load ceilings |
Body style determines nearly everything downstream — financing terms, residual value, service intervals and driver training. Dry vans anchor the volume base because of their resale liquidity, while refrigerated units capture disproportionate value growth as instrumentation and emissions compliance push average selling prices upward.
By Axle Configuration
| Sub-Segment | Key Trend |
| Single-Axle | Urban distribution and light-freight applications sustain a narrow niche |
| Tandem (2-Axle) | Remains the North American default under bridge-formula constraints |
| Tri-Axle (3-Axle) | European and Australian load limits favour three-axle load distribution |
| 4+ Axles | Heavy-haul and oversize permit work drives specialized multi-axle demand |
Axle count is a regulatory outcome more than an engineering preference. Fleets operating across jurisdictions frequently maintain mixed configurations rather than standardize, accepting higher parts complexity in exchange for route flexibility.
By Tonnage Capacity
| Sub-Segment | Key Trend |
| Below 25 Tonnes | Regional and last-leg distribution favours lighter, more manoeuvrable units |
| 25–50 Tonnes | The mainstream long-haul band; highest unit volumes globally |
| 50–100 Tonnes | Mining, energy and industrial haulage sustain premium pricing |
| Above 100 Tonnes | Wind components and modular construction cargo expand heavy-haul demand |
Capacity banding tracks end-use concentration closely. The 25–50 tonne band dominates because it aligns with the majority of national gross-combination-weight ceilings, while the heaviest band grows fastest from a small base on renewable-energy component logistics.
By End-Use Industry
| Sub-Segment | Key Trend |
| Logistics & Transportation | Drop-and-hook models raise trailer-to-tractor ratios |
| Construction | Infrastructure disbursement cycles drive platform and tipper orders |
| Food & Beverage | Cold-chain compliance documentation becomes a purchase specification |
| Chemicals & Petroleum | Tank certification and inspection regimes lengthen replacement cycles |
| Agriculture | Harvest seasonality creates concentrated, lumpy ordering patterns |
| Automotive & Industrial | Inbound component logistics favour curtain-sided and specialized carriers |
Buying behaviour differs sharply across these groups. Contract logistics providers optimize for residual value and interchange standardization; vocational buyers in construction and agriculture optimize for duty-cycle durability and accept weaker resale as the cost of fitness for purpose.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA