Self-adhesive Labels Market (2026 - 2035)

ID: MRFR/PCM/0825-HCR 111 Pages Snehal Singh Last Updated: September 18, 2026
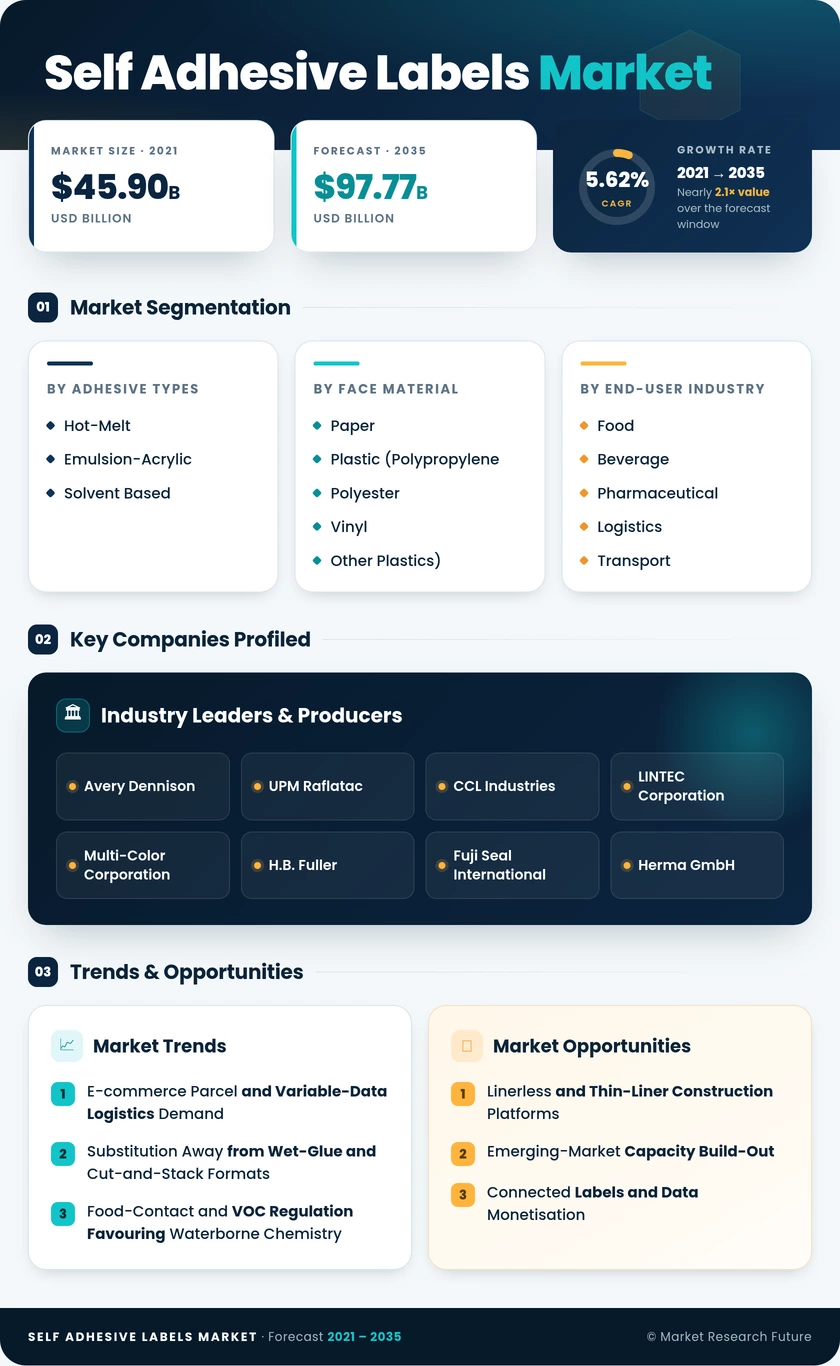
Self-adhesive Labels Market Research Report Information By Adhesive Types (Hot-Melt, Emulsion-Acrylic, and Solvent Based), By Face Material (Paper, Plastic, Polypropylene, Polyester, Vinyl, and Other Plastics), and By End-user Industry (Food and Beverage, Pharmaceutical, Logistics and Transport, Personal Care, Consumer Durables, and Other End-user Industries) – Forecast Till 2035
Self-adhesive Labels Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.62%
2025 Market SizeUSD 56.84 Billion
2035 Market SizeUSD 97.77 Billion
Key Players
Avery Dennison
UPM Raflatac
CCL Industries
LINTEC Corporation
Multi-Color Corporation
H.B. Fuller
Opportunities
  • Linerless and Thin-Liner Construction Platforms
  • Emerging-Market Capacity Build-Out
  • Connected Labels and Data Monetisation
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Adhesive Types | |
    2. 2.2 By Face Material | |
    3. 2.3 By End-user Industry | |
    4. 2.4 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2024) | |
    2. 3.2 Base Year Assessment (2025) | |
    3. 3.3 Forecast Market Size (2026–2035) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 E-commerce Parcel and Variable-Data Logistics Demand | |
    2. 4.2 Substitution Away from Wet-Glue and Cut-and-Stack Formats | |
    3. 4.3 Food-Contact and VOC Regulation Favouring Waterborne Chemistry | |
    4. 4.4 Pharmaceutical Serialization and Track-and-Trace Mandates | |
    5. 4.5 Digital Press Economics and SKU Proliferation | |
    6. 4.6 Cold-Chain and Durable Packaging Film Adoption | |
    7. 4.7 Closed-Loop Liner Recycling and Mono-Material Design | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Liner and Matrix Waste Disposal Cost | |
    2. 5.2 Paper and Specialty Film Price Volatility | |
    3. 5.3 Competition from Linerless and Direct-to-Package Printing | |
    4. 5.4 PVC Phase-Down and Solvent-Chemistry Restriction | |
    5. 5.5 Capital Intensity and Skilled-Operator Shortage | |
  6. 6 Opportunities | |
    1. 6.1 Linerless and Thin-Liner Construction Platforms | |
    2. 6.2 Emerging-Market Capacity Build-Out | |
    3. 6.3 Connected Labels and Data Monetisation | |
    4. 6.4 Closed-Loop Liner Recycling as a Contract Differentiator | |
    5. 6.5 Pharmaceutical and Cold-Chain Specification Capture | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 Asia-Pacific | | |
      1. 7.1.1 China | | |
      2. 7.1.2 India | | |
      3. 7.1.3 Japan | | |
      4. 7.1.4 South Korea | | |
      5. 7.1.5 Rest of Asia-Pacific | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 United Kingdom | | |
      3. 7.2.3 Italy | | |
      4. 7.2.4 France | | |
      5. 7.2.5 Rest of Europe | |
    3. 7.3 North America | | |
      1. 7.3.1 United States | | |
      2. 7.3.2 Canada | | |
      3. 7.3.3 Mexico | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East and Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 South Africa | | |
      3. 7.5.3 Rest of Middle East and Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Machine Vision and Autonomous Quality Assurance | |
    2. 8.2 Material Circularity as a Procurement Gate | |
    3. 8.3 Digital Capacity Reaching Structural Majority | |
    4. 8.4 The Label as a Data Endpoint | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Adhesive Types | | |
      1. 9.1.1 Hot-Melt | | |
      2. 9.1.2 Emulsion-Acrylic | | |
      3. 9.1.3 Solvent-Based | |
    2. 9.2 By Face Material | | |
      1. 9.2.1 Paper | | |
      2. 9.2.2 Plastic | |
    3. 9.3 By End-user Industry | | |
      1. 9.3.1 Food and Beverage | | |
      2. 9.3.2 Pharmaceutical | | |
      3. 9.3.3 Logistics and Transport | | |
      4. 9.3.4 Personal Care | | |
      5. 9.3.5 Consumer Durables | | |
      6. 9.3.6 Other End-user Industries | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 | |
  19. TABLE 5 Global Market Size, by Region, 2021–2035 (USD Billion) | |
  20. TABLE 6 Asia-Pacific Market Size, by Country, 2021–2035 (USD Billion) | |
  21. TABLE 7 Europe Market Size, by Country, 2021–2035 (USD Billion) | |
  22. TABLE 8 North America Market Size, by Country, 2021–2035 (USD Billion) | |
  23. TABLE 9 South America Market Size, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 Middle East and Africa Market Size, by Country, 2021–2035 (USD Billion) | |
  25. TABLE 11 Global Market Size, by Adhesive Types, 2021–2035 (USD Billion) | |
  26. TABLE 12 Global Market Size, by Face Material, 2021–2035 (USD Billion) | |
  27. TABLE 13 Global Market Size, by End-user Industry, 2021–2035 (USD Billion) | |
  28. TABLE 14 Competitive Benchmarking Matrix, 2026 | |
  29. TABLE 15 Company Profiles – Key Players | |
  30. TABLE 16 Recent Developments & Strategic Announcements, 2023–2025 | |
  31. TABLE 17 Report Scope & Methodology Summary | |
  32. TABLE 18 Detailed Sources and Citations Index | |
  33. TABLE 19 Segmentation Quick Reference Matrix | |
  34. TABLE 20 Sub-Segment Trend Matrix, by Adhesive Types | |
  35. TABLE 21 Sub-Segment Trend Matrix, by Face Material | |
  36. TABLE 22 Sub-Segment Trend Matrix, by End-user Industry | | LIST OF FIGURES | |
  37. FIGURE 1 Market Dynamics – Drivers, Restraints and Opportunities Map | |
  38. FIGURE 2 Industry Value Chain Analysis | |
  39. FIGURE 3 Porter's Five Forces Analysis | |
  40. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) | |
  41. FIGURE 5 Year-over-Year Growth Trajectory, 2022–2035 | |
  42. FIGURE 6 Market Share by Adhesive Types, 2025 vs 2035 | |
  43. FIGURE 7 Market Share by Face Material, 2025 vs 2035 | |
  44. FIGURE 8 Market Share by End-user Industry, 2025 | |
  45. FIGURE 9 Regional Revenue Share Distribution, 2025 | |
  46. FIGURE 10 Regional CAGR Comparison, 2026–2035 | |
  47. FIGURE 11 Asia-Pacific Country-Level Share Distribution, 2025 | |
  48. FIGURE 12 Europe Country-Level Share Distribution, 2025 | |
  49. FIGURE 13 Competitive Landscape Positioning Matrix, 2026 | |
  50. FIGURE 14 Top-Five Supplier Revenue Concentration, 2025

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Adhesive TypesHot-Melt; Emulsion-Acrylic; Solvent BasedEmulsion-Acrylic (41.05% share, 2025)Hot-Melt (6.57% CAGR, 2026–2035)
By Face MaterialPaper; Plastic (Polypropylene, Polyester, Vinyl, Other Plastics)Paper (59.24% share, 2025)Plastic (5.94% CAGR, 2026–2035)
By End-user IndustryFood and Beverage; Pharmaceutical; Logistics and Transport; Personal Care; Consumer Durables; Other End-user IndustriesFood and Beverage (22.65% share, 2025)Logistics and Transport (6.17% CAGR, 2026–2035)


Market Segmentation Overview

By Adhesive Types

Sub-SegmentKey Trend
Hot-MeltSIS polymer upgrades deliver microwave-grade heat resistance; instant cure supports high-speed automated lines
Emulsion-AcrylicWaterborne chemistry clears food-contact migration limits without reformulation
Solvent BasedMigration caps and VOC ceilings narrow application scope toward durable outdoor use


Emulsion-Acrylic holds the leading position because compliance, not adhesion performance, decides most food and beverage specifications, and waterborne formulations pass migration testing without the abatement investment solvent lines require. Hot-Melt grows fastest as converters standardise on presses that cure instantly and cut drying energy roughly a quarter, making it the default choice for logistics and consumer-durables work. Solvent-based holds ground only where chemical and outdoor resistance justify the regulatory overhead.

By Face Material

Sub-SegmentKey Trend
PaperFibre-recycling compatibility keeps paper specified for cartons and dry-goods packaging
PlasticCondensation, oil, and autoclave resistance drive substitution in cold-chain and pharmaceutical duty
PolypropyleneMono-material design rules pair PP facestock with PP containers
PolyesterSterilisation-stable substrate for serialised pharmaceutical codes
VinylOutdoor durability niche tempered by brand-level PVC phase-out commitments
Other PlasticsSpecialty barrier and synthetic-paper constructions for industrial marking


Paper leads on cost and on recyclability alignment with fibre-based cartons, which matters more under European recyclability grading than raw performance does. Plastic grows faster because the applications expanding quickest — frozen distribution, autoclaved pharmaceuticals, chemically exposed industrial containers — are exactly the conditions that degrade cellulose face stocks. Within plastic, Polypropylene gains from mono-material procurement rules while Vinyl advances slowly against sustainability commitments.

By End-user Industry

Sub-SegmentKey Trend
Food and BeverageSKU proliferation and nutrition-disclosure rules raise label variants per product line
PharmaceuticalUnit-level serialization mandates require sterilisation-stable, high-contrast codes
Logistics and TransportParcel growth and IATA hazard rules consolidate barcode, TTI, and customs data in one pass
Personal CareHolograms and NFC inlays counter counterfeiting; Delta-E under 2.0 colour tolerances apply
Consumer DurablesCompliance marking and warranty identification on long-life goods
Other End-user IndustriesIndustrial chemicals, agriculture, and retail shelf-edge applications


Food and Beverage leads on volume because its SKU count and disclosure obligations scale faster than unit output does. Logistics and Transport is the fastest riser: parcel throughput compounds while durable polyester facestocks absorb hazard, tracking, and customs data that previously required multiple labels. Pharmaceutical earns disproportionate value per unit under track-and-trace enforcement, and Personal Care sustains premium pricing through anti-counterfeit features and tight colour-stability specifications.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.