Scaffolding Market (2026 - 2035)

Scaffolding Market Research Report Information By Product (Hydrogels, Polymeric Scaffolds, Micropatterned Surface Microplates, and Nanofiber-Based Scaffolds), By Disease Type (Orthopedics, Musculoskeletal, Cancer, Skin and Integumentary, Dental, Cardiology and Vascular, Neurology, and Other Disease Types), By Application (Stem Cell Therapy, Regenerative Medicine and Tissue Engineering, Drug Discovery, and Other Applications), and By End User (Biotechnology and Pharmaceutical Organizations, Research Laboratories and Institutes, Hospitals and Diagnostic Centers, and Other End Users) – Forecast Till 2035.
ID: MRFR/PCM/3470-CR 206 Pages Chitranshi Jaiswal Last Updated: September 15, 2026
Scaffolding Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)12.5%
2025 Market SizeUSD 2.01 Billion
2035 Market SizeUSD 6.49 Billion
Key Players
Thermo Fisher Scientific
Merck KGaA
Corning Incorporated
Lonza Group
Integra LifeSciences
Zimmer Biomet
Opportunities
  • Emerging-Market Clinical Infrastructure
  • Scaffold Performance Data as a Commercial Asset
  • Organ-on-Chip Integration for Discovery

Scaffolding Market Summary

The Scaffolding Market reached USD 2.01 billion in 2025 and opens the forecast window at USD 2.25 billion in 2026, climbing to USD 6.49 billion by 2035 at a 12.5% CAGR. Two catalysts anchor that trajectory. The FDA's Regenerative Medicine Advanced Therapy designation pipeline crossed 100 active grants by late 2024, shortening review timelines for scaffold-enabled products [1], while the NIH obligated more than USD 480 million to tissue engineering and biomaterials research in FY2024 [2].

Underneath these figures, laboratory practice is evolving. Three-dimensional constructs that replicate extracellular matrix mechanics are replacing two-dimensional monolayer culture, which is biologically thin, reproducible, and inexpensive. Preclinical procedures that were previously exclusively conducted on flat plastic now incorporate hydrogel platforms, electrospun fiber meshes, and micropatterned culture surfaces. Horizon Europe allocated approximately EUR 1.1 billion to Cluster 1 health initiatives that addressed advanced therapies from 2023 to 2024, with a significant portion of this funding pertaining to biomaterial platforms [7].

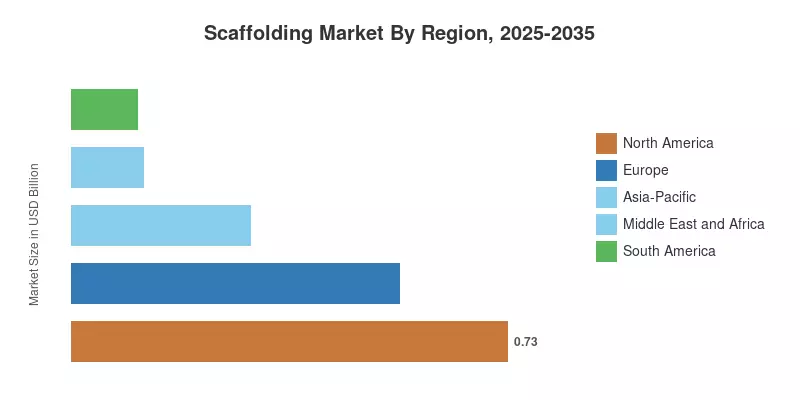
Supported by concentrated venture funding and dense clinical trial infrastructure, North America accounts for 36.3% of the Scaffolding Market. China, India, and South Korea are localizing biomaterial manufacturing, resulting in the fastest growth rate of 15.0% CAGR in the Asia-Pacific region. The harmonized ATMP regulations in Europe provide developers with a solitary regulatory reference point, resulting in a second-place ranking of USD 0.55 billion in 2025. The ability of manufacturing to scale to clinical volumes is more important than discovery in determining momentum through 2035.


Key Report Takeaways

• By Product

  • Hydrogels held 33.3% revenue share in 2025, reflecting tunable stiffness and established biocompatibility profiles.
  • Nanofiber-based scaffolds post the fastest product growth at 16.3% CAGR through 2035

• By Disease Type

  • Orthopedics accounted for 25.1% of Scaffolding Market demand in 2025, backed by decades of bone-void filler protocols.
  • Neurology expands at 14.6% CAGR, driven by conductive nerve conduits and guided axonal regeneration.

• By Application

  • Regenerative medicine and tissue engineering captured 38.4% share in 2025
  • Stem cell therapy grows quickest at 15.6% CAGR as xeno-free media improve derivation yields

• By End User

  • Biotechnology and pharmaceutical organizations commanded 49.2% of demand in 2025
  • Hospitals and diagnostic centers record a 15.3% CAGR, evidence of bench-to-bedside translation

• By Region

  • North America led the Scaffolding Market with a 36.3% share in 2025
  • Asia-Pacific grows fastest at 15.0% CAGR to 2035
  • Europe generated USD 0.55 billion in 2025

Market Size and Forecast (2021–2035)

Estimates combine bottom-up revenue modelling of biomaterial suppliers, culture-consumable vendors, and contract manufacturers with top-down validation against reported segment revenues in public filings [12][13][14]. Historical values reflect audited disclosures where available; forecast values apply demand elasticity to clinical trial starts, published regulatory approvals, and regional manufacturing capacity additions.
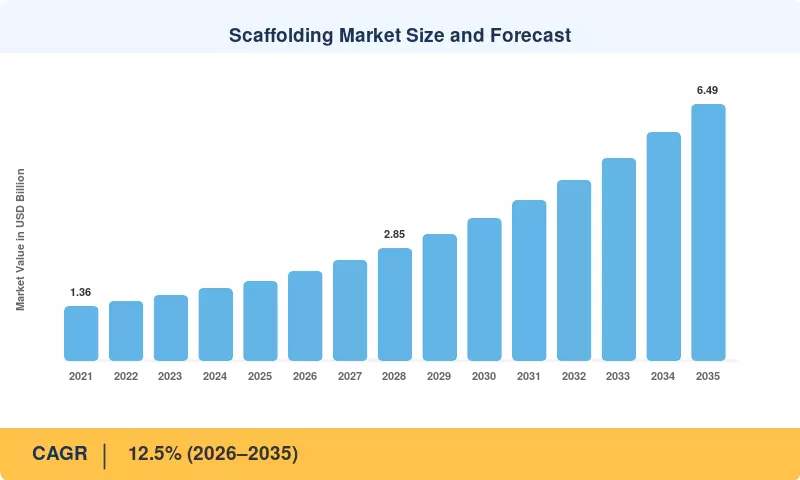
Scaffolding Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Regulatory approvals for scaffold-enabled therapies ~1.9 North America, Europe Short-term (≤2 yr)
Migration from 2D to 3D culture in discovery workflows ~1.7 Global Short-term (≤2 yr)
Public research funding for regenerative medicine ~1.5 North America, Europe, Asia-Pacific Medium-term (2–4 yr)
Ageing populations and musculoskeletal disease burden ~1.3 Europe, Asia-Pacific Long-term (≥4 yr)
Bioprinting and melt electrowriting process maturity ~1.2 Global Medium-term (2–4 yr)
Hospital-based cell therapy infrastructure build-out ~0.9 North America Medium-term (2–4 yr)
Asia-Pacific biomaterial manufacturing localisation ~0.8 Asia-Pacific Long-term (≥4 yr)


Regulatory Approvals for Scaffold-Enabled Therapies

Approval precedent removes the single largest commercial uncertainty for developers. The FDA had granted over 100 RMAT designations by the close of 2024, and roughly one in five involved a structural biomaterial component [1]. Europe's ATMP register recorded 25 centrally authorised products by 2024, several using resorbable matrices as delivery vehicles [3]. Each authorisation validates a manufacturing pathway that follow-on developers can reference, compressing timelines and cutting first-in-human costs materially.

Migration from 2D to 3D Culture in Discovery Workflows

Pharmaceutical discovery groups are replacing flat culture with matrix-supported models because predictive failure rates in late-phase trials remain punishing. Published comparisons show 3D hepatocyte and tumour models improving toxicity prediction concordance by 25–40% against animal data [4]. That translates into recurring consumable demand rather than one-off capital purchases, which is why hydrogel and microplate volumes track discovery headcount closely across the Scaffolding Market.

Public Research Funding for Regenerative Medicine

Government money still underwrites the earliest stages of this field. NIH obligations to tissue engineering and biomaterials programmes exceeded USD 480 million in FY2024 [2], while Horizon Europe's Cluster 1 health calls committed roughly EUR 1.1 billion across 2023–2024 with substantial advanced-therapy weighting [7]. Grant-funded academic laboratories buy scaffolds continuously and, more importantly, generate the published protocols that commercial buyers later adopt at scale.

Ageing Populations and Musculoskeletal Disease Burden

Demographics create durable volume. OECD data place the share of population aged 65 and over above 21% in Japan, Italy, and Germany [5], and WHO estimates roughly 1.7 billion people worldwide live with musculoskeletal conditions [6]. Bone-void fillers, cartilage repair matrices, and osteochondral constructs address that burden directly. Demand here is less sensitive to research funding cycles than discovery-driven segments, giving the forecast a stable floor.

Bioprinting and Melt Electrowriting Process Maturity

Fabrication control has improved faster than most buyers expected. Melt electrowriting now achieves sub-micron fibre placement, letting manufacturers specify porosity and stiffness gradients within a single construct [4]. Hybrid workflows that print hydrogel bulk around electrospun reinforcement have moved from single-laboratory demonstrations into commercial catalogue products, widening the addressable set of indications well beyond simple bone-void filling.

Hospital-Based Cell Therapy Infrastructure Build-Out

Clinical sites are becoming buyers, not just referrers. CMS outpatient payment updates for 2025 expanded coverage pathways for several cell-based procedures, improving hospital economics for on-site preparation [19]. Roughly 20 specialised US centres now run GMP-compliant suites capable of scaffold seeding, and robotic handling clusters cut labour cost per batch. Procurement shifts accordingly from research-grade catalogues to validated clinical-grade supply agreements.

Asia-Pacific Biomaterial Manufacturing Localisation

Regional supply chains are being rebuilt deliberately. China's NMPA issued updated cell and gene therapy manufacturing guidance in 2024 that clarified biomaterial characterisation requirements [9], and India's National Biopharma Mission disbursed over USD 250 million across translational infrastructure [20]. Local production narrows the price gap against imported Western products, expanding accessible volume in markets where cost has historically capped adoption.

Restraints Impact Analysis

Restraint impacts are directional drag estimates applied to unconstrained demand, not deductions from the reported CAGR. Where a restraint eases — reimbursement clarity, for instance — the associated drag reverses rather than disappearing.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
GMP-grade biomaterial cost structure ~-1.4 Global Short-term (≤2 yr)
Regulatory heterogeneity across jurisdictions ~-1.2 Asia-Pacific, Middle East and Africa Medium-term (2–4 yr)
Batch reproducibility and scale-up limits ~-1.0 Global Medium-term (2–4 yr)
Reimbursement uncertainty for scaffold-based procedures ~-0.8 North America, Europe Long-term (≥4 yr)
Shortage of trained bioprocess personnel ~-0.6 Europe, Asia-Pacific Long-term (≥4 yr)


GMP-Grade Biomaterial Cost Structure

Clinical-grade inputs cost several multiples of research-grade equivalents. Recombinant collagen and pharmaceutical-grade alginate carry documentation, traceability, and endotoxin testing burdens that suppliers price accordingly; Lonza's 2024 disclosures point to sustained gross margin pressure in specialised biomaterials [17]. For early-stage developers, matrix cost can consume a meaningful share of preclinical budgets, delaying the transition from bench validation to first-in-human work.

Regulatory Heterogeneity Across Jurisdictions

Classification remains inconsistent. Japan's conditional approval framework treats certain scaffold-cell combinations as regenerative medicine products [8], while Brazil's ANVISA routes comparable constructs through advanced therapy rules with different evidentiary demands [21]. Developers therefore run parallel dossiers, duplicating stability and biocompatibility testing. That duplication delays multi-country launches by 12–24 months and pushes smaller firms toward single-market strategies.

Batch Reproducibility and Scale-Up Limits

Processes that behave well at bench scale often fail at volume. Electrospinning and bioprinting both show fibre-diameter and porosity drift when run continuously, and ISO 10993 biological evaluation requirements apply to every validated change [23]. Manufacturers consequently over-specify tolerances, raising scrap rates. Until in-line process analytics mature, unit economics improve more slowly than the underlying science would suggest.

Reimbursement Uncertainty for Scaffold-Based Procedures

Payers move slower than regulators. Several scaffold-enabled procedures still lack dedicated codes, leaving hospitals to absorb material cost inside bundled payments [19]. Where a construct adds several thousand dollars per case without a corresponding payment adjustment, procurement committees defer adoption regardless of clinical evidence. This restraint bites hardest in the outpatient setting, where margin tolerance is thinnest.

Shortage of Trained Bioprocess Personnel

Talent constrains capacity expansion. Sector surveys report persistent vacancy rates in cell therapy manufacturing roles across Europe and Asia-Pacific, with qualified process engineers among the hardest positions to fill [11]. Every new suite requires trained operators before it can release product, so facility announcements translate into revenue with a lag. Training programmes are expanding, but qualification cycles run 12–18 months.

Scaffolding Market Opportunities

Emerging-Market Clinical Infrastructure

India, Brazil, and Saudi Arabia are building translational capacity faster than incumbent suppliers have built local channels. The National Biopharma Mission committed more than USD 250 million to translational infrastructure [20], and Saudi Arabia's Health Sector Transformation Program funds specialised regenerative centres under Vision 2030 [22]. Suppliers that register products locally and price for regional cost structures can capture volume before Western competitors establish distribution.

Scaffold Performance Data as a Commercial Asset

Every seeded construct generates characterisation data — porosity, degradation kinetics, cell viability curves — that most vendors discard. Subscription models that bundle matrices with validated protocol libraries and outcome benchmarking convert a consumable sale into recurring revenue. Early movers pairing catalogue product with cloud-hosted assay datasets report materially higher customer retention, a pattern already visible among life science tools vendors [12].

Organ-on-Chip Integration for Discovery

Pharmaceutical toxicology groups are adopting microphysiological systems requiring tissue-specific stiffness matrices. The FDA Modernization Act 2.0 authorized non-animal alternatives for drug applications, backed by market reports valuing the global organ-on-a-chip industry at USD 234.8 million in 2026. Co-developing chip-compatible formats allows suppliers to capture high-margin positions as the market scales toward USD 1.21 billion by 2033.


Xeno-Free and Animal-Free Supply Chains

Buyers require animal-free components due to regulatory and ESG mandates, noting that over 90% of drugs safe in animal trials fail human efficacy or safety testing. With government initiatives encouraging human-relevant New Approach Methodologies (NAMs), early conversion to recombinant alternatives lets firms avoid costly revalidations while meeting hospital procurement sustainability screens and strict regulatory standards.


Point-of-Care Manufacturing Partnerships

Centralised production adds cold-chain costs for short-shelf-life therapies. Closed-system hospital fabrication removes these hurdles, supported by contract manufacturing expansions. Global cell therapy processing data reports indicate market values expanding from USD 8.2 billion to USD 18.7 billion, enabling automated medical device segments to secure annuity revenue tied to clinical procedure volumes rather than volatile research budgets


Scaffolding Market Future Outlook

Computational Design and Automated Fabrication

Design cycles compress as machine learning predicts degradation and cell response before fabrication. Supported by global biotechnology market reports valuing the sector at USD 1.49 trillion in 2026, groups combining omics readouts with generative design report iteration reductions. Paired with unattended robotic fabrication cells, bottlenecks shift from discovery to validation, specifying products by mechanical profiles.


Consolidation Around Integrated Platform Suppliers

Buyers demand single contracts covering matrix, media, characterisation, and release testing. Large tools vendors assemble capabilities via acquisitions, tracking within broader segments of a global market projected to reach USD 4.18 trillion by 2034. Smaller specialists retain positions through differentiated chemistry, while commodity gel suppliers face margin compression as procurement consolidates around fewer qualified vendors.


Decentralised and Point-of-Care Production

Manufacturing moves closer to patients. Closed automated systems in hospital pharmacies eliminate cold-chain risks for short-viability constructs, backed by contract manufacturers packaging scaffold production into clinical services. Supported by life science analytics showing the global cell therapy market expanding to USD 19.31 billion, adoption relies on regulators accepting site-level equivalence rather than requiring full re-validation per location—a structural framework under active international agency consultation.


Sustainability and Animal-Free Sourcing

Environmental and ethical screening dictates procurement scoring at major hospital systems and pharmaceutical buyers. Replacing bovine and murine inputs with recombinant or plant alternatives resolves matrix variability issues documented across life science analyses, where the overarching biomaterials market is valued at approximately USD 330 billion. Vendors completing this transition before 2030 avoid substantial revalidation burdens that slower competitors will eventually be forced to absorb


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 36.3% share RMAT pipeline, hospital cell therapy suites, venture funding density
Europe USD 0.55 Billion ATMP harmonisation, Horizon Europe grants, orthopedic device base
Asia-Pacific 15.0% CAGR Manufacturing localisation, regulatory reform, government translational funds
Middle East and Africa USD 0.12 Billion Sovereign health transformation programmes, specialised centre build-out
South America 5.6% share ANVISA advanced therapy framework, academic-clinical partnerships
Total USD 2.01 Billion

Regional performance in the Scaffolding Market tracks three variables: density of active clinical trials, availability of GMP manufacturing capacity, and clarity of the local approval pathway. North America leads on all three today; Asia-Pacific is closing the gap on the second and third.


North America

Country Metric (2025) Key Driver
US 82.4% of region RMAT designations and NIH biomaterials funding [1][2]
Canada USD 0.09 Billion Provincial regenerative medicine networks and academic spinouts [11]
Mexico 13.1% CAGR Contract research expansion and cross-border manufacturing


North America anchors the Scaffolding Market because approval precedent, capital, and clinical volume sit in the same jurisdiction. The FDA's expedited pathways materially shorten development for combination products [1], and CMS outpatient rule updates for 2025 improved hospital economics for several cell-based procedures [19]. Canada contributes disproportionate academic output relative to its market size, while Mexico's role is shifting from distribution toward contract manufacturing for US sponsors seeking cost relief without long transit times.

Europe

Country Metric (2025) Key Driver
Germany 23.6% of region Orthopedic device manufacturing base and Fraunhofer translational institutes [7]
UK USD 0.09 Billion MHRA Innovative Licensing and Access Pathway adoption [10]
France 12.6% CAGR Public hospital advanced therapy programmes [3]
Italy 9.8% of region High ageing-population disease burden [5]
Spain USD 0.04 Billion Regional biobank and clinical trial network expansion [7]
Nordic Countries 13.4% CAGR Registry-based outcome evidence and public research funding [11]
Russia 4.1% of region Domestic substitution in surgical biomaterials
Rest of Europe USD 0.06 Billion Cross-border ATMP filings under centralised procedure [3]


Europe's advantage is procedural rather than financial. A single centralised ATMP authorisation covers 27 markets, which lowers the cost of multi-country launch relative to fragmented regions [3]. Germany's established orthopedic manufacturing cluster gives scaffold suppliers a ready commercial channel, and the UK's ILAP has compressed early regulatory engagement for several advanced therapies [10]. Ageing demographics across Italy and the Nordic markets sustain orthopedic and cartilage repair volumes independently of research funding cycles [5].

Asia-Pacific

Country Metric (2025) Key Driver
China 31.2% of region NMPA cell and gene therapy guidance and domestic capacity [9]
India 16.8% CAGR National Biopharma Mission translational funding [20]
Japan USD 0.11 Billion Conditional approval framework for regenerative products [8]
South Korea 12.4% of region Government-backed bio-cluster investment [11]
ASEAN 15.4% CAGR Medical tourism and private hospital capability upgrades
Rest of Asia-Pacific USD 0.03 Billion Academic collaboration and import-led adoption


Asia-Pacific grows fastest because policy, capital, and manufacturing are moving together. Japan's conditional approval route allows earlier commercialisation of regenerative products with post-market evidence obligations, a structure several scaffold-based therapies have used [8]. China's updated NMPA guidance clarified characterisation requirements that previously stalled filings [9]. India's cost base makes it a plausible export platform once quality systems mature, and ASEAN private hospitals are upgrading capability faster than public systems.

Middle East and Africa

Country Metric (2025) Key Driver
Saudi Arabia 28.7% of region Health Sector Transformation Program specialised centres [22]
UAE 14.6% CAGR Medical free-zone regulatory flexibility and clinical partnerships [22]
South Africa USD 0.02 Billion Academic hospital research programmes
Egypt 11.3% of region Public tertiary hospital procurement expansion
Rest of MEA 12.2% CAGR Import-led adoption via regional distributors


Middle East and Africa remains small in absolute terms but is unusually concentrated in sovereign-funded projects. Saudi Arabia's Vision 2030 health programme directs capital toward specialised centres that buy advanced biomaterials as part of turnkey builds [22]. UAE free zones offer regulatory flexibility that international sponsors use for early clinical work. South Africa and Egypt follow a different pattern, with demand originating in academic hospitals rather than national programmes, which caps order size but stabilises repeat purchasing.

South America

Country Metric (2025) Key Driver
Brazil 54.6% of region ANVISA advanced therapy product framework [21]
Argentina USD 0.02 Billion University-led tissue engineering programmes
Rest of South America 12.9% CAGR Regional distributor networks and private clinic demand


South America's trajectory hinges on Brazil. ANVISA's advanced therapy rules created a defined registration route, and several domestic groups have used it to move academic constructs toward clinical evaluation [21]. Argentina contributes strong academic research but limited commercial scale, constrained by currency volatility that complicates imported input pricing. Across the remainder of the continent, private clinics rather than public systems drive early adoption, typically through regional distributors carrying multiple international lines.

Scaffolding Market By Region, 2025-2035

Scaffolding Market Segmentation

Segmentation in the Scaffolding Market follows four dimensions: product architecture, target disease area, application workflow, and purchasing organisation. Each behaves differently, and the fastest-growing sub-segment is rarely the largest one.

By Product

Segment Metric (2025) Primary Demand Driver
Hydrogels 33.3% share Tunable stiffness and established biocompatibility data
Polymeric Scaffolds USD 0.57 Billion Fabrication versatility and predictable degradation profiles
Micropatterned Surface Microplates USD 0.31 Billion High-throughput screening compatibility
Nanofiber-Based Scaffolds 16.3% CAGR Extracellular matrix mimicry and high surface area


Hydrogels lead product revenue in the Scaffolding Market because their mechanical properties can be tuned across several orders of magnitude without changing the underlying handling protocol. Polymeric scaffolds hold substantial volume in load-bearing repair, where degradation timing must match tissue remodelling. Nanofiber-based scaffolds grow fastest as electrospinning and melt electrowriting deliver architectures that support osteogenic differentiation, while micropatterned surface microplates serve screening workflows that prize reproducibility over biological complexity.

By Disease Type

Segment Metric (2025) Primary Demand Driver
Orthopedics 25.1% share Established bone-void filler clinical protocols
Musculoskeletal USD 0.29 Billion Soft-tissue and tendon repair procedure volume
Cancer 16.8% of dimension Tumour microenvironment modelling for therapeutic screening
Skin and Integumentary USD 0.21 Billion Burn and chronic wound reconstruction demand
Dental 8.1% of dimension Guided bone regeneration in implantology
Cardiology and Vascular USD 0.23 Billion Vascular graft and patch approvals
Neurology 14.6% CAGR Conductive nerve conduits and guided axonal regeneration
Other Disease Types 5.5% of dimension Ophthalmic and urologic reconstruction niches


Orthopedics remains the anchor indication across the Scaffolding Market, supported by reimbursement precedent and surgeon familiarity that newer areas lack. Cancer applications grow through research rather than therapy, using matrices to reconstruct tumour microenvironments for screening. Neurology expands quickest as custom-printed nerve conduits combining conductive polymers with controlled growth-factor release address peripheral injuries where autograft supply is limited. Skin, dental, and cardiovascular indications each contribute steady, procedure-linked volume.

By Application

Segment Metric (2025) Primary Demand Driver
Stem Cell Therapy 15.6% CAGR Xeno-free media improving derivation efficiency
Regenerative Medicine and Tissue Engineering 38.4% share Clinical translation of engineered constructs
Drug Discovery USD 0.49 Billion 3D model adoption in toxicology screening
Other Applications 9.1% of dimension Diagnostics, cosmetics testing, and veterinary use


Regenerative medicine and tissue engineering generate the largest application revenue in the Scaffolding Market, reflecting the maturity of constructs already in clinical use. Drug discovery contributes a stable consumable stream tied to pharmaceutical research headcount rather than approval milestones. Stem cell therapy grows fastest as electrospun meshes coated with biological polymers improve mesenchymal cell viability and paracrine output, advancing cartilage and cardiac repair programmes toward pivotal trials.

By End User

Segment Metric (2025) Primary Demand Driver
Biotechnology and Pharmaceutical Organizations 49.2% share Internal R&D spend and pilot-scale manufacturing
Research Laboratories and Institutes USD 0.52 Billion Grant-funded proof-of-concept programmes
Hospitals and Diagnostic Centers 15.3% CAGR On-site cell therapy suites and clinical translation
Other End Users 6.7% of dimension CDMOs, veterinary clinics, and cosmetics testing labs


Biotechnology and pharmaceutical organizations dominate purchasing in the Scaffolding Market because they buy across discovery, development, and pilot manufacturing simultaneously. Research laboratories and institutes buy smaller quantities but set the protocols commercial groups later adopt. Hospitals and diagnostic centers record the fastest growth as GMP suites move preparation on-site; robotic handling clusters reduce labour per batch while maintaining compliance, making hospital-based production economically defensible at moderate volume.

Competitive Benchmarking

Concentration in the Scaffolding Market is moderate. Estimated HHI sits in the 900–1,200 range, with the top five suppliers accounting for roughly 38–44% of global revenue. The structure splits cleanly: diversified life science tools companies command the discovery-consumable segment through scale and distribution, while smaller specialists hold defensible positions in clinical-grade matrices where chemistry and regulatory dossiers create switching costs. Acquisition activity has been steady but not transformative, as acquirers absorb niche chemistries rather than consolidating whole segments.

Company Est. Revenue Share Range Key Offerings for Scaffolding Market Strategic Positioning
Thermo Fisher Scientific ~10–13% 3D culture consumables, matrices, bioprocess media Scale distribution and integrated workflow bundling [12]
Merck KGaA ~8–11% Hydrogel matrices, recombinant proteins, culture surfaces Chemistry depth plus global regulatory documentation [13]
Corning Incorporated ~7–10% Micropatterned surface microplates, basement membrane matrix Entrenched installed base in screening laboratories [14]
Lonza Group ~5–8% GMP biomaterials, contract cell therapy manufacturing Integrated CDMO route from matrix to clinical batch [17]
Integra LifeSciences ~4–7% Collagen-based regeneration matrices for wound and dural repair Clinical channel strength in surgical specialties [15]
Zimmer Biomet ~3–6% Bone void fillers and osteoconductive scaffolds Orthopedic surgeon relationships and hospital contracts [18]
Vericel Corporation ~2–5% Autologous cell therapy with matrix delivery Narrow indication focus with reimbursement precedent [16]
Nanofiber Solutions ~1–4% Electrospun nanofiber constructs for wound and nerve repair Pure-play nanofiber specialist with clinical pipeline [11]
Advanced BioMatrix ~1–3% Research-grade collagen, hyaluronan, and bioprinting inks Catalogue breadth for academic and early-stage users
Matricel GmbH ~1–3% Collagen membranes and cartilage repair matrices Contract development for European device partners
Molecular Matrix ~1–2% Carbohydrate-based bone regeneration scaffolds Differentiated chemistry in orthopedic niche
3D Biotek ~1–2% Precision-fabricated polymeric culture inserts Format specialisation for 3D screening workflows


Recent News & Developments

  • US Food and Drug Administration (March 2023): Issued updated guidance clarifying combination product classification for cell-matrix constructs, reducing pre-submission ambiguity for developers [1].
  • Merck KGaA (September 2023): Expanded its animal-origin-free culture matrix portfolio, targeting clinical-grade users facing revalidation pressure from ISO 10993 requirements [13][23].
  • Japan PMDA (January 2024): Reaffirmed conditional approval eligibility for regenerative products incorporating resorbable matrices, sustaining Japan's early-commercialisation advantage [8].
  • Lonza Group (May 2024): Announced integration of scaffold seeding into its cell therapy contract manufacturing offering, shortening supply chains for clinical-stage sponsors [17].
  • China NMPA (August 2024): Published revised cell and gene therapy manufacturing guidance specifying biomaterial characterisation requirements, unblocking several domestic filings [9].
  • UK MHRA (November 2024): Reported expanded use of the Innovative Licensing and Access Pathway by advanced therapy developers, cutting early regulatory engagement timelines [10].
  • Integra LifeSciences (February 2025): Disclosed capacity expansion for collagen-based regeneration matrices, citing sustained surgical demand in wound and dural repair [15].
  • CMS (July 2025): Finalised outpatient payment updates improving hospital economics for selected cell-based procedures using matrix delivery systems [19].

Scaffolding Market Report Scope

Parameter Detail
Market Scope Global Scaffolding Market covering product, disease type, application, end user, and region.
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 12.5% (2026–2035)
Market Size Checkpoints USD 2.01 Billion (2025); USD 2.25 Billion (2026); USD 6.49 Billion (2035)
Fastest Growing Segments Nanofiber-Based Scaffolds (16.3% CAGR); Stem Cell Therapy (15.6% CAGR); Hospitals and Diagnostic Centers (15.3% CAGR); Asia-Pacific (15.0% CAGR)
Companies Profiled Thermo Fisher Scientific, Merck KGaA, Corning Incorporated, Lonza Group, Integra LifeSciences, Zimmer Biomet, Vericel Corporation, Nanofiber Solutions, Advanced BioMatrix, Matricel GmbH, Molecular Matrix, 3D Biotek
Valuation Currency USD Billion

FAQs

How should procurement teams qualify suppliers in the Scaffolding Market?
Request lot-level certificates of analysis, endotoxin data, and documented change-control history before pricing discussions. Suppliers unable to produce ISO 10993 evaluation files will trigger revalidation costs later [23].
What contract terms matter most when licensing scaffold intellectual property?
Secure field-of-use clarity and manufacturing step-in rights. Without step-in rights, a licensor's production failure can strand a clinical programme mid-trial [11].
How do hydrogel and nanofiber platforms compare on validation cost?
Hydrogels carry lower characterisation burden because rheological methods are well established. Nanofiber constructs require fibre-diameter and porosity validation at every scale change, raising qualification spend materially [4].
What integration challenges slow adoption across the Scaffolding Market?
Automated liquid handlers were designed for flat plates, so 3D formats often need custom labware and revalidated assay protocols. Budget six to nine months for workflow requalification [4].
Which reimbursement pathway applies to scaffold-based procedures?
Coverage typically follows the procedure code rather than the material. Where no dedicated code exists, hospitals absorb matrix cost inside bundled payment, which suppresses adoption [19].
How concentrated is supplier risk in the Scaffolding Market?
Several clinical-grade recombinant inputs come from a small number of qualified producers. Dual-sourcing is advisable but requires parallel regulatory documentation, so plan qualification well before commercial launch [17].
Which emerging use cases sit outside current clinical segments?
Cultivated meat scaffolding and cosmetics toxicity testing both draw on the same fabrication base. Neither carries clinical regulatory burden, making them attractive volume outlets for existing production lines [4].
Author
Author Author Profile Chitranshi Jaiswal LinkedIn Team Lead - Research
Chitranshi is a Team Leader in the Chemicals & Materials (CnM) and Energy & Power (EnP) domains, with 6+ years of experience in market research. She leads and mentors teams to deliver cross-domain projects that equip clients with actionable insights and growth strategies. She is skilled in market estimation, forecasting, competitive benchmarking, and both primary & secondary research, enabling her to turn complex data into decision-ready insights. An engineer and MBA professional, she combines technical expertise with strategic acumen to solve dynamic market challenges. Chitranshi has successfully managed projects that support market entry, investment planning, and competitive positioning, while building strong client relationships. Certified in Advanced Excel & Power BI she leverages data-driven approaches to ensure accuracy, clarity, and impactful outcomes.

Research Approach

Research Methodology on Scaffolding Market

Introduction
 

The global scaffolding market is growing with the rising applications of scaffolding in the construction and oil & gas domains. The need for safer and more efficient structures is driving market demand for scaffolding. According to a new report from Market Research Future (MRFR), the global scaffolding market is projected to register a healthy growth rate over the review period.

The chief factors driving the growth of this market are the escalating construction activities in residential, commercial and industrial sectors and the rapid technological advancements in scaffolding products. The construction industry is undergoing a rapid transformation characterized by the adoption of new scaffolding technologies to improve the quality of buildings, reduce the time taken for construction projects, and meet the demand for eco-friendly and sustainable infrastructure.

Research Objectives
 

The objective of this research is to study the current market scenario of the scaffolding industry, identify the key market trends, opportunities and challenges, analyze the key drivers and restraints of the industry, and make forecasts on the growth of the industry over the period from 2023 to 2030 and is focused on market size estimation and its forecast at a global level.

Research Methodology
 

The research for this market report is conducted primarily through primary and secondary research. Primary research includes interviews with scaffolding industry experts and leaders, while secondary research included data and information gathered from external and internal sources, such as trade journals, industry white papers and annual reports of the companies in the global scaffolding market.

  •  Primary Research

Primary research is conducted through telephone and online interviews with key industry players. A total of 10 interviews are conducted, which includes 5 interviews with industry experts and 5 interviews with industry leaders. The primary research focuses on understanding the current market situation, customer preferences and trends, industry strategies and dynamics, and factors influencing the market over the coming years.

  • Secondary Research

Secondary research includes trade journals and annual reports of the leading companies in the industry. Additionally, other sources such as industry associations, government websites and databases, third-party research and news articles are also studied. Various parameters used for the research are product type, application, region, country, and company size.

Data Collection and Analysis
 

  • Data Sources

The main data sources for the global scaffolding market include manufacturers, suppliers, distributors, and end-users. The major data sources used for primary and secondary research are:

  • Industry reports and publications
  • Government websites
  • Company websites and databases
  • Trade associations and industry councils
  • Key opinion leaders (KOL)
  • Market Size Estimation

The market size is estimated using the bottom-up approach. This approach involves the aggregation of data obtained from the demand side and the supply side. The demand side data is collected through interviews and participant observation. The supply-side data is collected using a combination of primary and secondary sources.

 Data Triangulation
 

Data triangulation is used to ensure the accuracy of the market share and size estimates by comparing the bottom-up and top-down approaches. The market share and size estimates are compared with the demand-side and supply-side data.

Market Breakdown & Data Validation
 

The market research methodology employed in the analysis focuses on quantitative and qualitative information about the scaffolding market. The main frameworks for market estimation are prepared and validated using Porter’s Five Forces model. The market share and size estimates are further validated using interviews with industry experts and leaders.

  •  Assumptions for Market Sizing
  • Global annual sales of scaffolding products and services are assumed to reach an all-time high valuation
  • Increasing demand for housing and infrastructure development in emerging economies is considered the major driving factor for scaffolding market growth.
  • The demand for scaffolding products in the Asia-Pacific region will remain the major driver of the overall market share over the forecast period.
  • Conclusion

The global scaffolding market is expected to register a healthy CAGR over the review period (2023–2030). This can be attributed to the rising construction activities in residential, commercial and industrial sectors and the rapid technological advancements in scaffolding products. Major players in the global scaffolding market are focusing on partnerships, mergers and acquisitions, and new product launches to strengthen their market presence.

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















