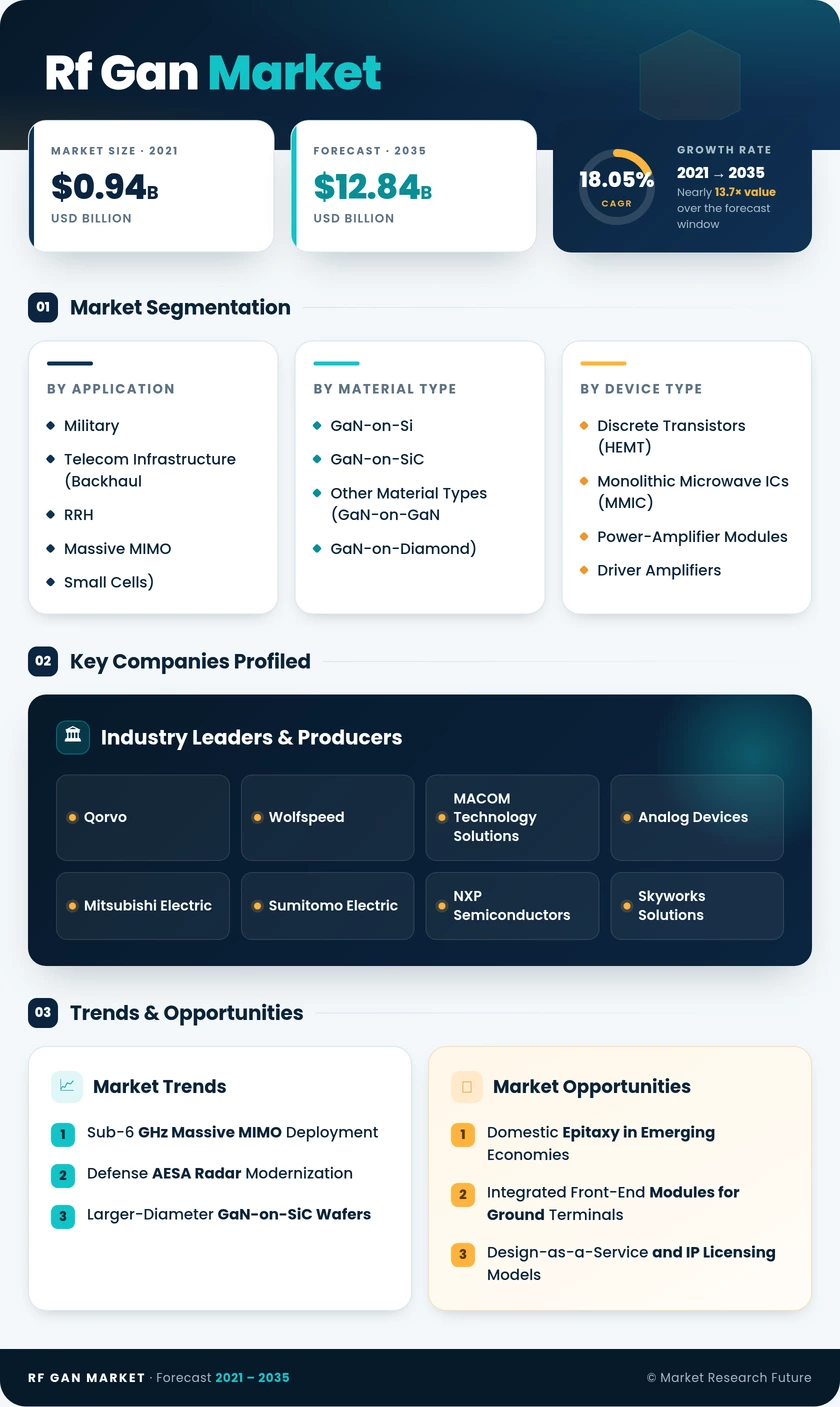
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Application | Military; Telecom Infrastructure (Backhaul, RRH, Massive MIMO, Small Cells); Satellite Communication; Wired Broadband; Commercial Radar and Avionics; RF Energy | Telecom Infrastructure (43.2% share, 2025) | Satellite Communication (18.85% CAGR) |
| By Material Type | GaN-on-Si; GaN-on-SiC; Other Material Types (GaN-on-GaN, GaN-on-Diamond) | GaN-on-SiC (68.1% share, 2025) | Other Material Types (22.4% CAGR) |
| By Device Type | Discrete Transistors (HEMT); Monolithic Microwave ICs (MMIC); Power-Amplifier Modules; Driver Amplifiers | Discrete Transistors (HEMT) (52.4% share, 2025) | Monolithic Microwave ICs (MMIC) (19.15% CAGR) |
| By Frequency Band | Below 3 GHz (L, S Bands); 3 – 6 GHz (C Band, 5G Sub-6); 6 – 18 GHz (X, Ku); Above 18 GHz (Ka, mmWave) | 3 – 6 GHz (C Band, 5G Sub-6) (45.6% share, 2025) | Above 18 GHz (Ka, mmWave) (19.12% CAGR) |
Market Segmentation Overview
By Application
| Sub-Segment | Key Trend |
| Military | AESA radar retrofits and electronic warfare arrays sustain premium-margin device orders |
| Telecom Infrastructure (Backhaul, RRH, Massive MIMO, Small Cells) | High per-radio device counts in 64T64R architectures drive volume consumption |
| Satellite Communication | Ka-band payloads treated as baseline specification across LEO constellations |
| Wired Broadband | DOCSIS 4.0 node upgrades deliver steady low-growth replacement demand |
| Commercial Radar and Avionics | Antenna footprint reduction of roughly 40% supports weather and traffic radar adoption |
| RF Energy | Solid-state heating modules approach efficiency thresholds for industrial deployment |
Telecom Infrastructure leads this dimension because massive MIMO radios and remote radio heads each carry dozens of transmit devices, and carrier energy-cost pressure rewards the efficiency gallium nitride delivers above 3 GHz. Satellite Communication expands fastest as low-earth-orbit operators standardize on Ka-band payloads, which keeps amplifier counts per spacecraft high and locks suppliers into multi-year programs. Military demand ranks second by value, protected by qualification barriers that discourage substitution, while RF Energy stays pre-commercial pending appliance-scale cost parity.
By Material Type
| Sub-Segment | Key Trend |
| GaN-on-Si | Cost-competitive below 3 GHz where breakdown voltage requirements are relaxed |
| GaN-on-SiC | Thermal conductivity near 490 W/m·K enables sustained junction temperatures above 200 °C |
| Other Material Types (GaN-on-GaN, GaN-on-Diamond) | Diamond substrates cut junction temperature 40–50 °C at premium wafer cost |
GaN-on-SiC holds the dominant position because its thermal headroom is the binding constraint on power density, and that advantage widens as designs move above 6 GHz. GaN-on-Si retains a defensible pocket in sub-3 GHz telecom, where 8-inch capacity scaling makes unit cost the deciding criterion rather than junction temperature. Other Material Types grow fastest from a narrow base, with diamond-backed devices reserved for thermally constrained defense arrays until wafer pricing falls materially below current levels.
By Device Type
| Sub-Segment | Key Trend |
| Discrete Transistors (HEMT) | Band-by-band matching network optimization maximizes efficiency per transmit path |
| Monolithic Microwave ICs (MMIC) | Single part replaces up to twelve discrete devices, improving phase coherence across array elements |
| Power-Amplifier Modules | Bundled die and control circuitry suit plug-and-play satellite ground terminals |
| Driver Amplifiers | High gain eliminates a stage in multi-stage chains, reducing radio bill of materials |
Discrete Transistors (HEMT) remain the revenue leader because engineers designing band-specific transmit chains extract more efficiency from tailored matching networks than from general-purpose integration. Monolithic Microwave ICs (MMIC) grow fastest as phased-array builders trade that efficiency margin for footprint and phase coherence, a trade that falling multi-project wafer costs have made economically accessible to smaller integrators. Power-Amplifier Modules gain in ground terminal segments valuing integration speed, while Driver Amplifiers stay smallest by revenue.
By Frequency Band
| Sub-Segment | Key Trend |
| Below 3 GHz (L, S Bands) | Incumbent silicon retains 30–40% price advantage per watt in legacy systems |
| 3 – 6 GHz (C Band, 5G Sub-6) | C-band repack and sub-6 GHz spectrum awards concentrate deployment volume |
| 6 – 18 GHz (X, Ku) | Defense radar and Ku-band ground terminals anchor mid-band consumption |
| Above 18 GHz (Ka, mmWave) | E-band backhaul and 28 GHz user terminals expand the high-frequency envelope |
The 3 – 6 GHz (C Band, 5G Sub-6) band dominates because regulators across major economies concentrated 5G spectrum awards there, producing a single synchronized equipment refresh across national carriers. Above 18 GHz (Ka, mmWave) grows fastest as E-band radios deliver multi-gigabit backhaul where trenching fiber costs six figures per kilometer, and as second-generation satellite terminals adopt 28 GHz front ends. Below 3 GHz (L, S Bands) advances slowly, since silicon's cost advantage persists where efficiency requirements stay modest.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA