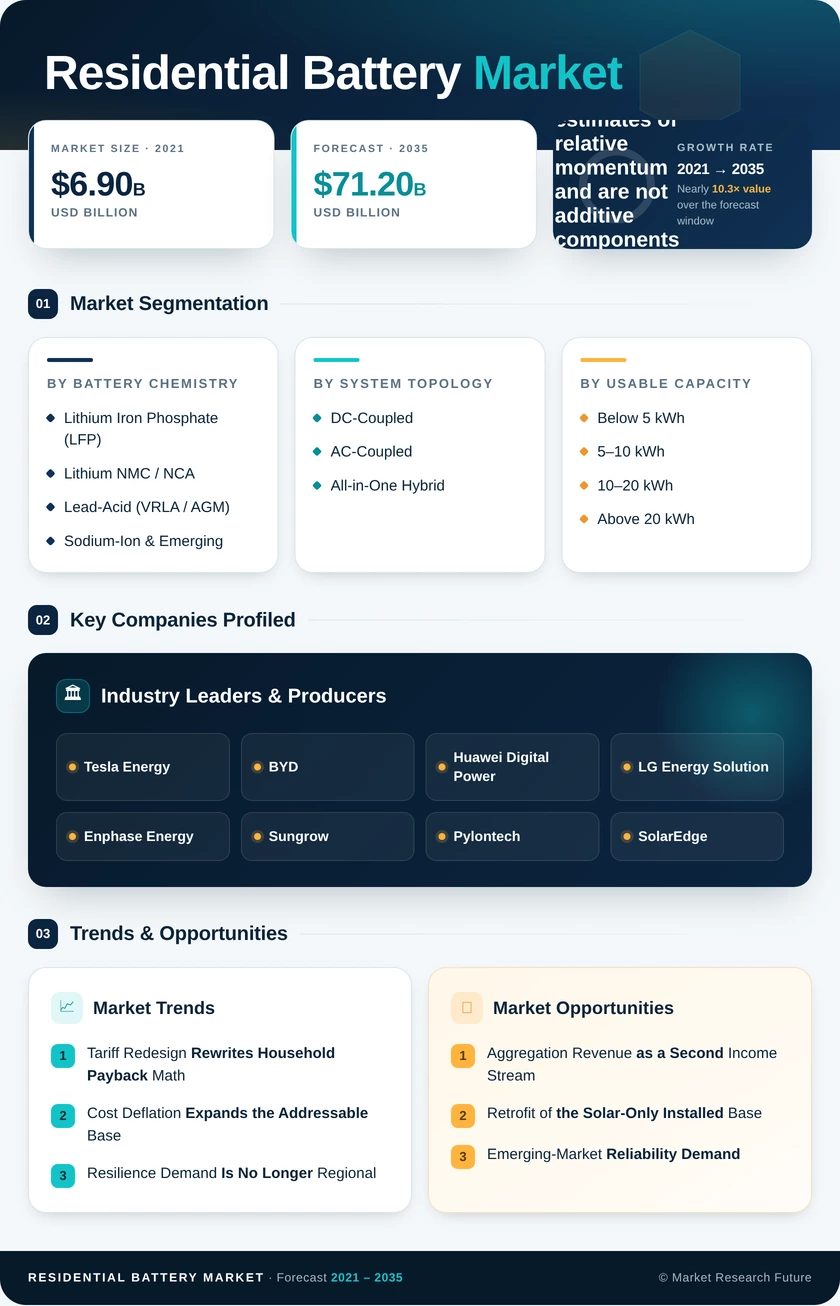
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Battery Chemistry | Lithium Iron Phosphate (LFP); Lithium NMC / NCA; Lead-Acid (VRLA / AGM); Sodium-Ion & Emerging | Lithium Iron Phosphate (LFP) | Sodium-Ion & Emerging |
| By System Topology | DC-Coupled; AC-Coupled; All-in-One Hybrid | DC-Coupled | All-in-One Hybrid |
| By Usable Capacity | Below 5 kWh; 5–10 kWh; 10–20 kWh; Above 20 kWh | 5–10 kWh | 10–20 kWh |
| By Application | Solar Self-Consumption; Backup Power / Resilience; Tariff Arbitrage; Grid Services / Aggregation | Solar Self-Consumption | Grid Services / Aggregation |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | Europe | Asia-Pacific |
Market Segmentation Overview
By Battery Chemistry
| Sub-Segment | Key Trend |
| Lithium Iron Phosphate (LFP) | Cobalt-free composition and unlimited-cycling warranties make it the default residential specification |
| Lithium NMC / NCA | Retained in space-constrained installations where volumetric energy density is decisive |
| Lead-Acid (VRLA / AGM) | Confined to legacy off-grid replacement; steadily displaced on total cost of ownership |
| Sodium-Ion & Emerging | Commercial entry expected 2029–2031 targeting cold-climate and price-sensitive demand |
Chemistry selection has consolidated around risk and warranty economics rather than peak performance. Manufacturers able to underwrite daily full-depth cycling for a decade now set the reference specification, and that capability is what has pushed nickel-based systems into a narrowing niche.
By System Topology
| Sub-Segment | Key Trend |
| DC-Coupled | Preferred on new-build solar for single-stage conversion efficiency |
| AC-Coupled | Primary route into the large existing solar-only installed base |
| All-in-One Hybrid | Integrated enclosures cut installation hours in labour-constrained markets |
Topology has become an installer-economics decision as much as an engineering one. Labour scarcity across North America, Australia and Northern Europe rewards products that reduce truck rolls and commissioning time, which is why integrated units are gaining share faster than their efficiency profile alone would justify.
By Usable Capacity
| Sub-Segment | Key Trend |
| Below 5 kWh | Entry-level backup and apartment applications; portable formats blurring the boundary |
| 5–10 kWh | Standard single-family self-consumption configuration across most European markets |
| 10–20 kWh | Fastest expansion as heat pumps and home EV charging raise household load |
| Above 20 kWh | Off-grid, rural and high-consumption households; multi-day autonomy requirements |
Median system size drifts upward each forecast year as the marginal cost of additional capacity falls faster than the fixed cost of installation. Households electrifying heating and transport simultaneously are the clearest driver of that shift.
By Application
| Sub-Segment | Key Trend |
| Solar Self-Consumption | Universal driver wherever retail price exceeds export compensation |
| Backup Power / Resilience | Emotionally decisive purchase motivation; loosens payback constraints |
| Tariff Arbitrage | Expands with time-of-use rate spreads and dynamic retail contracts |
| Grid Services / Aggregation | Contracted flexibility revenue emerging as a recurring income layer |
Applications overlap in practice — a single unit typically performs all four functions across a given week. Segment allocation reflects the dominant purchase motivation captured at point of sale, which is why resilience registers strongly in North America while self-consumption dominates European reporting.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA