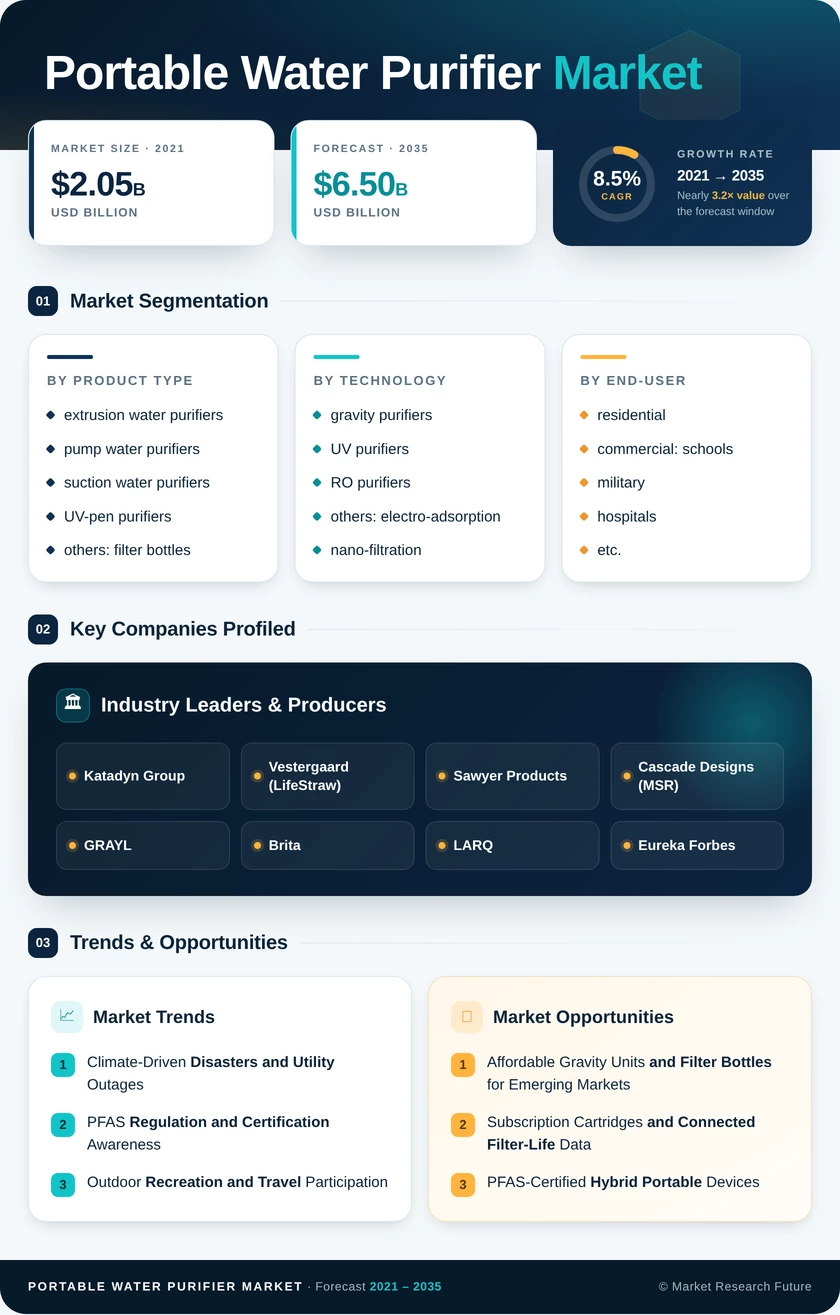
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|
| By Product Type | extrusion water purifiers; pump water purifiers; suction water purifiers; UV-pen purifiers; others: filter bottles, gravity bags, etc. | extrusion water purifiers (32.2% share) | UV-pen purifiers (10.5% CAGR) |
| By Technology | gravity purifiers; UV purifiers; RO purifiers; others: electro-adsorption, nano-filtration, etc. | gravity purifiers (36.0% share) | RO purifiers (9.9% CAGR) |
| By End-user | residential; commercial: schools, military, hospitals, etc. | Residential (53.0% share) | commercial (11.2% CAGR) |
| By Distribution Channel | B2C/retail (multi-brand stores, exclusive brand outlets, online, and other distribution channels); B2B/directly from the manufacturers | B2C/retail (71.5% share) | B2B/directly from the manufacturers (9.6% CAGR) |
| By Region | North America; South America; Asia-Pacific; Europe; Middle East & Africa | North America (35.0% share) | Asia-Pacific (10.2% CAGR) |
Market Segmentation Overview
| Sub-Segment | Key Trend |
|---|
| extrusion water purifiers | Squeeze and plunger designs valued for dirty-source durability |
| pump water purifiers | High-flow units retained for expeditions and groups |
| suction water purifiers | Straw formats dominate low-cost travel and aid kits |
| UV-pen purifiers | Lighter bodies and USB charging attract ultralight users |
| Others: filter bottles, gravity bags, etc. | Filter bottles cross over into everyday carry |
Extrusion water purifiers lead because squeeze and plunger mechanisms work with silty water and need no power, which suits extended trips. UV-pen purifiers grow fastest, driven by ultralight hikers and frequent flyers who value short treatment cycles and no consumable filters. Suction water purifiers and filter bottles serve buyers prioritizing price and convenience over flow rate.
| Sub-Segment | Key Trend |
|---|
| gravity purifiers | Hands-free group filtration with larger reservoirs |
| UV purifiers | LED efficiency improves battery life and cycle speed |
| RO purifiers | Battery-powered models target PFAS and dissolved solids |
| Others: electro-adsorption, nano-filtration, etc. | Low-pressure virus capture without power |
Gravity purifiers hold the lead because they treat large volumes unattended for families and camps. RO purifiers expand fastest as preparedness buyers seek chemical and PFAS reduction that UV purifiers cannot deliver. Electro-adsorption and nano-filtration media are gaining attention for virus capture in compact, unpowered housings.
| Sub-Segment | Key Trend |
|---|
| residential | Outage backup and travel drive household purchases |
| Commercial: schools, military, hospitals, etc. | Continuity planning and field deployment contracts |
Residential buyers dominate, using portable units for outages, travel and rental homes where installation is impractical. Commercial demand grows fastest because schools, military units and hospitals now specify virus-rated, serviceable purifiers in resilience plans, favoring suppliers with documented test performance and spare-part support.
| Sub-Segment | Key Trend |
|---|
| B2C/retail (multi-brand stores, exclusive brand outlets, online, and other distribution channels) | Online share rises as reviews and certification labels guide choice |
| B2B/directly from the manufacturers | Multi-year tenders with defense and humanitarian agencies |
B2C/retail leads as multi-brand stores and exclusive brand outlets offer demonstration while online platforms win on range. B2B/directly from the manufacturers grows faster because institutional buyers negotiate bulk volumes, custom packaging and service terms directly with producers.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA