Port Equipment Market (2026 - 2035)

Port Equipment Market Research Report By Equipment Type (Cranes, Trucks and Terminal Tractors, Reach Stackers and Container Handlers, Straddle and Shuttle Carriers, Other Equipment), By Application (Container Handling, Bulk Handling, Warehouse and Yard Logistics, Ship and Vessel Operations), By Fuel Type (Diesel, Electric and Hybrid, Alternative Fuels), By Operation Mode (Conventional (Manual/Semi-Auto), Fully Autonomous) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth & Industry Forecast to 2035
ID: MRFR/Equip/10880-HCR
128 Pages
Harshita Gorde
Last Updated: August 28, 2026
Port Equipment Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.80%
2025 Market SizeUSD 21.98 Billion
2035 Market SizeUSD 38.51 Billion
Key Players
ZPMC
Konecranes
Kalmar
Liebherr
Sany Marine
Hyster-Yale
Opportunities
  • Retrofit and Repowering as a Standalone Revenue Line
  • Equipment-as-a-Service and Availability Contracting
  • Fleet Telemetry and Predictive Maintenance Monetization

Port Equipment Market Summary

The Port Equipment Market closed 2025 at USD 21.98 billion and enters the forecast window at USD 23.18 billion in 2026, climbing to USD 38.51 billion by 2035 at a 5.80% CAGR. Two catalysts anchor that trajectory. The United States has committed roughly USD 20 billion to onshore ship-to-shore crane manufacturing and hardening terminal cyber-defences [2]. At the same time, China's automated gateways moved 16.04 billion tons of cargo and roughly 300 million containers in 2024, a 3.4% year-on-year gain that keeps replacement demand structurally elevated [1].

Terminal operators are retiring diesel-hydraulic yard fleets and manually driven gantry lines that have run since the early 2000s. Replacing them: battery-electric tractors, remote-operated gantries, and cab-less carriers governed by digital twin scheduling engines. The Port Equipment Market now sits at the intersection of heavy machinery and software, with the European Union's Alternative Fuels Infrastructure Regulation requiring shore-power provision at major TEN-T seaports from 2030 [5], pulling forward billions in electrification capex.

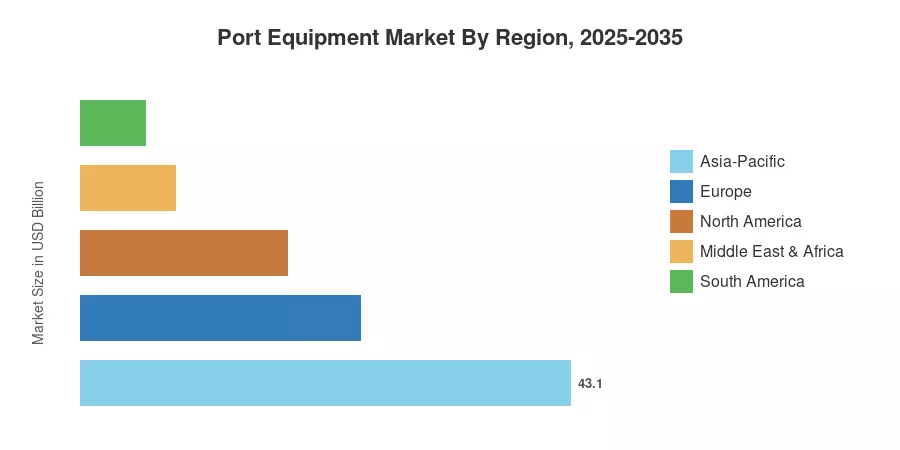
Asia-Pacific holds 43.1% of the Port Equipment Market and simultaneously grows fastest at a 6.61% CAGR, propelled by Chinese and Indian terminal buildouts. Europe follows at 24.6%, where decarbonization compliance rather than throughput growth drives spend. North America ranks third on retrofit and security-driven procurement. The decade ahead belongs to operators who treat equipment as networked infrastructure.


Key Report Takeaways

• By Equipment Type


  • Cranes command 52.4% of the Port Equipment Market, retaining the largest equipment-type position through 2035
  • Fully autonomous operation modes are forecast to expand at a 17.17% CAGR, the fastest of any dimension tracked.
  • Electric and hybrid propulsion units post a 9.58% CAGR as diesel fleets reach end-of-life.

• By Application

  • Container handling accounts for 50.9% of the Port Equipment Market, reflecting box volume concentration at hub gateways.
  • Warehouse and yard logistics applications grow at an 8.59% CAGR through 2035
  • Bulk handling equipment represents USD 4.70 billion of 2025 demand

• By Region

Market Size and Forecast (2021–2035)

Estimates combine port authority capital budgets, OEM order backlogs, customs-level equipment import data, and throughput statistics from national transport ministries. Historical values were reconciled against installed-base counts at the world's 120 largest container terminals; forecasts apply fleet-age curves layered with announced electrification mandates. The Port Equipment Market model treats retrofit revenue as in-scope where it materially extends asset life.
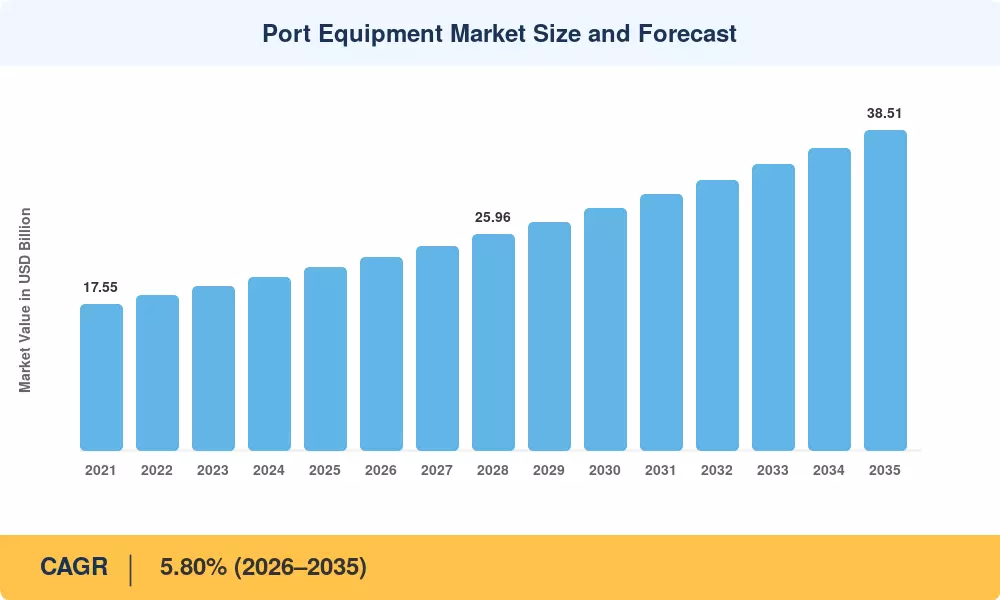
Port Equipment Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Terminal automation and AI yard orchestration ~1.30 Asia-Pacific, Europe Medium-term (2–4 yr)
IMO decarbonization and shore-power mandates ~1.10 Global Long-term (≥4 yr)
Ultra-large vessel cascade forcing quay upgrades ~0.90 Asia-Pacific, MEA Short-term (≤2 yr)
Public port infrastructure funding programs ~0.80 North America, Europe, India Medium-term (2–4 yr)
Crane manufacturing onshoring and cyber hardening ~0.60 North America Short-term (≤2 yr)
Aging diesel fleet replacement cycle ~0.55 Global Long-term (≥4 yr)
Battery and hydrogen cost declines ~0.40 Europe, Asia-Pacific Long-term (≥4 yr)


Terminal Automation and AI Yard Orchestration

Automation has moved past pilot status. Shanghai's Yangshan Phase IV and Rotterdam's Maasvlakte II now run cab-less horizontal transport at scale, and the International Transport Forum estimates automated terminals cut per-move energy consumption by 15–25% versus manual equivalents [3]. That efficiency delta reframes automation as an operating-cost decision rather than a labour one, which is why the Port Equipment Market sees autonomous units growing at 17.17%. In comparison, conventional modes still hold 85.5% of the installed base.

Decarbonization and Shore-Power Compliance

The IMO's revised greenhouse gas strategy targets net-zero shipping emissions around 2050, with checkpoints at 2030 and 2040 [4]. Ports absorb a share of that burden through berth-side emissions rules. The EU's Alternative Fuels Infrastructure Regulation obliges TEN-T core seaports to supply onshore power to container and passenger vessels by January 2030 [5], and California's CARB at-berth regulation already covers roughly 2,300 vessel visits annually [8]. Each rubber-tired gantry RTG crane conversion to cable-reel or battery power now carries a compliance rationale alongside its fuel-cost case.

Vessel Upsizing and Quay Crane Obsolescence

Container ships above 18,000 TEU require outreach beyond 24 rows — a specification most cranes installed before 2012 cannot meet. Retrofit boom extensions cost 30–40% of a new unit but deliver only partial capability, pushing many operators to full replacement [7]. Roughly 41% of the global quay crane fleet is over 15 years old, creating a replacement backlog that underpins the crane segment's 7.46% CAGR.

Public Infrastructure Funding

Washington's Port Infrastructure Development Program has awarded over USD 1.7 billion since 2022, with a mandated domestic-content share [2]. India's Sagarmala initiative lists more than 800 projects worth about USD 70 billion through 2035 [9]. Public money de-risks the first automation tranche at mid-tier ports that could not otherwise finance it.


Restraints Impact Analysis

Restraint weightings are directional drags on headline growth, assigned through operator interviews and project-delay tracking. They are not subtractive inputs to the CAGR calculation.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
High capital intensity and 8–12 year payback ~-0.90 Global Long-term (≥4 yr)
Grid capacity and interconnection delays ~-0.70 North America, Europe Medium-term (2–4 yr)
Labour resistance to automated operations ~-0.60 North America, Europe Short-term (≤2 yr)
Tariffs and trade friction on crane imports ~-0.50 North America Short-term (≤2 yr)
Fragmented interoperability and retrofit standards ~-0.40 Global Medium-term (2–4 yr)


Capital Intensity and Payback Duration

A single ship-to-shore unit runs USD 12–15 million installed; a full electrified yard fleet at a mid-size terminal exceeds USD 200 million. Against typical concession terms of 25–30 years, operators face payback horizons of 8–12 years on electrification alone [7]. The Port Equipment Market therefore skews toward staged procurement, with mixed-fleet transitions rather than wholesale replacement.

Grid Constraints at the Fence Line

Electrification assumes power that often is not there. The IEA notes global grid investment must roughly double to about USD 600 billion annually by 2030 to keep pace with electrification demand [6]. Terminals in Northern Europe and the US West Coast report interconnection queues of 24–48 months, and several operators have deferred equipment orders until substation upgrades are confirmed.

Labour and Social Licence

Automation agreements remain contested. The 2024 US East and Gulf Coast dockworker dispute ended with contract language restricting fully automated equipment deployment [10]. Similar constraints exist at several European and Australian gateways. Where automation is bargained rather than mandated, deployment timelines stretch by two to four years.


Port Equipment Market Opportunities

Retrofit and Repowering as a Standalone Revenue Line

Converting legacy diesel port equipment to battery-electric drivetrains costs 35–45% of a new unit and can extend service life by a decade. UN Trade and Development (UNCTAD) reports that world container port throughput reached 920 million TEUs, intensifying yard wear. OEMs package retrofits with fixed-price programs, reducing downtime across dense logistics hubs.


Equipment-as-a-Service and Availability Contracting

Rather than selling machines, several suppliers now sell guaranteed crane availability priced per container move. Industry evaluations place the global port equipment market valuation at USD 21.66 billion. This model shifts residual-value risk to the OEM, giving capital-constrained terminals access to modern fleets while capturing recurring telemetry data streams.


Fleet Telemetry and Predictive Maintenance Monetization

Instrumented equipment produces thousands of data points per move. Aggregated across fleets, that stream supports predictive spares positioning and pricing. Market analyses indicate that warehouse and yard logistics equipment is expanding at 7.2% CAGR, maximizing data monetization potential through advanced cloud subscription analytics platforms.


Hydrogen and Alternative Fuel Pilots

Where duty cycles defeat battery swapping — heavy straddle operations, 24-hour bulk terminals — hydrogen fuel cells offer a path. The Port Equipment Market currently attributes 6.6% of fuel-type demand to alternative fuels, but Rotterdam, Valencia, and Los Angeles pilots position this as the decade's option value.


Port Equipment Market Future Outlook

Autonomy Moves From Yard to Quay

Horizontal transport automation is largely solved; the frontier is the ship-to-shore interface, where lashing, twist-lock handling, and vessel motion still require human judgment. Machine-vision spreader guidance and remote-supervised quay operation are moving toward commercial deployment, and the Port Equipment Market should see supervised-autonomous quay cranes reach meaningful share by the early 2030s [3].

Software Margins Reshape Supplier Economics

Terminal operating systems, equipment control systems, and fleet analytics now influence procurement decisions as heavily as lift capacity. Suppliers with integrated software stacks capture recurring revenue at gross margins well above hardware, and this gap is driving acquisitions of independent automation specialists [11].

The Electrification Supercycle

The IEA projects that grid investment must approach USD 600 billion annually by 2030 to support electrification across sectors [6]. Ports are early, concentrated load centres. Combined with the reach stacker container handler and terminal tractor replacement wave, this positions electric and hybrid units on a 9.58% CAGR through 2035 within the Port Equipment Market.

Emissions Reporting Becomes Procurement Criteria

Carriers under the EU Emissions Trading System and FuelEU Maritime are increasingly asking terminals for verified berth-side emissions data [5]. Equipment that cannot report energy consumption per move at asset level will struggle in tenders. Expect embedded metering and audited reporting to become standard specification lines by 2028.


Port Equipment Market Segmentation

By Equipment Type

The Port Equipment Market divides most cleanly along equipment class, where crane economics dominate capital allocation.

Segment Metric Primary Demand Driver
Cranes 52.4% share Vessel upsizing and quay obsolescence
Trucks and terminal tractors 7.98% CAGR Drayage electrification mandates
Reach stackers and container handlers. USD 2.70 Billion Intermodal and inland terminal growth
Straddle and shuttle carriers 8.7% share Automation-ready yard reconfiguration
Other equipment USD 1.69 Billion Bulk conveyors, shiploaders, mooring systems


Cranes retain over half of spend because a single quay crane costs more than a dozen yard tractors, and because outreach requirements are non-negotiable once a terminal targets larger vessel classes. Terminal tractors, by contrast, lead on growth rather than value: short, predictable duty cycles make them the easiest asset class to electrify, and fleet sizes are large enough that unit-cost declines compound quickly.

By Application

Application mix in the Port Equipment Market reflects the container's dominance of general cargo economics.

Segment Metric Primary Demand Driver
Container handling 50.9% share Global box throughput records [1]
Bulk handling USD 4.70 Billion Grain, ore and energy commodity flows
Warehouse and yard logistics 8.59% CAGR Inland depot and free-zone expansion
Ship and vessel operations 11.9% share Mooring, bunkering and shore-power systems


Container handling anchors the segment because box terminals turn assets hardest and replace them fastest. Warehouse and yard logistics is the growth story: as terminals push storage inland to relieve quay congestion, demand shifts toward smaller, higher-cycle equipment operating in enclosed environments where electric drivetrains face no range constraint.

By Fuel Type

Segment Metric Primary Demand Driver
Diesel 64.8% share Installed base inertia and duty-cycle reliability
Electric and hybrid 9.58% CAGR Emissions rules and fuel-cost arbitrage
Alternative fuels USD 1.45 Billion Hydrogen and LNG pilot programs


The segment is dominated by Diesel, which holds a 64.8% share driven by installed base inertia and reliability. Meanwhile, Electric and hybrid represent the fastest-growing segment, expanding at 9.58% CAGR due to emission rules and cost arbitrage. Alternative fuels stand at USD 1.45 billion, propelled by hydrogen and LNG pilots. Relevant policy frameworks include the IMO greenhouse gas strategy and the EU Alternative Fuels Infrastructure Regulation (AFIR), driving green transitions.

By Operation Mode

Segment Metric Primary Demand Driver
Conventional (manual/semi-auto) 85.5% share Legacy fleet and labour agreements
Fully autonomous 17.17% CAGR Greenfield terminals and productivity mandates


Conventional equipment still overwhelms the installed base, and will for another decade. Fully autonomous systems nonetheless grow three times faster than any other cut of the Port Equipment Market, concentrated almost entirely in greenfield projects where no incumbent workforce agreement constrains deployment.


Regional Market Share Analysis

Region Share (2025, %) Primary Investment Themes
Asia-Pacific 43.1 Greenfield capacity, full automation, domestic OEM scale
Europe 24.6 Shore power, AFIR compliance, brownfield retrofit
North America 18.2 Onshoring, cyber hardening, drayage electrification
Middle East & Africa 8.4 Transshipment hubs, logistics free zones
South America 5.7 Bulk export terminals, concession renewals
Total 100.0

Regional weighting in the Port Equipment Market tracks container throughput concentration more closely than GDP, which is why Asia-Pacific's lead is structural rather than cyclical.


North America

Country Metric Key Driver
US 79.4% share of region Port Infrastructure Development Program awards [2]
Canada 5.68% CAGR Prince Rupert and Vancouver capacity expansion
Mexico USD 0.42 Billion Nearshoring volumes at Manzanillo and Veracruz


American procurement is being reshaped by policy rather than volume. Federal action to reduce dependence on foreign-manufactured cranes has triggered domestic assembly commitments and mandatory cybersecurity assessments across major container gateways [2]. Terminals are simultaneously absorbing California's at-berth rules [8], making the US the most regulation-intensive buying environment in the Port Equipment Market despite mid-single-digit volume growth.

Europe

Country Metric Key Driver
Germany USD 1.19 Billion Hamburg and Bremerhaven automation programs
UK 14.8% share of region Freeport incentives and London Gateway expansion
France 5.31% CAGR Haropa multimodal investment plan
Italy 10.2% share of region Genoa breakwater and terminal modernization
Spain USD 0.51 Billion Algeciras and Valencia transshipment volumes
Nordic Countries 6.02% CAGR Early shore-power adoption
Russia 4.9% share of region Domestic sourcing under sanctions
Rest of Europe USD 0.63 Billion Baltic and Adriatic corridor upgrades


Europe buys for compliance. AFIR's 2030 shore-power obligation at TEN-T core ports has converted a discretionary upgrade into a dated deliverable [5], and terminal operators are sequencing crane electrification, substation reinforcement, and yard fleet conversion into single multi-year programs. Rotterdam and Antwerp-Bruges anchor the region's technical standards.

Asia-Pacific

Country Metric Key Driver
China 46.3% share of region Automated terminal rollout; 16.04 Bn tons throughput [1]
India 8.14% CAGR Sagarmala and Vadhavan port development [9]
Japan USD 0.88 Billion Aging fleet replacement at Keihin ports
South Korea 9.6% share of region Busan Jinhae smart port project
ASEAN 7.42% CAGR Vietnam and Indonesia capacity additions
Rest of Asia-Pacific USD 0.61 Billion Australian and Pacific bulk terminals


Scale and domestic manufacturing reinforce each other here. Chinese suppliers build for a home market that operates the world's largest automated terminal estate, then export the resulting cost position. India represents the region's steepest growth curve, with more than 800 Sagarmala projects and greenfield deep-water capacity at Vadhavan requiring complete equipment fleets [9].

South America

Country Metric Key Driver
Brazil 58.2% share of region Santos expansion and agri-bulk exports
Argentina USD 0.21 Billion Paraná waterway concession renewal
Rest of South America 6.11% CAGR Chilean and Peruvian copper terminals


Commodity cycles set the tempo. Brazilian soybean and iron ore volumes drive shiploader and conveyor investment more than container equipment, while Peru's Chancay terminal has introduced automated container handling as a regional benchmark. Concession renewal calendars, not emissions rules, determine when capital gets committed.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 27.4% share of region Vision 2030 logistics hub strategy
UAE USD 0.54 Billion Jebel Ali automation and DP World fleet renewal
South Africa 5.94% CAGR Transnet terminal recapitalization
Egypt 11.8% share of region Suez Canal Economic Zone terminals
Rest of MEA USD 0.29 Billion West African gateway development


Gulf ports are buying ahead of demand deliberately, positioning as transshipment alternatives amid Red Sea routing volatility. South Africa's Transnet recapitalization addresses an equipment availability crisis that cut Durban productivity sharply, and represents one of the largest single procurement opportunities in the region.


Port Equipment Market By Region, 2025-2035

Competitive Benchmarking

Concentration is moderate. The estimated Herfindahl-Hirschman Index sits near 950–1,100, with the top five suppliers holding roughly 55–62% of global revenue. One Chinese manufacturer holds a commanding position in quay cranes, while yard and mobile equipment remains materially more fragmented — regional specialists compete effectively on service coverage and delivery lead time.

Company Est. Revenue Share Range Key Offerings for Port Equipment Market Strategic Positioning
ZPMC ~26–31% STS cranes, gantry systems, automated terminal packages Global quay crane volume leader; scale cost advantage
Konecranes ~9–12% Yard cranes, lift trucks, automation software Broadest product breadth; strong service annuity
Kalmar ~8–11% Terminal tractors, straddle carriers, electric handlers Electrification pure-play focus post-separation
Liebherr ~6–9% Mobile harbour cranes, ship-to-shore, offshore cranes Engineering-led premium positioning
Sany Marine ~4–7% Container handlers, cranes, port machinery Aggressive pricing in emerging markets
Hyster-Yale ~3–5% Empty and laden container handlers, reach stackers Strong dealer network in the Americas
Cargotec Group ~3–5% Cargo flow solutions, load handling systems Portfolio realignment toward high-margin services
Toyota Industries ~2–4% Terminal tractors, industrial handling equipment Manufacturing scale and lean production
TMEIC ~2–4% Crane drives, automation and control systems Embedded control-layer specialist
Terex Port Solutions ~2–3% Mobile harbour equipment, straddle carriers Niche mobility and flexibility focus


Recent News & Developments

  • US Administration (February 2024): Announced roughly USD 20 billion to rebuild domestic crane manufacturing capacity and impose cyber-security requirements on foreign-made port cranes, restructuring North American sourcing [2]
  • European Union (October 2023): Adopted the Alternative Fuels Infrastructure Regulation mandating shore-power supply at TEN-T core seaports from 2030, creating a dated compliance market [5]


  • ILA and USMX (January 2025): Ratified a six-year master contract containing restrictions on fully automated equipment across US East and Gulf Coast terminals [10]
  • DP World (June 2024): Committed to a multi-year electrification program across Jebel Ali and international terminals, including battery-electric yard fleets
  • Konecranes (September 2024): Expanded its remote-operation and fleet-analytics offering, bundling equipment supply with availability-based service contracts
  • India Ministry of Ports (August 2024): Approved the Vadhavan deep-water port project, one of the largest greenfield equipment procurement pipelines in South Asia [9]
  • IMO MEPC (July 2023): Adopted the revised greenhouse gas strategy targeting net-zero shipping emissions by around 2050, cascading emissions pressure into port operations [4]


Port Equipment Market Report Scope

Parameter Detail
Market Scope Global Port Equipment Market covering cranes, trucks, container handlers, carriers and ancillary port machinery
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 5.80% (2026–2035)
Market Size Checkpoints USD 21.98 Billion (2025); USD 23.18 Billion (2026); USD 38.51 Billion (2035)
Fastest Growing Segments Fully autonomous operation (17.17% CAGR); Electric and hybrid fuel (9.58% CAGR); Warehouse and yard logistics (8.59% CAGR)
Companies Profiled ZPMC, Konecranes, Kalmar, Liebherr, Sany Marine, Hyster-Yale, Cargotec, Toyota Industries, TMEIC, Terex
Valuation Currency USD Billion, constant 2025 prices

FAQs

What total cost of ownership assumptions should buyers test before committing to the Port Equipment Market's electric equipment options?
Model electricity tariffs including demand charges, not just energy rates, since peak charges often exceed consumption costs at terminals. Battery replacement at year seven and residual value at end of concession are the two variables that most often break the business case [13].
How should a terminal decide between retrofitting existing cranes and buying new units?
Retrofit makes sense when the structure has 15 or more years of fatigue life remaining, and outreach already meets vessel requirements. If outreach is short for target ship classes, replacement is the only path — boom extensions rarely deliver full capability [7].
What cyber-security requirements now apply to Port Equipment Market procurement in the United States?
Federal directives require operators of foreign-manufactured cranes to conduct vulnerability assessments and segregate operational technology networks from corporate IT. Vendor remote-diagnostics access must be logged, time-bounded, and terminated at contract end [2].
Are equipment control systems interoperable across manufacturers?
Largely not. Terminal operating system integration typically requires custom middleware for each equipment brand, which is why mixed-vendor automated yards cost more to commission. Buyers should negotiate open API commitments before signing [11].
What lead times should buyers plan for in the Port Equipment Market today?
Ship-to-shore cranes run 24 to 36 months from order to commissioning, including transport and erection. Yard equipment typically ships in 9 to 15 months, though electric variants face longer battery cell allocation queues [7].
How does equipment choice affect a terminal's Container Port Performance Index ranking?
Ranking hinges on berth productivity — crane moves per hour and vessel turnaround time. Equipment count and quay length matter less than yard flow design, so investing in horizontal transport often improves scores more than adding cranes [11].
What workforce planning does automation require?
Each automated yard converts driver roles into remote-operator and maintenance technician positions, typically at a three-to-one reduction. Successful deployments budget 12 to 18 months of retraining before go-live and negotiate transition terms early [10].    
Author
Author
Author Profile
Harshita Gorde LinkedIn Research Analyst
Harshita Post graduate MBA in Business Administration from Welingkar Institute, Mumbai and 5 years of experience in the field of product market research. As a Research Analyst, I have cross-domain experience in packaging, and industrial Automation & Equipment. I am currently looking after the research process of packaging, logistics & transportation, and industrial automation & equipment at Market Research Future Reports. My responsibilities at the organization involve handling syndicate and custom reports as well as responding to client inquiries, and organize, co-ordinate with a group of 5 to 6 persons to manage all workflows.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, maritime industry publications, trade statistics, and authoritative transportation organizations. Key sources included the International Maritime Organization (IMO), International Association of Ports and Harbors (IAPH), American Association of Port Authorities (AAPA), European Sea Ports Organization (ESPO), Drewry Maritime Research, United Nations Conference on Trade and Development (UNCTAD) Review of Maritime Transport, World Shipping Council (WSC), Organisation for Economic Co-operation and Development (OECD) Transport Statistics, World Bank Logistics Performance Index, Bureau of Transportation Statistics (BTS), Eurostat Maritime Transport Statistics, United Nations Economic Commission for Europe (UNECE) Transport Statistics, International Transport Forum (ITF), Lloyd's List Intelligence, IHS Markit Maritime & Trade, and national port authority reports from key markets including Maritime and Port Authority of Singapore (MPA), China Maritime Safety Administration, and port authorities of Los Angeles, Rotterdam, and Hamburg. These sources were used to collect port throughput statistics, equipment procurement data, automation adoption trends, trade volume analysis, regulatory compliance requirements, and competitive landscape assessment for cranes, automated guided vehicles (AGVs), straddle carriers, reach stackers, terminal tractors, and port automation software systems.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. Supply-side sources comprised Chief Executive Officers, Chief Technology Officers, Vice Presidents of Engineering, leaders of commercial strategy, and global sales directors from port equipment manufacturers, automation solution providers, and component suppliers. Port terminal operators, chief operating officers of port authorities, procurement directors of container terminals, fleet managers, marine engineers, and leaders of automation from the world's most prominent container ports, bulk terminals, and general cargo facilities comprised demand-side sources. Market segmentation was verified, product development roadmaps were confirmed, and insights regarding fleet modernization cycles, automation investment priorities, TCO (Total Cost of Ownership) dynamics, and port infrastructure expansion plans were obtained through primary research.

Primary Respondent Breakdown:

By Designation: C-level Primaries (42%), Director Level (33%), Others (25%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through revenue mapping and equipment fleet analysis. The methodology included:

Identification of 50+ key manufacturers across North America, Europe, Asia-Pacific, and Latin America

Product mapping across ship-to-shore (STS) cranes, rubber-tired gantry (RTG) cranes, rail-mounted gantry (RMG) cranes, automated stacking cranes (ASCs), straddle carriers, reach stackers, terminal tractors, and port automation software & solutions

Analysis of reported and modeled annual revenues specific to port equipment and related service portfolios

Coverage of manufacturers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (equipment unit sales × ASP by equipment type and region) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















