Polyvinylidene Fluoride Market (2026 - 2035)

ID: MRFR/CnM/3058-CR 449 Pages Chitranshi Jaiswal Last Updated: October 14, 2026
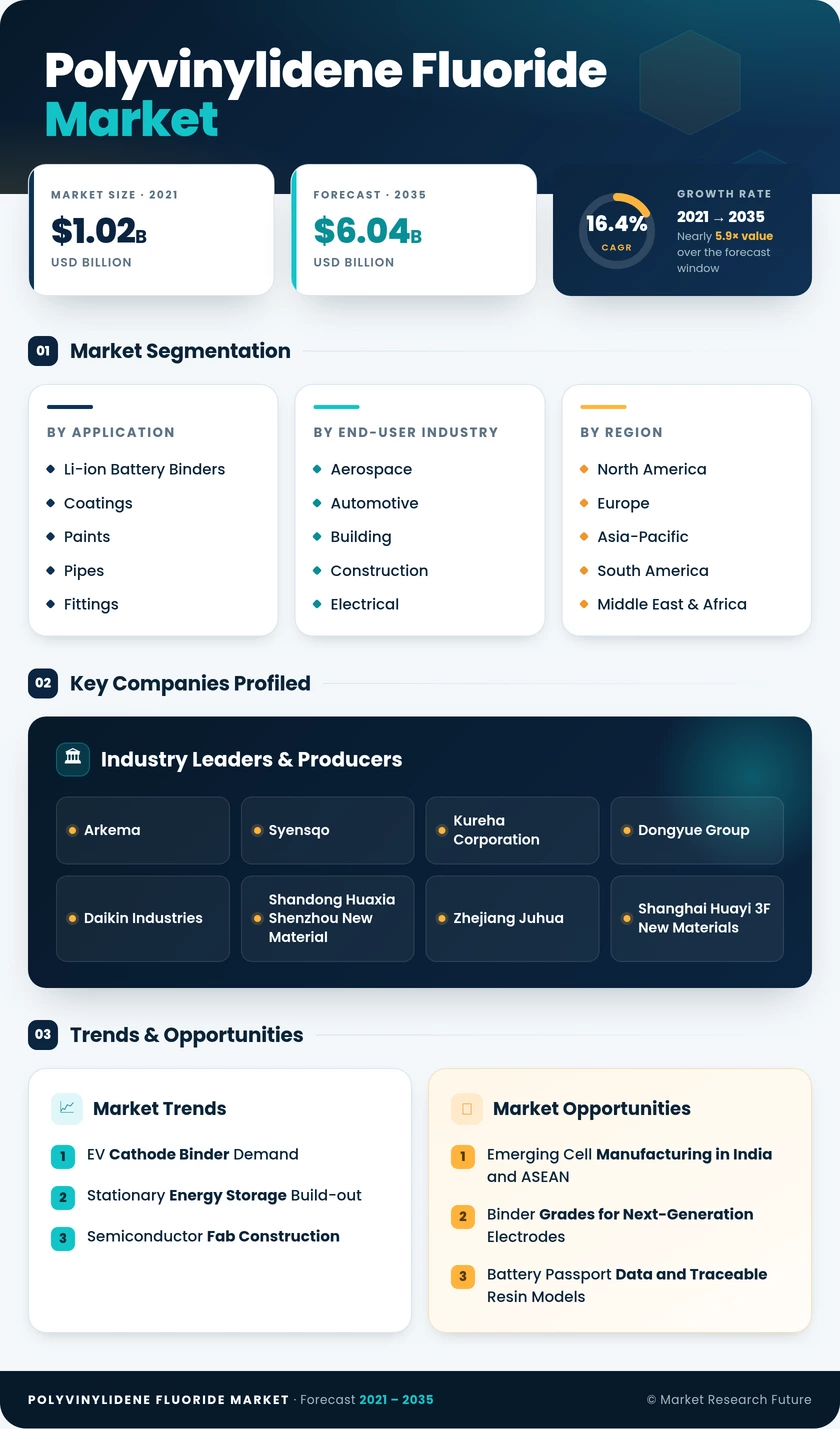
Polyvinylidene Fluoride Market Research Report Information By Application (Li-ion Battery Binders, Coatings and Paints, Pipes and Fittings, Films and Sheets, Wire and Cable Insulation, and Other Applications), and By End-user Industry (Aerospace, Automotive, Building and Construction, Electrical and Electronics, Industrial and Machinery, Packaging, and Other End-user Industries) – Forecast Till 2035.
Polyvinylidene Fluoride Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)16.4%
2025 Market SizeUSD 1.32 Billion
2035 Market SizeUSD 6.04 Billion
Key Players
Arkema
Syensqo
Kureha Corporation
Dongyue Group
Daikin Industries
Shandong Huaxia Shenzhou New Material
Opportunities
  • Emerging Cell Manufacturing in India and ASEAN
  • Binder Grades for Next-Generation Electrodes
  • Battery Passport Data and Traceable Resin Models
  1. 1 Market Summary | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Application | |
    2. 2.2 By End-user Industry | |
    3. 2.3 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Forecast Market Size (2026–2035) | |
    3. 3.3 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 EV Cathode Binder Demand | |
    2. 4.2 Stationary Energy Storage Build-out | |
    3. 4.3 Semiconductor Fab Construction | |
    4. 4.4 Water Reuse and Desalination Membranes | |
    5. 4.5 Battery Materials Onshoring Incentives | |
    6. 4.6 Durable Architectural Coatings | |
    7. 4.7 Solar PV Backsheets and Films | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 EU Universal PFAS Restriction Proposal | |
    2. 5.2 Battery-Grade Overcapacity in China | |
    3. 5.3 Water-Based and Dry-Electrode Substitution | |
    4. 5.4 Feedstock and Fluorspar Supply Constraints | |
    5. 5.5 PFAS Liability and Producer Exits | |
  6. 6 Opportunities | |
    1. 6.1 Emerging Cell Manufacturing in India and ASEAN | |
    2. 6.2 Binder Grades for Next-Generation Electrodes | |
    3. 6.3 Battery Passport Data and Traceable Resin Models | |
    4. 6.4 Water Reuse Membranes in the Middle East | |
    5. 6.5 Localised Semiconductor Piping Supply | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of MEA | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 The Electrification Supercycle | |
    2. 8.2 PFAS Regulation and Product Redesign | |
    3. 8.3 Semiconductors and AI Data Centres | |
    4. 8.4 Carbon Reporting and Circularity | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Application | | |
      1. 9.1.1 Li-ion Battery Binders | | |
      2. 9.1.2 Coatings and Paints | | |
      3. 9.1.3 Pipes and Fittings | | |
      4. 9.1.4 Films and Sheets | | |
      5. 9.1.5 Wire and Cable Insulation | | |
      6. 9.1.6 Other Applications | |
    2. 9.2 By End-user Industry | | |
      1. 9.2.1 Aerospace | | |
      2. 9.2.2 Automotive | | |
      3. 9.2.3 Building and Construction | | |
      4. 9.2.4 Electrical and Electronics | | |
      5. 9.2.5 Industrial and Machinery | | |
      6. 9.2.6 Packaging | | |
      7. 9.2.7 Other End-user Industries | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Arkema | | |
      2. 10.3.2 Syensqo | | |
      3. 10.3.3 Kureha Corporation | | |
      4. 10.3.4 Dongyue Group | | |
      5. 10.3.5 Daikin Industries | | |
      6. 10.3.6 Shandong Huaxia Shenzhou New Material | | |
      7. 10.3.7 Zhejiang Juhua | | |
      8. 10.3.8 Shanghai Huayi 3F New Materials | | |
      9. 10.3.9 Gujarat Fluorochemicals | | |
      10. 10.3.10 Orbia (Koura) | | |
      11. 10.3.11 Sinochem Lantian | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Market Snapshot, 2025 and 2035 | |
  16. TABLE 2 Global Market Size and Forecast, by Revenue (USD Billion), 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis, 2026–2035 | |
  18. TABLE 4 Restraints Impact Analysis, 2026–2035 | |
  19. TABLE 5 Regional Summary, by Region, 2025 | |
  20. TABLE 6 North America Market, by Country, 2025 | |
  21. TABLE 7 Europe Market, by Country, 2025 | |
  22. TABLE 8 Asia-Pacific Market, by Country, 2025 | |
  23. TABLE 9 South America Market, by Country, 2025 | |
  24. TABLE 10 Middle East & Africa Market, by Country, 2025 | |
  25. TABLE 11 Global Market, by Application, 2025–2035 | |
  26. TABLE 12 Global Market, by End-user Industry, 2025–2035 | |
  27. TABLE 13 Competitive Benchmarking Matrix, 2025 | |
  28. TABLE 14 Report Scope and Methodology | |
  29. TABLE 15 Detailed Sources and Citations | |
  30. TABLE 16 Segmentation Quick Reference | |
  31. TABLE 17 Market Segmentation Overview, by Application | |
  32. TABLE 18 Market Segmentation Overview, by End-user Industry | | LIST OF FIGURES | |
  33. FIGURE 1 Market Dynamics Overview (Drivers, Restraints, Opportunities) | |
  34. FIGURE 2 Industry Value Chain Analysis | |
  35. FIGURE 3 Porter's Five Forces Analysis | |
  36. FIGURE 4 Global Market Size Trend (USD Billion), 2021–2035 | |
  37. FIGURE 5 Year-over-Year Growth Trend, 2021–2035 | |
  38. FIGURE 6 Market Share, by Application, 2025 | |
  39. FIGURE 7 Market Share, by End-user Industry, 2025 | |
  40. FIGURE 8 Regional Market Share, 2025 | |
  41. FIGURE 9 Asia-Pacific Market Share, by Country, 2025 | |
  42. FIGURE 10 Europe Market Share, by Country, 2025 | |
  43. FIGURE 11 Competitive Landscape: Estimated Revenue Share Ranges, 2025 | |
  44. FIGURE 12 Driver and Restraint Impact Comparison

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By ApplicationLi-ion Battery Binders; Coatings and Paints; Pipes and Fittings; Films and Sheets; Wire and Cable Insulation; Other ApplicationsLi-ion Battery Binders (27.0% CAGR)Li-ion Battery Binders (27.0% CAGR)
By End-user IndustryAerospace; Automotive; Building and Construction; Electrical and Electronics; Industrial and Machinery; Packaging; Other End-user IndustriesElectrical and Electronics (29.6% share)Automotive (24.3% CAGR)
By RegionNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaAsia-Pacific (58.4% share)Asia-Pacific (58.4% share)

Market Segmentation Overview

By Application

Sub-SegmentKey Trend
Li-ion Battery BindersLower loading per kWh and high-nickel stability
Coatings and PaintsFluorosurfactant-free, long-warranty façade systems
Pipes and FittingsFab-certified high-purity welded systems
Films and SheetsCompetition from PET and glass-glass modules
Wire and Cable InsulationLow-smoke aerospace and plenum cabling
Other ApplicationsChlorine-tolerant hollow-fibre membranes

Li-ion Battery Binders lead and grow fastest because high-nickel cathodes need a binder that stays stable above 150 °C during drying and cycling, and cell makers rarely requalify once a grade is approved. Coatings and Paints remain the second pillar but face solvent rules in mature regions. Membranes within Other Applications are the next fastest climber, as chlorine-tolerant hollow fibres displace polysulfone in water reuse.

By End-user Industry

Sub-SegmentKey Trend
AerospaceFAA-compliant low-smoke wiring
AutomotiveEV gigafactory binder qualification
Building and ConstructionCoastal cladding and corrosion-proof piping
Electrical and ElectronicsSemiconductor fluid handling and devices
Industrial and MachineryAcid- and caustic-service pumps and valves
PackagingPharmaceutical blister moisture barriers
Other End-user IndustriesWater treatment and energy assets

Electrical and Electronics holds the largest share because semiconductor fabs, circuit boards and device makers specify the resin for purity and flame performance. Automotive grows fastest as EV cell plants in China, South Korea, Europe and North America qualify binder supply. Aerospace and Packaging stay small but profitable, insulating producers from feedstock price swings.


Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.