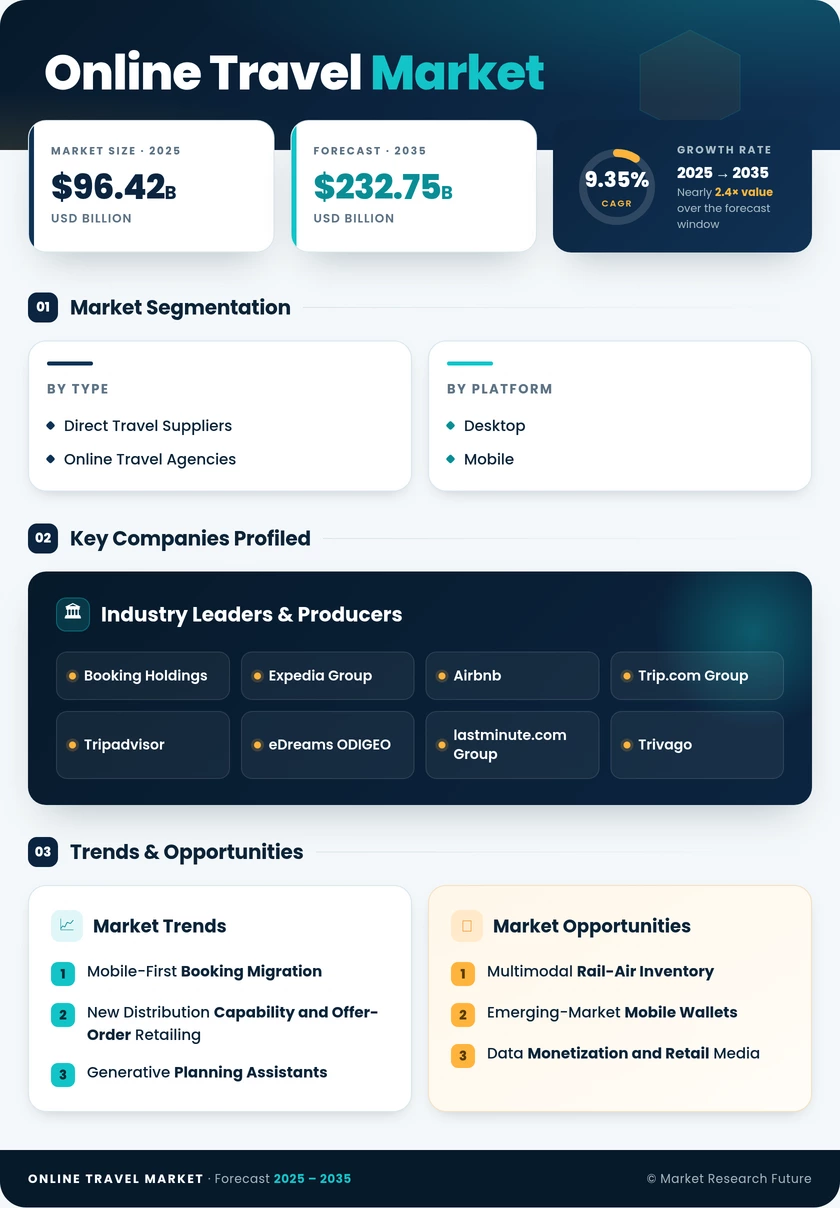
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Service Type | Transportation; Travel Accommodation; Vacation Packages; Other Service Types | Transportation | Vacation Packages |
| By Booking Type | Online Travel Agencies; Direct Travel Suppliers | Direct Travel Suppliers | Online Travel Agencies |
| By Platform | Desktop; Mobile | Desktop | Mobile |
| By Geography | North America; Europe; Asia-Pacific; South America; Middle East & Africa | Europe | Asia-Pacific |
Market Segmentation Overview
By Service Type
| Sub-Segment | Key Trend |
| Transportation | Commission compression pushes platforms toward ancillary attach and continuous pricing |
| Travel Accommodation | Rate-parity erosion intensifies competition between supplier apps and intermediaries |
| Vacation Packages | Dynamic assembly engines extend bundling beyond traditional tour-operator inventory |
| Other Service Types | Experiences, insurance, and ground transport become the highest-margin attach layer |
Service-type economics are diverging faster than volumes. Transportation still generates the most transactions, but the profit pool has migrated toward bundled and ancillary products where price comparison is structurally harder for the consumer.
By Booking Type
| Sub-Segment | Key Trend |
| Online Travel Agencies | Long-tail supply aggregation and subscription programs offset acquisition cost inflation |
| Direct Travel Suppliers | Loyalty currency and member-only pricing entrench owned-channel share |
The channel contest is no longer about price transparency — it is about who owns the repeat relationship. Suppliers hold the larger installed base while intermediaries grow faster by serving supply that cannot fund its own demand generation.
By Platform
| Sub-Segment | Key Trend |
| Desktop | Retains complex, high-value, and corporate itineraries where screen real estate matters |
| Mobile | App-native repeat purchase and last-minute demand drive transaction-count leadership |
Platform mix reveals a value-versus-volume split. Mobile already leads on bookings made, particularly across Asia-Pacific, while desktop continues to carry disproportionate booked value through complex multi-component trips.
By Geography
| Sub-Segment | Key Trend |
| North America | Supplier loyalty ecosystems and retail media reshape intermediary positioning |
| Europe | Regulatory density — identity wallets, package liability, platform conduct rules — defines strategy |
| Asia-Pacific | Super-app and wallet distribution bypasses standalone travel brand relationships |
| South America | Installment-credit checkout support determines conversion more than inventory breadth |
| Middle East & Africa | Giga-project hospitality supply outpaces available booking infrastructure |
Regional strategy cannot be copy-pasted. What wins in Europe — regulatory fluency and rail integration — is largely irrelevant in Brazil, where payment structure decides the sale, or in Southeast Asia, where the wallet owns the customer.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA