Segmentation Quick Reference
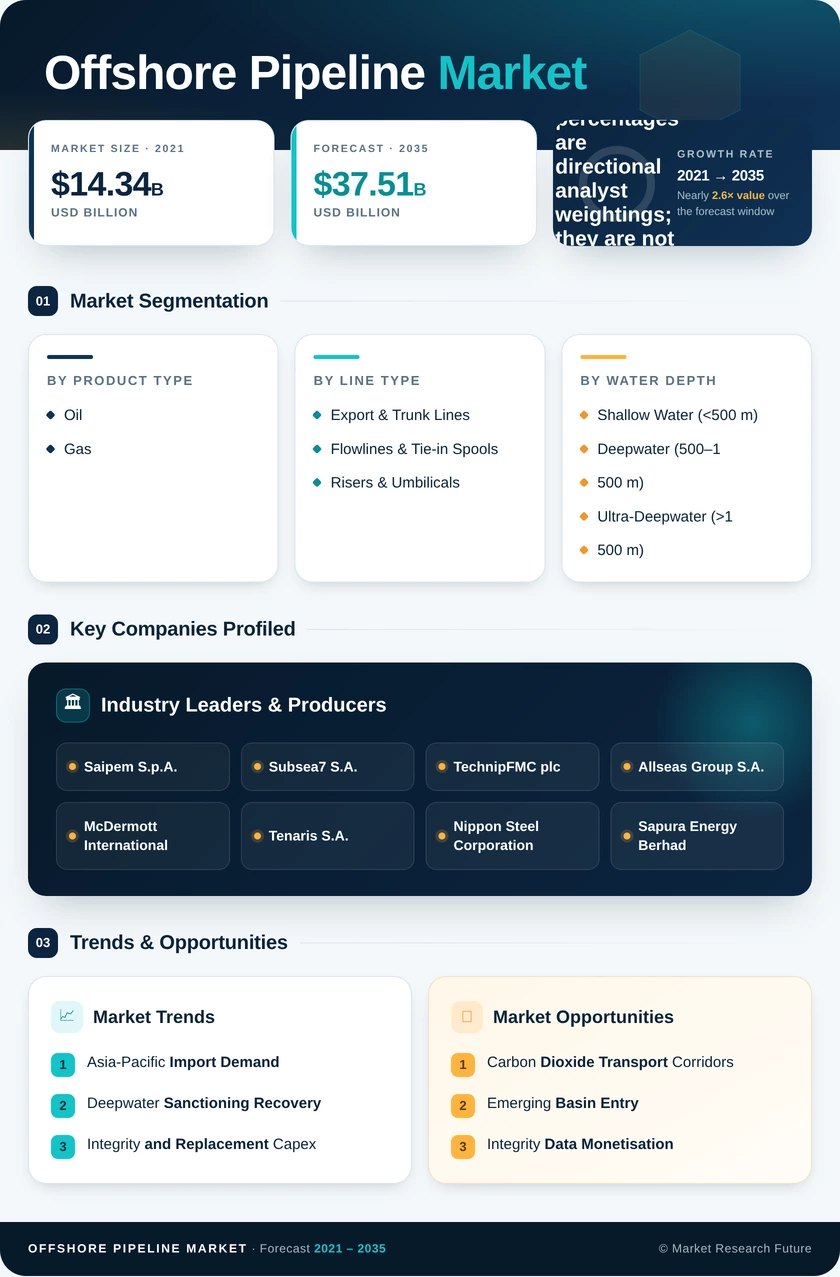
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Product Type | Oil; Gas | Oil | Gas |
| By Line Type | Export & Trunk Lines; Flowlines & Tie-in Spools; Risers & Umbilicals | Export & Trunk Lines | Risers & Umbilicals |
| By Water Depth | Shallow Water (<500 m); Deepwater (500–1,500 m); Ultra-Deepwater (>1,500 m) | Shallow Water (<500 m) | Ultra-Deepwater (>1,500 m) |
| By Geography | North America; South America; Europe; Middle East & Africa; Asia-Pacific | North America | Asia-Pacific |
Market Segmentation Overview
By Product Type
| Sub-Segment | Key Trend |
| Oil | Long-diameter export corridors sustain the largest installed value base, with replacement outpacing greenfield in mature basins |
| Gas | LNG feed-gas gathering and import diversification lift order intake, with sour-service metallurgy commanding premium pricing |
Product-type economics diverge more than volume figures suggest. Oil-service lines generate revenue through diameter and distance, while gas-service systems increasingly generate it through specification complexity — hydrogen sulphide tolerance, dense-phase fracture control and blend-readiness all raise unit value without adding a single kilometre.
By Line Type
| Sub-Segment | Key Trend |
| Export & Trunk Lines | Cross-border consenting and vessel availability, not engineering, now govern delivery schedules |
| Flowlines & Tie-in Spools | Tieback proliferation multiplies contract events, favouring contractors with reeled-lay capability |
| Risers & Umbilicals | Floating production unit orderbook drives dynamic system demand, with depth ratings climbing steadily |
Contract structure follows line type closely. Trunk-line work concentrates value in a small number of large awards vulnerable to single-project slippage, whereas flowline and riser scope arrives as a steadier stream of smaller packages that smooths contractor revenue across the cycle.
By Water Depth
| Sub-Segment | Key Trend |
| Shallow Water (<500 m) | Brownfield renewal in the Gulf of Suez, Bohai Bay and Persian Gulf anchors baseline demand |
| Deepwater (500–1,500 m) | Tieback-led development keeps breakevens competitive against onshore shale alternatives |
| Ultra-Deepwater (>1,500 m) | Pre-salt and Orange Basin expansion drives the fastest growth, constrained mainly by specialist vessel supply |
Depth determines who can bid. Below 1,500 metres, the qualified contractor pool narrows to a handful of owners with proprietary tonnage, which sustains pricing power and explains why ultra-deepwater margins hold up even when overall capital discipline tightens across the sector.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA