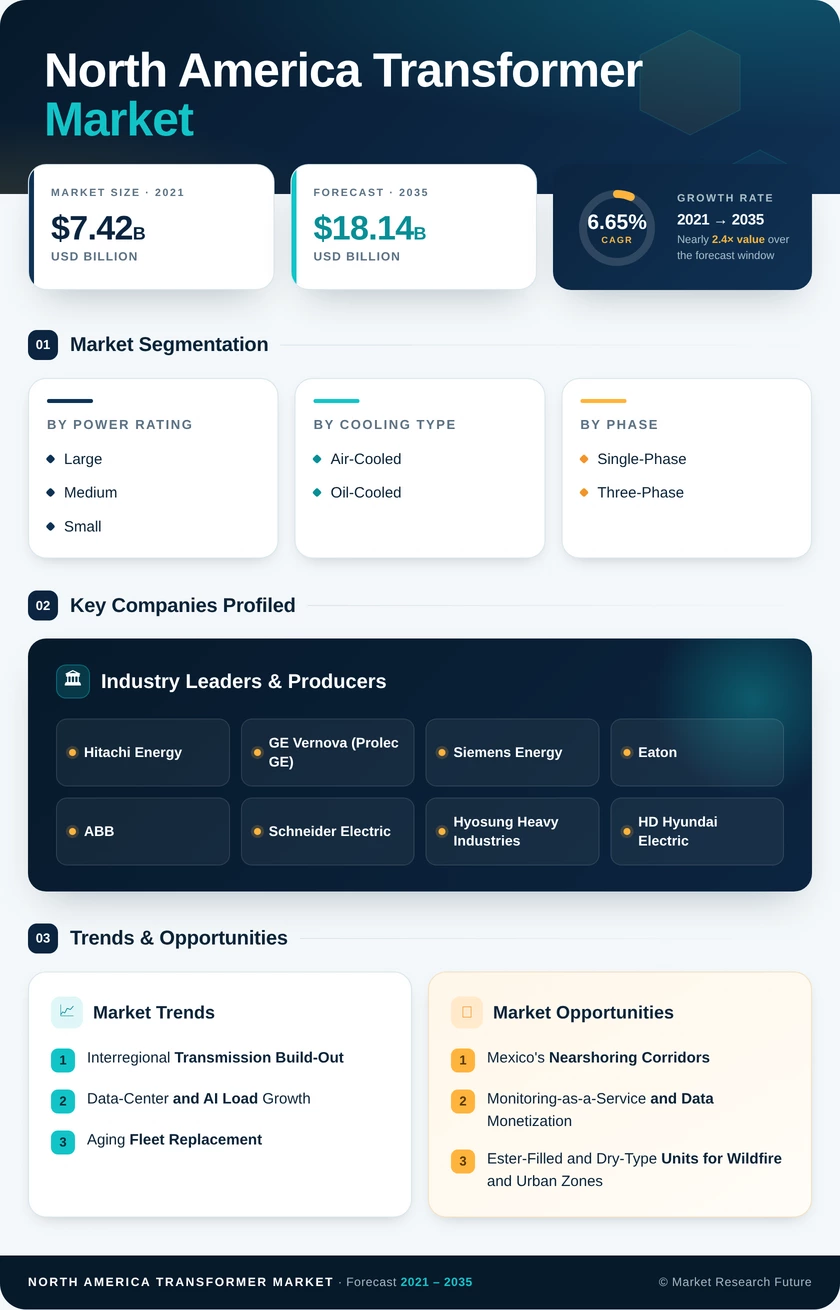
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Power Rating | Large, Medium, Small | Small (44.6% share) | Large (7.5% CAGR) |
| By Cooling Type | Air-Cooled, Oil-Cooled | Oil-Cooled (63.4% share) | Air-Cooled (7.3% CAGR) |
| By Phase | Single-Phase, Three-Phase | Three-Phase (64.8% share) | Three-Phase (64.8% share) |
| By Transformer Type | Power, Distribution | Power (51.9% share) | Power (51.9% share) |
| By End-User | Power Utilities, Industrial, Commercial, Residential | Power Utilities (54.3% share) | Industrial (7.4% CAGR) |
| By Region | United States, Canada, Mexico | United States (78.6% share) | Mexico (7.8% CAGR) |
Market Segmentation Overview
By Power Rating
| Sub-Segment | Key Trend |
|---|---|
| Large | 765 kV and HVDC projects drive orders above 100 MVA |
| Medium | Data-center and industrial substations in the 10–100 MVA range |
| Small | Feeder upsizing for EV charging and heat pumps |
Small units lead this dimension with a 44.6% share because every distribution feeder relies on them in large numbers. Large units grow fastest at a 7.5% CAGR, since a single backbone line or converter station requires several units rated well above 100 MVA. Medium ratings benefit from campus-scale substations but face supply competition as factories prioritize higher-margin Large builds.
By Cooling Type
| Sub-Segment | Key Trend |
|---|---|
| Air-Cooled | Cast-resin and VPI designs gaining in indoor sites |
| Oil-Cooled | Ester fluids replacing mineral oil in fire-risk zones |
Oil-Cooled units lead with a 63.4% share because liquid insulation handles high ratings and outdoor duty at lower cost. Air-Cooled units grow faster at a 7.3% CAGR as data centers, hospitals, and transit operators avoid oil containment and suppression requirements. Ester-filled Oil-Cooled designs slow the shift in wildfire districts but do not reverse it for indoor medium-voltage applications.
By Phase
| Sub-Segment | Key Trend |
|---|---|
| Single-Phase | Rural cooperatives upgrading pole-top units |
| Three-Phase | Industrial, transmission, and EV fast-charging demand |
Three-Phase units dominate with a 64.8% share and also grow faster because transmission substations, factories, and fast-charging hubs require balanced three-phase supply. Single-Phase units remain essential in low-density cooperative territories, generating USD 3.37 billion in 2025. Voltage imbalance from rooftop solar is prompting some rural feeder rebuilds to convert from Single-Phase to Three-Phase service.
By Transformer Type
| Sub-Segment | Key Trend |
|---|---|
| Power | Long backlogs and new domestic factories for high-voltage units |
| Distribution | Efficiency standard compliance from 2029 |
Power units hold a 51.9% share and remain the faster-growing type as interregional transmission and generator interconnection expand. Distribution units grow at a 6.0% CAGR, supported by residential electrification but tempered by the redesign effort that DOE's 2029 efficiency standard requires. Backlog asymmetry continues to pull manufacturer investment toward Power units.
By End-User
| Sub-Segment | Key Trend |
|---|---|
| Power Utilities | Risk-ranked fleet replacement and transmission portfolios |
| Industrial | Self-built high-voltage substations at data centers and fabs |
| Commercial | Dry-type units for hospitals, offices, and charging sites |
| Residential | Feeder upgrades tied to heat pumps and EVs |
Power Utilities lead with a 54.3% share, funded through regulated capital plans and federal programs such as GRIP. Industrial buyers grow fastest at a 7.4% CAGR, as hyperscale data centers and reshored factories procure their own substations to avoid utility interconnection delays. Commercial and Residential demand grows more steadily, tracking building electrification and new construction.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA